Tag: China

  • China Migrant Worker Reforms Could Unlock US$95 Billion in Spending

    China Migrant Worker Reforms Could Unlock US$95 Billion in Spending

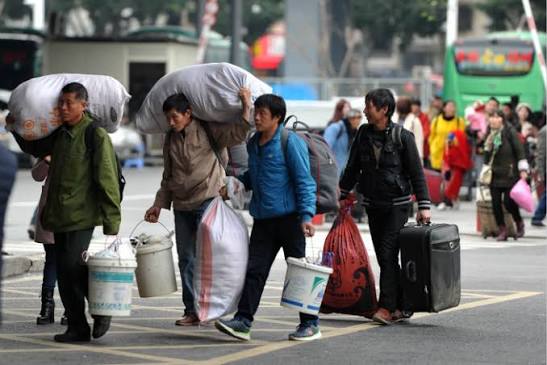
    Improving living conditions for China’s 131 million urban migrant workers could release US$95 billion annually in consumer spending, according to research released on Thursday by HSBC. That spending lift equals roughly 0.5 per cent of China’s gross domestic product.

    The bank found that the country’s broader consumption revival rests far less on high-income earners and more on easing the financial strain on urban migrant families. Mainland cities housed 130.9 million migrant workers last year, a number that expands to roughly 170 million when including dependents.

    The Savings Gap

    Precautionary financial habits keep those households from spending. Migrant workers in Chinese cities save an average of 54 per cent of their income, compared with a 36 per cent savings rate among registered urban residents. High healthcare costs, housing instability, and limited access to public services drive that defensive cash accumulation.

    Similar patterns constrain younger demographics. New workforce entrants, including recent university graduates, display elevated savings rates that restrict discretionary retail sales and leisure outlays across metropolitan centers.

    Asia Drives Consumer Expansion

    The demographic rebalancing forms part of a wider regional transformation. HSBC projects the global economy will add 1.2 billion middle- and high-income consumers by 2050. Asia will generate 77 per cent of that expansion.

    India will deliver almost half of the total regional increase. China and neighboring Asian markets will account for the remainder, cementing Asia’s position as the primary driver of worldwide consumer demand over the next two decades.

    The Shift for Retailers

    For brands and retail operators across mainland China, the findings point toward a necessary realignment. Growth will depend on mass-market volume and entry-level household goods rather than premium luxury lines that cater to top-tier wealth.

    Previous policy measures focused on subsidies and targeted tax relief for established urban households, which produced modest gains in discretionary spending. Broadening social safety nets and residency access would direct liquidity straight to essential retail categories, daily groceries, and consumer durables.

    Mainland provincial governments are now setting updated targets for municipal residency access and basic medical coverage transfers through the end of the year.
  • Speediance Signs Mark Cavendish to Lead Global Smart Fitness Push

    Speediance Signs Mark Cavendish to Lead Global Smart Fitness Push

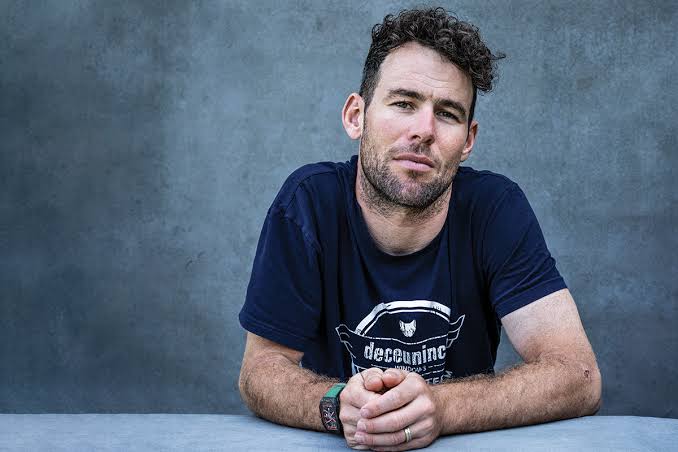
    Smart fitness equipment maker Speediance signed 35-time Tour de France stage winner Sir Mark Cavendish on September 12. Cavendish will serve as global brand ambassador for the company’s new Build for Belief campaign.

    The deal pairs the Shenzhen-founded connected gym manufacturer with cycling’s most decorated sprinter. It lands as hardware makers battle cooling post-pandemic demand for premium home workout gear.

    Speediance launched the campaign with a digital training film featuring Cavendish. The video focuses on resistance training and physical rehabilitation routines. Speediance develops digital cable resistance machines, including its flagship Gym Monster series and VeloNix stationary bike, using electronic motors instead of weight plates to adjust loads.

    Hardware Pivot to Athletic Credibility

    Bringing in an elite endurance athlete shifts the brand away from casual lifestyle marketing toward performance training. Connected fitness startups spent years targeting recreational home users with touchscreen consoles. Falling hardware margins and subscription fatigue changed that approach. Now, brands must prove real functional value to dedicated athletes.

    For retail buyers and fitness distributors across Asia and Europe, the push signals an effort to challenge commercial gym suppliers directly. Speediance must convince specialty sports retailers that multi-functional digital resistance units can win floor space from traditional free weights and stationary cardio machines.

    Defending Intellectual Property in Global Markets

    High-profile athletic endorsements also give the Chinese manufacturer clear identity in crowded Western retail channels. Distributors in Europe and North America often hesitate to stock new Asian hardware brands facing patent or design disputes from copycat rivals.

    Speediance is actively defending its industrial designs abroad. Earlier this month, the company secured an injunction in the Cologne Regional Court against rival maker AEKE over Gym Monster design infringements. Strong athlete partnerships give distributors added legal and commercial confidence when allocating prime floor space.

    Expanding Physical Retail Footprint

    Founded in 2020, the company builds compact home workout machines using direct digital motor resistance. It expanded its reach through physical concessions earlier this year, placing its Gym Monster 2s line inside Smartech flagship department stores.

    Wholesale conversion is the next major test. Speediance must now turn online marketing buzz into firm stock orders from department stores and athletic retail chains ahead of the year-end holiday shopping cycle.

  • Chinese Shoppers Ditch Supermarkets for Small Community Stores

    Chinese Shoppers Ditch Supermarkets for Small Community Stores

    Chinese consumers are ditching traditional supermarkets in favour of small neighbourhood community stores that offer low prices and instant delivery services.

    In Guangzhou, 20-something shopper Cindy Wang now stops by a local community store after work, finding it cheaper than a standard supermarket and better stocked than convenience chains like 7-Eleven.

    Discount Pricing at the Doorstep

    On an early September evening, Wang bought a bottle of milk for 7 yuan (US$1), a beer for 2.5 yuan, and mangoes priced at 10 yuan per kilogram at the newly opened outlet near her home.

    These residential outposts carry a wider assortment of fresh produce and pantry goods than traditional convenience chains like 7-Eleven. They also eliminate the commute and layout friction associated with sprawling edge-of-town hypermarkets.

    Pressure Mounts on Hypermarket Operators

    Traditional big-box chains across mainland China face structural headwinds from this shift. Large hypermarkets built on multi-tier lease models and high supplier listing fees cannot easily match the ultra-lean operating costs of ground-floor residential shops. For commercial real estate landlords, shrinking footfall at anchor supermarket tenants weakens foot traffic across entire suburban retail developments.

    Instant-delivery networks also shift bargaining use toward smaller operators. Neighbourhood storefronts function simultaneously as walk-in retail units and micro-fulfilment hubs, cutting last-mile delivery times down to minutes without the capital expense of dedicated dark stores.

    The Next Front in Grocery Competition

    The transition follows years of aggressive online penetration by instant grocery apps and group-buying platforms across major metropolitan areas. As consumer spending turns more value-conscious, physical proximity and clear price transparency carry greater weight than brand loyalty.

    Retail operators now race to secure high-density residential leases across southern China to protect market share before legacy grocery chains can reconfigure their floor space.

  • Trump Says Chinese Automakers Can Build in US Despite 100% Tariffs

    Trump Says Chinese Automakers Can Build in US Despite 100% Tariffs

    Donald Trump has stated that his administration would not block Chinese automakers from building electric vehicles in the United States, even as imports face 100 per cent tariffs.

    Speaking in September 2026, Trump indicated that Chinese manufacturers could establish assembly plants in states such as Tennessee or Alabama, despite warnings from the domestic automotive sector that local Chinese production could threaten traditional US carmakers.

    While fully built electric cars from China remain virtually barred under the existing 100 per cent tariff wall, industry analysts note that manufacturers cannot easily replicate China’s integrated parts ecosystem and low-cost supply chain in the American South.

    Supply Chain Realities in the US Market

    RetailNews Asia notes that Chinese electric vehicle brands are directing capital toward markets with clearer regulatory frameworks. Automakers such as BYD and XPENG are opening assembly hubs and distribution networks across Southeast Asia, Europe, Australia, Latin America and Africa. Those regions offer established trade corridors, predictable import policies and faster adoption rates than the North American retail market.

    For Asian parts suppliers and battery vendors, building factories in North America brings heightened political exposure. Shifts in US federal policy make long-term factory payback calculations unreliable. Expanding in ASEAN, South America and Central Europe allows Chinese automotive groups to utilize their domestic supply networks while building local retail presence near high-demand consumer clusters.

    Regional Diversification Beyond North America

    American automotive retail conditions remain difficult for foreign pure-play electric vehicle brands. Charging network rollouts in the US lag behind China and Western Europe, while consumer demand for battery-electric passenger cars has softened relative to hybrid options. Chinese original equipment manufacturers achieve better factory utilization rates by serving emerging markets across Asia and South America, where entry-level city cars face minimal competition from legacy American brands.

    Legacy US car companies have used the 100 per cent import tariff to protect sales of high-margin petrol sport utility vehicles and pickup trucks. If Chinese manufacturers establish US assembly operations, domestic producers will face direct price pressure on their home turf. That outcome would force domestic brands to accelerate their own electric platform cost reductions or surrender market share in entry-level passenger car segments.

    Tariff Walls and Industrial Strategy

    Washington escalated tariffs on Chinese electric cars to 100 per cent to shelter domestic producers from lower-cost imports. That defensive trade posture accelerated the construction of Chinese automotive plants in Thailand, Brazil and Hungary rather than drawing assembly capital into North America.

    Chinese automotive executives are tracking whether the US federal government establishes formal foreign investment security rules for automotive production sites before submitting any state-level factory applications.

  • China Gains 221 Million Formula 1 Fans as Brand Backing Lags

    China Gains 221 Million Formula 1 Fans as Brand Backing Lags

    China counted an audience of 221 million Formula 1 fans in March 2026, yet commercial brand activations across the domestic market remain largely muted despite a sold-out Shanghai Grand Prix.

    Ticket allocations for the Shanghai race cleared out immediately as a younger demographic increasingly directs discretionary spending toward live sports and experiential hospitality over traditional product purchases.

    Premium hospitality meets young consumers

    The core of luxury engagement at Formula 1 centres on the Paddock Club, an exclusive hospitality tier positioned directly above team garages that provides pit lane access and curated dining. Premium lifestyle houses use these paddock suites as private commercial salons, bringing VIP clients into high-touch environments that combine networking with entertainment.

    Global luxury conglomerate LVMH established the modern benchmark for motorsport marketing by securing a 10-year, billion-dollar worldwide sponsorship deal covering multiple brands across its portfolio. That agreement placed watches, champagne, and fashion labels directly into the race weekend ecosystem across international circuits.

    Hesitation among domestic consumer labels

    Chinese domestic labels have hesitated to commit major marketing budgets to motorsport, leaving trackside activations dominated by traditional global sponsors. Local consumer brands often prioritize short-term e-commerce livestreaming conversions over multi-year experiential sports rights that require extensive hospitality infrastructure.

    This reluctance creates an opening for European luxury groups and regional lifestyle retailers to capture high-net-worth race attendees without facing heavy counter-bidding from local players. The risk for brands sitting out the circuit is losing direct access to young, affluent consumers who view live racing as a primary cultural identifier.

    The shift toward live entertainment spend

    The current race sellouts follow years of steady motorsport audience building in mainland China, accelerated by digital streaming access and international team promotion. Younger urban consumers who cut back on conventional luxury goods are still allocating capital to ticketed trackside events and associated travel.

    Commercial focus now turns to whether local consumer electronics makers and domestic apparel groups step into paddock hospitality tiers before the next regional race calendar locks in multi-year partner rosters.

  • BYD Denza Launches All-Electric N8L SUV Priced from 299,800 Yuan

    BYD Denza Launches All-Electric N8L SUV Priced from 299,800 Yuan

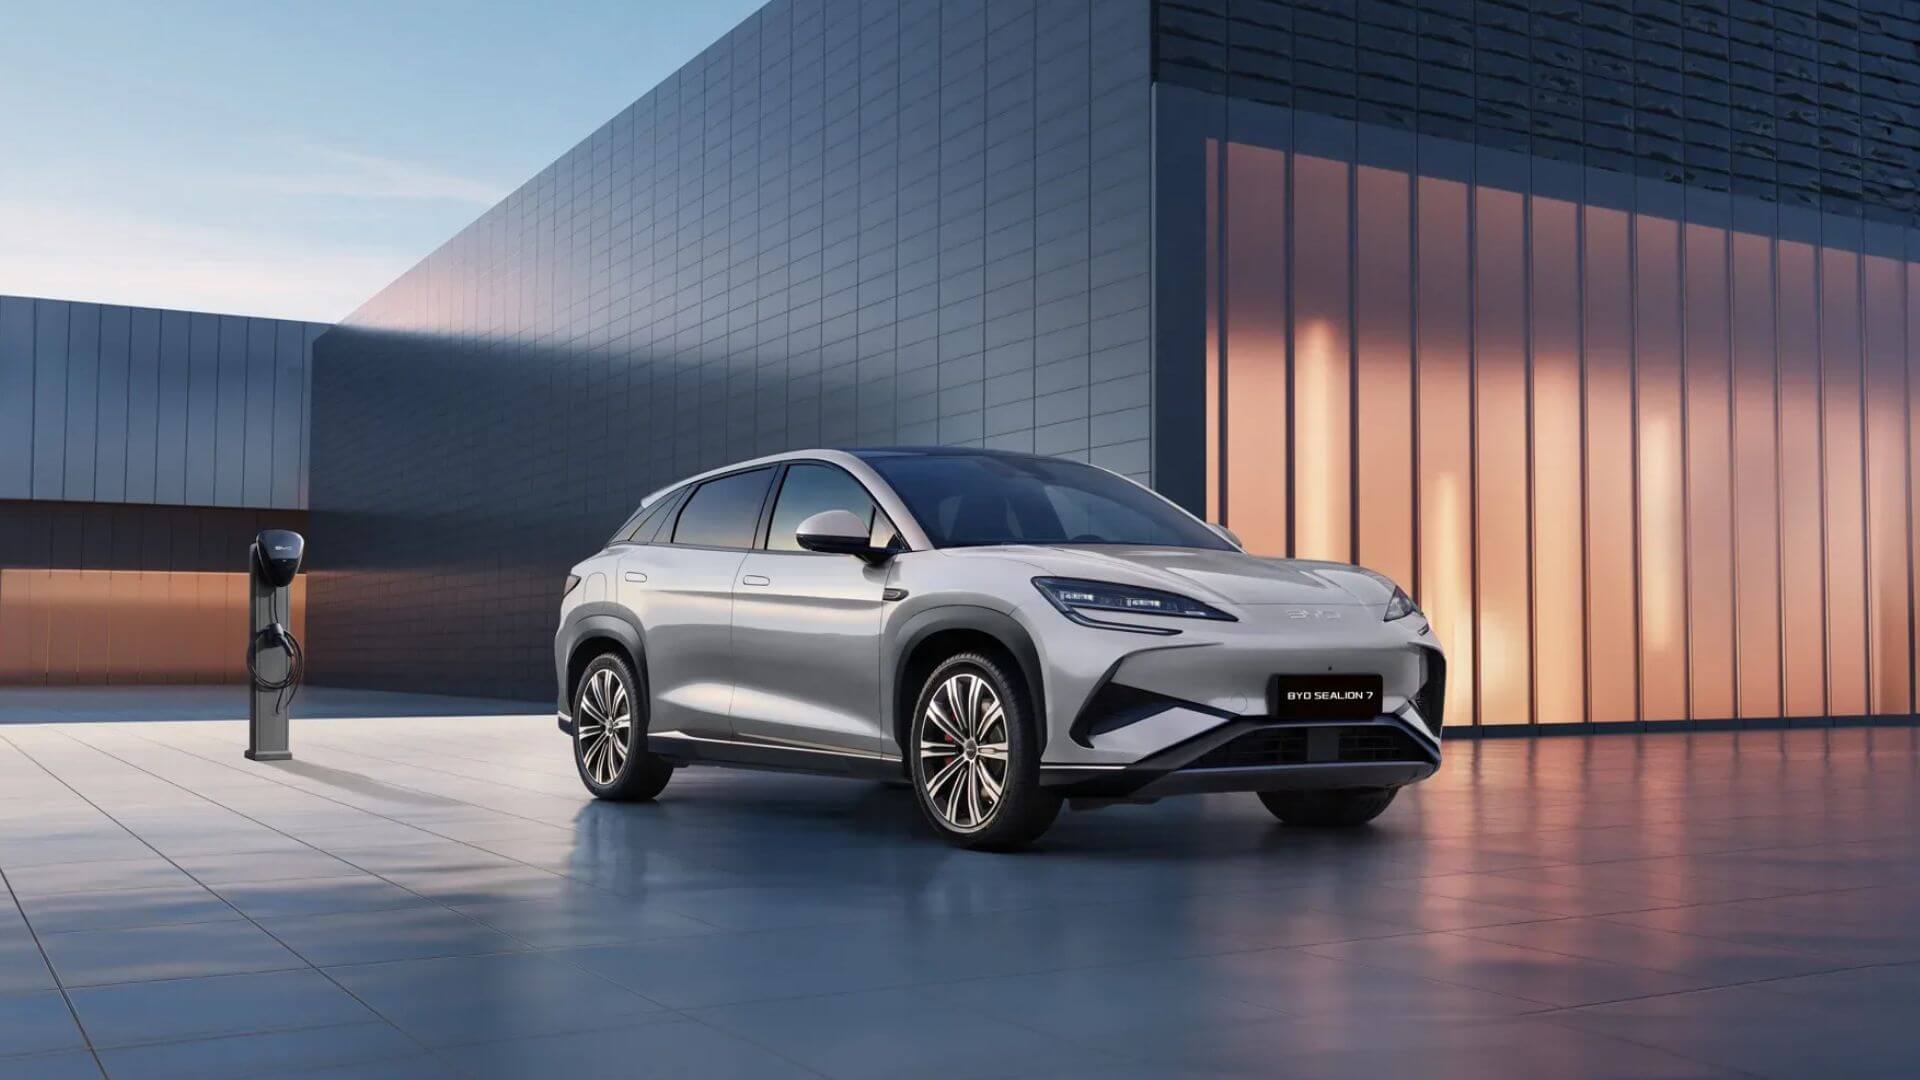
    BYD rolled out the battery-electric version of its Denza N8L sport utility vehicle in China on Monday, pricing the large six-seater from 299,800 yuan ($44,280).

    The launch introduces a pure electric drivetrain to a flagship family model that previously sold only as a plug-in hybrid, undercutting the hybrid edition’s starting price by 20,000 yuan.

    Battery Power and Fast Charging Hardware

    Denza sells the new all-electric SUV in two configurations. The entry Flash Charging Prestige costs 299,800 yuan, while the higher-spec Flash Charging Flagship retails for 329,800 yuan. Both variants use an 800-volt electrical architecture paired with a 130.15-kilowatt-hour second-generation Blade Battery, delivering a driving range of up to 960 kilometres under China Light-Duty Vehicle Test Cycle standards.

    Propulsion comes from a single rear-mounted electric motor rated at 370 kilowatts, or 496 horsepower. At BYD flash charging stations, the system pushes battery state from 10 per cent to 70 per cent in five minutes, and reaches 97 per cent in nine minutes.

    Body measurements match the hybrid predecessor exactly. The chassis measures 5,200 millimetres in length, 1,999 millimetres in width and 1,820 millimetres in height, riding on a 3,075-millimetre wheelbase with a three-row, six-seat interior. Storage includes a 208-litre powered front trunk equipped with a drainage plug for wet gear. Standard driving hardware incorporates rear-wheel steering that trims the turning radius to 4.58 metres, dual-chamber air suspension, continuous damping control and a roof-mounted LiDAR unit running the God’s Eye 5.0 driver assistance package.

    Shifting Family Buyers Toward Pure Electrics

    By pricing the pure electric model below the plug-in hybrid version, Denza is rewriting the traditional price ladder in China’s premium three-row segment. Automakers historically charged heavy premiums for massive 130-kWh battery packs. BYD is using its vertical cell manufacturing scale to absorb those costs and squeeze rivals such as Li Auto and Nio, forcing competitors to defend margins across the 300,000-yuan family SUV bracket.

    The commercial success of the vehicle relies directly on BYD’s ability to maintain high charging speeds away from urban showrooms. A 960-kilometre nominal range eases highway anxiety, but deploying ultra-fast power cabinets across key highway arteries is what will convince combustion-engine owners to ditch petrol backups for family transport.

    Building Out the N8L Lineage

    Denza introduced the original N8L nameplate in October 2025 as a dedicated plug-in hybrid. The brand updated that hybrid in June with a 75.26-kWh second-generation Blade pack offering 430 kilometres of electric range and flash charging capability, priced at 319,800 yuan.

    BYD operated 10,000 flash charging stations across China as of late August and expects to reach 20,000 operational stations before the end of December.

  • China Aims for $8.94 Trillion in Retail Sales as Price Wars Persist

    China Aims for $8.94 Trillion in Retail Sales as Price Wars Persist

    China’s physical retailers are retooling floor space into leisure and entertainment hubs to counter entrenched price competition as Beijing targets $8.94 trillion in annual consumer sales by 2030.

    First-half retail sales reached $3.7 trillion, but Bain & Company partner Weiwen Han warns the market will stay muted over the next three years as discounting continues to squeeze operating margins across shopping centres and supermarket chains.

    Experience Costs and Margin Pressures

    Official policy guidelines urge store operators to blend standard shopping with immersive dining, social spaces, and entertainment. The strategy shifts the industry away from chasing raw foot traffic toward extracting higher margins from shoppers who do enter. Transforming selling space into experience zones raises the fixed cost per square metre, penalising operators whose foot traffic fails to convert at the cash register.

    The policy combines experience-led flagships in commercial districts and transit hubs with neighbourhood infrastructure upgrades dubbed 15-minute life circles. These local clusters focus on daily essentials through convenience stores, supermarkets, and wet markets.

    Digital Convergence and Supply Chains

    Pure physical retail has ceased to exist in the Chinese market. With online sales of physical goods rising 4.8 per cent year to date compared to 1.3 per cent growth for total retail sales, shoppers routinely compare shelf prices against live e-commerce listings on their phones within seconds.

    Instead of trying to defeat digital platforms on pricing, operators are adopting automated inventory systems, drone delivery, and private-label merchandise. Developing proprietary private-label lines allows chains to offer price value directly without slashing headline gross margins on national brands.

    “They are asking stores to be worth visiting for reasons beyond price,” said Jotham Lim, head of global marketing at Beijing Taomi Technology Co. Ltd.

    Winners and Structural Consolidation

    Mid-sized domestic grocery, convenience, and food and beverage operators stand to gain the most from planned regional deregulation, which removes long-standing barriers preventing chain retailers from expanding across provincial borders. Independent single-store merchants face steep hurdles absorbing the capital expenditure required for digital traceability and store fit-outs, accelerating industry consolidation into regional chains.

    Financing rules now allow qualifying retail operators to raise capital through asset-backed securities and commercial real estate investment trusts, alongside interest subsidies from commercial banks. Landlords and property-owning retailers can tap these vehicles to fund store refits without burning operating cash flow.

    The retail sector entered this transition carrying heavy overcapacity in commercial floor space following decades of rapid mall construction across second- and third-tier cities. Moojing Market Intelligence recorded a steady increase in consumer discussions regarding in-store price checking against e-commerce platforms between the first half of 2024 and the first half of 2026.

    Market operators now face the rollout of regional licensing reforms and the government target to lift retail sales from ¥24.87 trillion to ¥60 trillion over the next four years.

  • Over 90 per Cent of Luxury Consumers Seek Experiences Beyond Products

    Over 90 per Cent of Luxury Consumers Seek Experiences Beyond Products

    More than 90 per cent of luxury consumers now seek brand experiences outside the product itself, including hospitality, travel, dining, and wellness, according to a 2026 report by MG2 Advisory.

    Craftsmanship remains the primary purchasing driver for 62 per cent of buyers, yet luxury houses such as Hermès, Gucci, and Kith are increasingly evaluated on the ongoing relationships and environments they build around their goods.

    More than three-fourths of respondents associate luxury with rarity and exclusivity, while nearly half expressed interest in private, members-only spaces and repair services that preserve product value.

    Hospitality reshapes flagship formats

    Houses are reacting by building operational ecosystems that extend past apparel and leather goods. Kith opened its members-only Ivy concept to integrate sport, dining, and retail, while Gucci expanded its culinary presence through Gucci Osteria da Massimo Bottura. In London, Hermès opened its sixth Hermès Maison concept store, replicating mixed hospitality and retail formats already operating in Tokyo, Seoul, Shanghai, Paris, and New York.

    For prime landlords across Asia-Pacific, this shift changes leasing economics entirely. Retailers no longer evaluate store footprints solely on sales density per square metre. Instead, top-tier brands require larger floorplates to accommodate private client salons, cafes, and preservation workshops, forcing mall operators in Hong Kong, Singapore, and Tokyo to reallocate prime ground-floor space from transactional sales to experiential services.

    The operational risk sits squarely in execution. Running fine dining, bespoke tailoring, and hospitality requires different supply chains and labour models than selling boxed leather goods. When service levels in brand-run restaurants or repair centres slip, the reputational damage flows directly back to the core fashion label.

    After-care moves to the balance sheet

    Post-purchase services have evolved from back-office cost centres into client retention mechanisms. Hermès and Louis Vuitton have reinforced dedicated repair units to extend product lifespans, while Coach runs its circular (Re)Loved restoration and resale division across major retail markets.

    Physical flagships in major regional capitals will increasingly reflect this split between exhibition and maintenance. The next metric to watch is whether luxury groups maintain capital expenditure for multi-floor experiential maisons as store construction costs and prime commercial rents across Asia climb through late 2026.

  • Rainbow Opens Shenzhen Supermarket Fitted with 17,000 IoT Devices

    Rainbow Opens Shenzhen Supermarket Fitted with 17,000 IoT Devices

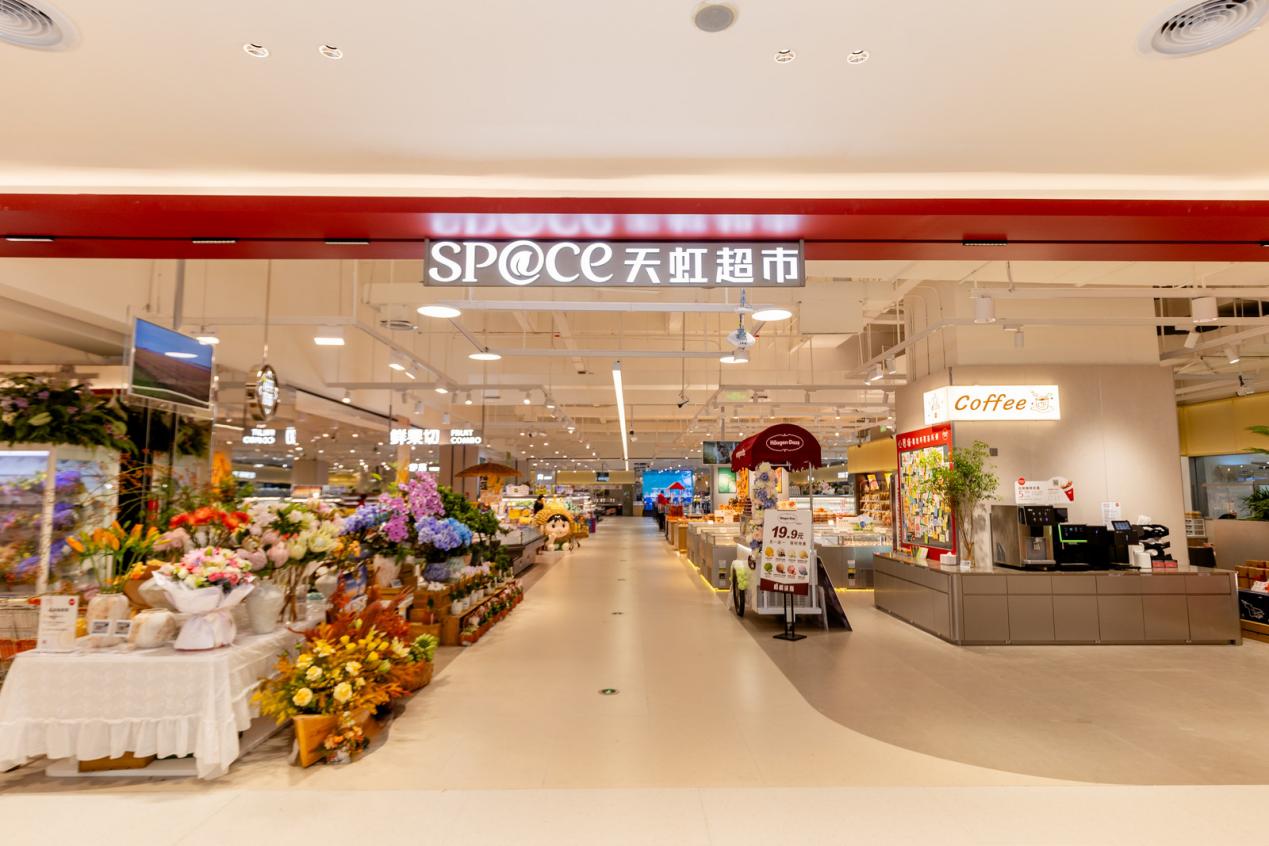
    Rainbow opened its upgraded Shahe sp@ce supermarket in Shenzhen on September 8, deploying more than 17,000 connected IoT devices across the trading floor. The project turns a 17-year-old site in Nanshan District into Rainbow’s first operational store digital twin, linking physical shelf monitoring directly to automated inventory orders and home-delivery packing.

    The retailer developed the system with electronic shelf label supplier Hanshow and its own technology arm, Lingzhi Digital Technology. Hanshow Nebular Ultra electronic labels provide centimeter-level shelf positioning and tap-to-read product provenance for customers, while automated cameras and robotics track out-of-stock items along the aisles. Lingzhi’s proprietary Bailingniao retail artificial intelligence model processes the visual data to adjust replenishment orders and assign tasks to store clerks.

    Smart Carts and Micro-Fulfilment at Shahe

    Shoppers navigating the nine food and lifestyle zones use Hanshow NexConnect smart carts fitted with Lingzhi’s AI assistant for in-store mapping, item lookups and self-checkout. The store also houses a dedicated micro-fulfilment center built to assemble and dispatch online grocery deliveries directly from the back room.

    Our goal with sp@ce 3.0 is to create a better everyday shopping experience built on quality, freshness, transparency and trust. As Rainbow’s first Store Digital Twin-enabled store, the Shahe sp@ce supermarket brings digital visibility into day-to-day operations, helping our teams respond faster and more accurately, while allowing store employees to spend more time on the service and experiences that matter to customers.

    How the Model Cuts Labour and Inventory Friction

    Chinese supermarket chains have spent five years testing automated checkout and camera-based shelf scanning, but most systems remain isolated experiments that alert staff without solving stocking bottlenecks. Rainbow is attempting to connect real-time shelf telemetry directly to supply forecasts, removing manual inventory counts entirely from daily shopfloor routines.

    For suppliers and distributors, the shift to automated replenishment leaves little room for negotiated shelf space or delayed delivery windows. If a supplier fails to restock within the algorithm’s timetable, the system flags the gap immediately. The risk sits in hardware maintenance across thousands of sensor endpoints, where battery depletion or sensor misalignments can distort automated ordering across an entire product category.

    The Trajectory of Rainbow’s Digital Formats

    Rainbow has spent several years reformatting its traditional department stores and community retail centers across China into mixed-use lifestyle hubs. The Shahe project follows Hanshow’s earlier shelf-monitoring rollouts and the launch of its xPilot retail platform in June 2026.

    Operators across southern China will now watch whether the sensor-dense model delivers measurable margin gains or simply inflates store fit-out capital expenditure ahead of Rainbow’s planned rollouts to other sp@ce locations.

  • Xi Visits India for First Time in Seven Years as Business Ties Stall

    Xi Visits India for First Time in Seven Years as Business Ties Stall

    Chinese President Xi Jinping arrived in New Delhi this week for his first visit to India in seven years, facing entrenched regulatory barriers that continue to block major bilateral investments.

    Cross-border commercial projects remain frozen across consumer electronics, automotive manufacturing and financial services despite tentative diplomatic progress at the annual BRICS summit.

    Indian authorities have blocked a proposal by Ant Group affiliate Alipay to connect to the domestic instant payments system on national security grounds. Regulators are also reviewing a recommendation by the Serious Fraud Investigation Office to investigate smartphone vendor Xiaomi over alleged foreign investment law breaches. Xiaomi stated it complies with all local regulations and has received no notice from investigators.

    Carriers and Factories Caught in Scrutiny

    Industrial hurdles run both ways across the border. Vehicle makers BYD and Great Wall Motor shelved planned manufacturing outlays in India following heightened regulatory checks from New Delhi, while Beijing has instructed domestic suppliers to withhold shipments of critical mobile manufacturing equipment, solar panels and port hardware.

    Heavy industrial machinery remains caught in transit. Massive Chinese tunnel-boring machines designated for Indian urban transit and infrastructure sites have sat stranded at customs checkpoints for more than a year, while business executives from both sides report recurring visa rejections.

    Supply Chains Face use Risks

    For consumer electronics vendors and appliance assemblers, the standoff keeps operating costs elevated across South Asia. Indian contract manufacturers rely heavily on Chinese tooling and sub-assemblies to feed domestic assembly lines, leaving production schedules exposed whenever border customs tighten component inspections.

    Suppliers attempting to build local joint ventures face a double squeeze. Beijing now subjects outward technology transfers to stricter internal reviews, while New Delhi retains case-by-case screening on foreign capital from bordering nations even after easing rules for select solar and capital goods ventures in March.

    China has economic heft and there is a good opportunity to use that and emerge as a reliable partner, especially when both nations are impacted by America’s trade policies.

    The Path Since Galwan

    Bilateral economic relations chilled after a 2020 border clash in the Galwan Valley resulted in casualties on both sides, prompting New Delhi to ban hundreds of Chinese apps and restrict direct foreign investment. Direct commercial flights between the two countries resumed last year alongside an initial pilot easing business visa clearance protocols.

    A preliminary assembly partnership between India’s Dixon Technologies and handset maker Vivo Mobile secured formal clearance following those initial concessions. Whether additional industrial joint ventures gain clearance now hinges on the scheduling of a formal bilateral meeting between Prime Minister Narendra Modi and Xi before the summit concludes.

  • Malbon Golf Expands in China with Stores in Shanghai and Beijing

    Malbon Golf Expands in China with Stores in Shanghai and Beijing

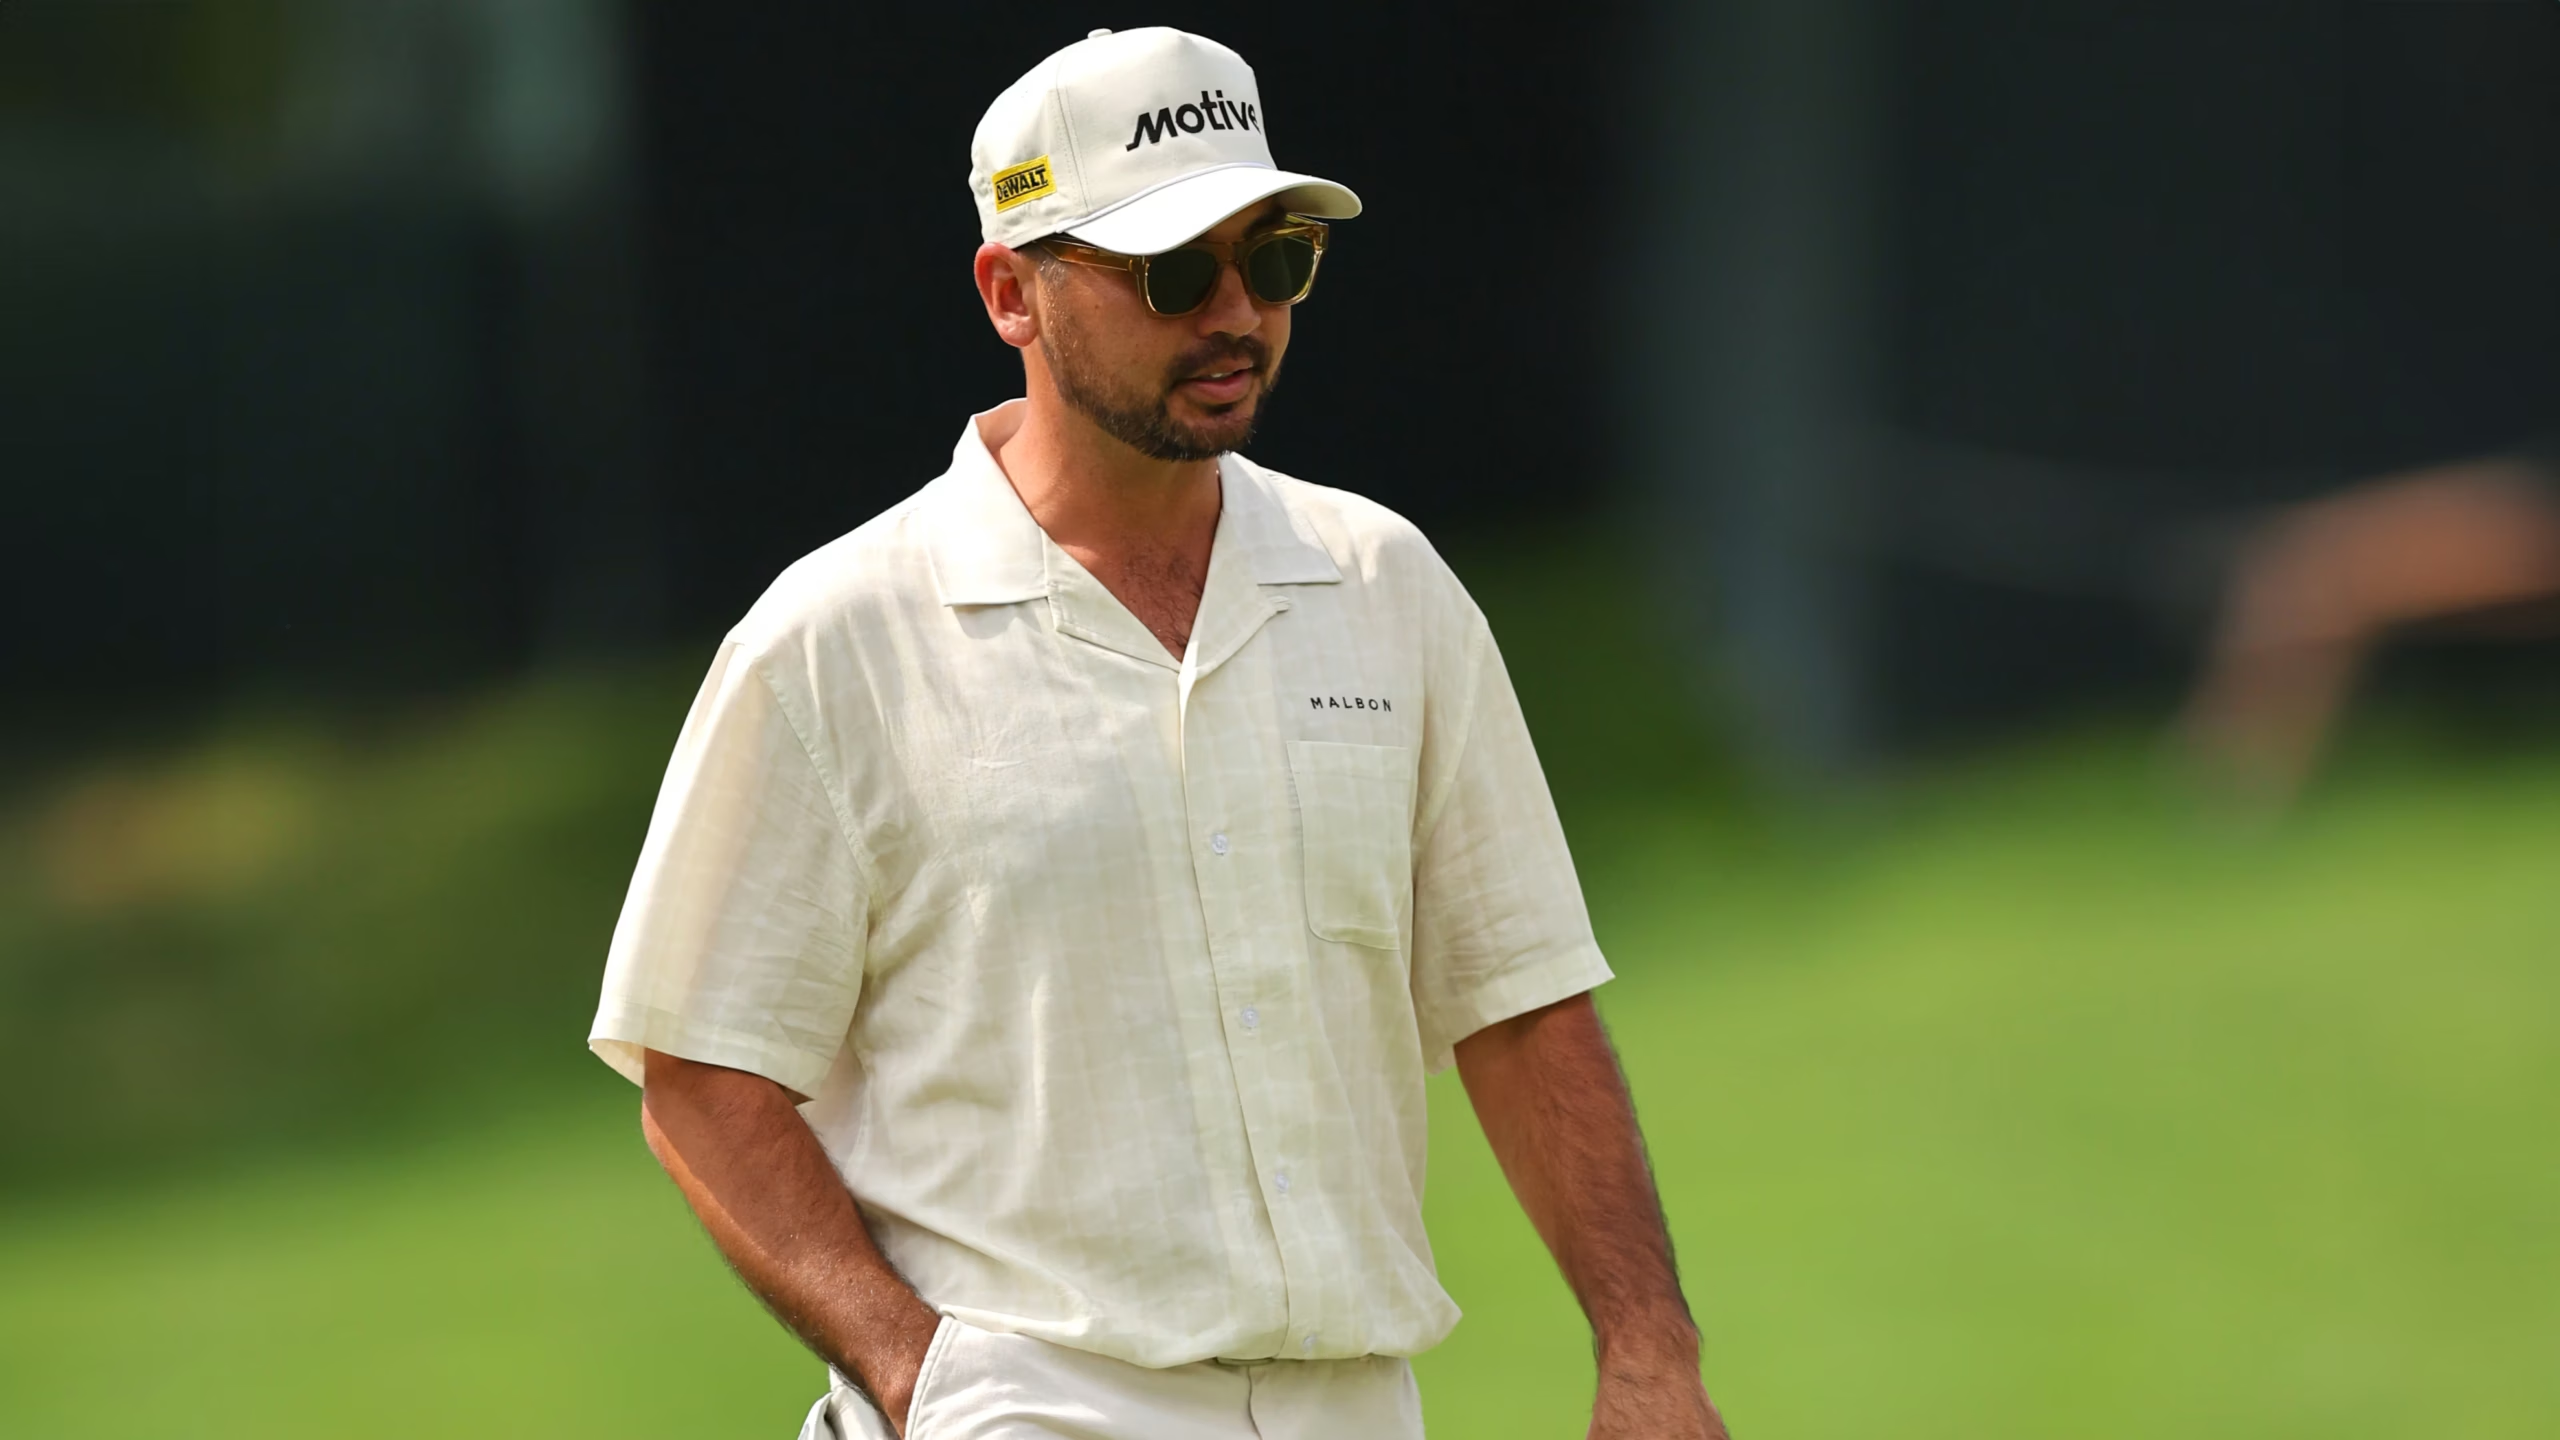
    US golf lifestyle brand Malbon Golf is expanding its retail presence in China with locations in Shanghai and Beijing as part of its broader market expansion strategy.

    Founded in Los Angeles in 2017, the company has partnered with TKG Lifestyle to support its rollout, with Hangzhou and Shenzhen among the next markets in its pipeline.

    Tier-one footprint and localized store designs

    Earlier this year, the brand opened its first Mainland China flagship at Shanghai’s Jing’an Kerry Centre, followed by a second location in the West Bund and a store at Beijing’s Taikoo Li Sanlitun.

    Its Shanghai stores combine golf and streetwear aesthetics with references to local culture, with the West Bund site incorporating vintage imagery, creative elements, and interactive golf features. The Taikoo Li Sanlitun store in Beijing features localized design elements alongside city-specific apparel and lifestyle collections.

    The streetwear crossover in Chinese sports retail

    China-exclusive products form part of the company’s local strategy, with city-specific collections developed alongside its core golf apparel and accessories. Malbon’s partnership with TKG Lifestyle also extends to other regional markets, including Vietnam and the Philippines.

    Earlier expansion steps

    Malbon operates at the intersection of golf and lifestyle fashion, with collections and collaborations spanning apparel, accessories, and cultural partnerships since its founding in 2017. The planned expansion into Hangzhou and Shenzhen will further extend the label’s footprint across major Chinese cities.

  • Seven China IPOs Hand Retail Investors over 100,000 Yuan This Year

    Seven China IPOs Hand Retail Investors over 100,000 Yuan This Year

    China’s boom in initial public offerings has handed individual investors first-day trading profits exceeding 100,000 yuan ($14,900) across seven separate stock debuts this year.

    The run represents the most six-figure retail listing windfalls in at least six years. Investors who secured standard 500-share allocations and sold on debut day captured gains equivalent to six months of salary in a single day.

    Robotics and Tech Lead the Surge

    Individual investor Stacy Wei earned about 380,000 yuan after securing an allocation in the listing of Unitree Robotics and selling on debut day, enough to upgrade to her dream car.

    Hardware manufacturers and artificial intelligence supply-chain companies continue to draw the heaviest speculative retail subscriptions across domestic exchanges. Bidders flip shares instantly rather than holding long positions, treating mainland debut pops as liquidity events rather than valuation anchors.

    Shifting Liquidity in Mainland Markets

    Institutional allocators face a different calculation. While retail flippers bank quick cash, fund managers buying secondary tranches absorb the risk of sharp post-debut pullbacks once initial euphoria clears from the order book.

    Sellers who take profits on opening day bypass subsequent price volatility. That trading pattern concentrates quick consumer liquidity in Tier 1 and Tier 2 cities, diverting trading gains directly into private purchases and big-ticket household spending.

    The Trajectory of New Offerings

    Regulators spent recent quarters calibrating the pace of new equity issuance to stabilise broader secondary market indices. That restricted pipeline funnelled intense speculative capital into the select batch of tech and robotics candidates cleared for listing.

    Trading desks now track subscription ratios for the next pipeline of advanced manufacturing and consumer tech filings scheduled for domestic exchange review this autumn.

  • Global Finance Names Winners of 19Th Annual Stars of China Awards

    Global Finance Names Winners of 19Th Annual Stars of China Awards

    Global Finance revealed the winners of its 19th annual Stars of China Awards on Thursday. The program recognizes commercial banks, fintech providers, and asset management firms across the mainland.

    The annual index benchmarks institutions navigating domestic economic adjustments. It measures operational strength, capital stability, and credit deployment to key industrial sectors.

    Lending Shifts Toward Industry and Tech

    State-owned lenders and regional commercial banks have redirected credit lines away from traditional real estate developers. Capital now flows toward high-end manufacturing, small businesses, and technology ventures. This shift mirrors policy directives from Beijing aimed at stabilizing production while consumer spending recovers at an uneven pace.

    Retail and consumer brands operating in China find their working capital tied directly to these institutional priorities. Supply chain operators, logistics networks, and hardware developers continue to secure competitive borrowing terms. Purely consumer-facing discretionary merchants face tighter credit underwriting from regional lenders.

    China’s resilient economy continues to face challenges from weak domestic demand and the property sector, but policy support, steady industrial activity, and efforts to stimulate lending provide reasons for cautious optimism. The country’s largest banks remain well capitalized and are expanding lending to manufacturing, technology, and small businesses.

    Balancing Property Drag and Small Business Credit

    Asset managers and commercial banks operate amid subdued domestic demand and persistent liquidity stresses in commercial real estate. Even with those pressures, core tier-one capital ratios at China’s top commercial institutions remained steady throughout the year.

    Evaluators assessed cross-border capabilities alongside domestic performance, tracking how Chinese firms handle outbound trade and currency settlement across the Asia-Pacific region. Trade corridors linking mainland suppliers with Southeast Asian retail networks serve as a primary growth driver for trade finance desks.

    Full Report Slated for November Release

    Global Finance founded the China-focused evaluation 19 years ago to track performance inside the world’s second-largest economy. The publication reaches 50,000 corporate and financial decision-makers across 196 countries.

    Full winner lists and the ranking of the Safest Banks in China will run in the November print and digital editions, ahead of an in-person awards ceremony in Beijing later this autumn.

  • GAC Signs Villarreal CF Sleeve Sponsorship to Back European Electric Vehicle Push

    GAC Signs Villarreal CF Sleeve Sponsorship to Back European Electric Vehicle Push

    Guangzhou Automobile Group signed an official automotive partnership with Spanish football club Villarreal CF on September 10, 2026, securing shirt sleeve branding across European competition.

    Under the agreement signed at the Estadio de la Cerámica, the Chinese automaker’s logo will appear on the left sleeve of Villarreal’s first-team shirts during domestic LaLiga fixtures and UEFA Champions League matches.

    Sleeve Sponsorship and EV Lineup

    GAC is tying the football partnership directly to the rollout of two battery-electric passenger models aimed at European drivers. The carmaker plans to feature the AION V, an electric sport utility vehicle tailored for family buyers, alongside the AION UT, a compact electric hatchback designed for urban commuting.

    Match-day activations, digital campaigns and fan events across Spain and broader tournament stops will give prospective buyers direct access to both vehicles. Placing the brand on a squad competing in continental club tournaments offers immediate television exposure across core Western European markets where Chinese automotive nameplates still struggle with consumer familiarity.

    The European Market Play

    Securing football inventory has become the standard playbook for Chinese electric vehicle manufacturers seeking rapid legitimacy in Europe. BYD took official tournament partner status for UEFA Euro 2024, and GAC is now deploying a similar sponsorship model at club level to bypass the slow, expensive grind of building retail recognition from scratch.

    For dealership groups and fleet buyers across Europe, the sponsorship signals that GAC is committing marketing capital rather than testing the waters with low-volume imports. The commercial risk sits in conversion: high-profile stadium exposure creates top-of-funnel awareness, but turning match viewers into EV buyers requires competitive financing packages, dense service networks and spare parts availability that Chinese brands must build on the ground.

    Expanding the Global Network

    The European push follows earlier sports marketing initiatives by GAC in Latin America and aligns with the company’s broader One GAC 2.0 strategy. That framework divides international expansion across target territories in Asia-Pacific, the Middle East, Africa, Europe, the CIS and Latin America through localized sales channels and aftersales operations.

    Attention now shifts to the commercial deployment of the AION V and AION UT across regional dealer networks, alongside the establishment of certified local repair centers before tournament group matches get underway.

  • Fast Retailing Names James Kelly as Global CEO of Theory

    Fast Retailing Names James Kelly as Global CEO of Theory

    Theory appointed James Kelly as its global chief executive officer, elevating the former Fast Retailing executive after two years in senior leadership at the New York-based fashion brand.

    Kelly takes over from Dinesh Tandon, who led the label globally since 2019 and now returns to run Theory China while serving as global co-chief operating officer alongside Serena Peck.

    Leadership reshuffle across two labels

    In his new post, Kelly assumes oversight of both Theory and sister label Helmut Lang. His remit covers global headquarters functions, commercial operations and international expansion.

    Kelly joined Theory in 2022 as chief financial officer before stepping into the global co-chief operating officer role. Prior to that, he spent years inside Japanese parent group Fast Retailing, where he directed store network expansion for Uniqlo across the United States and Canada.

    Sharpening focus on Asian retail operations

    Splitting global commercial control while sending Tandon directly back to helm China operations shows how Fast Retailing is organizing its premium brands around Asian retail demand. Putting an experienced operator on the ground in China gives the Japanese group closer operational control over store productivity, concession partnerships and local inventory allocation in a highly competitive market.

    For competing contemporary fashion labels across East Asia, the management shift signals an aggressive push from Fast Retailing to scale its higher-margin portfolio. Theory provides Fast Retailing with access to affluent office workers who want technical tailoring, a segment where traditional European designer labels face margin pressure at entry-level price points.

    Two decades under Japanese ownership

    Andrew Rosen and Elie Tahari founded Theory in New York in 1997, building the brand on stretch-fabric tailoring and contemporary workwear. Japanese licensee Link International acquired the company in 2003, and Fast Retailing took full ownership of the business in 2009.

    Link Theory Holdings had previously purchased Helmut Lang from Prada Group in 2006, creating the high-end apparel pillar that sits alongside Fast Retailing’s mass-market Uniqlo and GU banners.

    Commercial execution to watch

    Retail observers will track Tandon’s store rollout and comparable-sales performance across mainland China’s department store network, alongside Kelly’s progress in turning Helmut Lang into a steady profit generator.