Tag: #growth

  • Jack Ma calls 12-hour work days a “blessing”

    Jack Ma calls 12-hour work days a “blessing”

    In the middle of stress awareness month, Alibaba founder Jack Ma has told his company’s workers they should be working a “996” work schedule – that is from 9am to 9pm, six days a week.

    According to a speech made this week by Ma, working 12 hours a day for Alibaba was a “blessing” to staff, and necessary for the business to achieve success.

    Ma’s comments caused a stir in China, where a conversation about work-life balance has spring-boarded off of a slowing tech industry.

    “With the pressure of economic downturn, many enterprises are facing challenges to survive… but the way to relieve anxiety is not to let employees work overtime as much as possible,” an editorial wrote.

    Ma later backtracked on his comments, calling such a work regime inhumane, unhealthy and unsustainable.

    The comments come as LinkedIn revealed work-life balance is the top cause of stress at work for Australians, with 72 per cent of survey respondents struggling to keep a balance between the two.

    The report also found that executive-level professionals are the most stressed, more so than middle management and individual contributors.

    In terms of age demographic, Generation X is the most stressed generation with over half (54 per cent) claiming to struggle with confidence in the future of their work.

  • Credit growth limited at 15% for best banks in 2019

    Credit growth limited at 15% for best banks in 2019

    HÀ NỘI The State Bank of Vietnam (SBV) has assigned a credit growth limit to each commercial bank in 2019, with priority given to those who met Basel II’s capital safety and risk management standards ahead of schedule.

    According to the current regulation, the SBV sets a credit growth limit for the entire year for each bank – depending on its health – to ensure the credit growth target of the entire banking system during the year (14 per cent for 2019).

    This year, the highest credit growth limit of 15 per cent was assigned to the group of banks which met the Basel II’s standards earlier than the SBV’s deadline of 2020. The remaining banks, meanwhile, were allocated a lower rate of below 12 per cent.

    Last year, most banks were assigned higher credit growth limits, ranging from 14 per cent to 16 per cent.

    The credit growth target of the entire banking system and of each bank has tended to slow in the past two years. Experts attributed the slowdown to the SBV’s policy changes. Previously, due to the underdevelopment of the local stock market, banks, which should act only as intermediaries in the monetary market, had to function to fund medium- and long-term capital for the economy.

    However, the SBV has tried to gradually change the role of banks so as to make them fund only short-term capital for the economy through the provision of working capital loans for businesses and households.

    To make the change, the SBV required banks to lower the ratio of short-term funds for medium and long-term loans from 45 per cent in 2018 to 40 per cent since early this year.

    Experts have also agreed with the credit growth slowdown, saying it was necessary to improve banks’ credit quality and risk management.

    Nguyễn Xuân Thành from Fulbright University Vietnam said currently, the pressure on credit growth to support economic growth was not so high, so the allocation of a credit limit to each bank depending on its health was reasonable. Accordingly, banks should only boost credit in case of good control of risks, in order to ensure sustainable growth.

    To offset the revenue reduction from lending activities, banks said they plan to increase profits through cutting operating costs and promoting digital services.

    Đỗ Minh Phú, chairman of TPBank, said digital banking would play a major role in reducing operating costs and increasing the cost-to-income ratio (CIR) efficiency, contributing to improving the bank’s profits this year.

    Phú said the biggest costs in banking operations were the costs of network investment and development, along with the costs for personnel, which could be solved by the application of digital banking. Attracting customers to non-credit services and service fee collection was also becoming a trend.

    Sharing the same view, Nghiêm Xuân Thành, chairman of Vietcombank, said that 2019 would be the year of digital banking for Vietcombank. In the past three years, the bank had focused on investment and implementation of a new core banking system to boost service development and shift the revenue structure instead of relying heavily on credit.

    Developing digital banking combined with retail banking in a potential market of 95 million with a high percentage of young people means commercial banks were quickly accumulating a customer base and large payment needs, Thành said.

    The focus on digital banking combined with retail banking has also helped some banks, like Vietcombank, Techcombank and HDBank, increase their number of individual customers rapidly in recent years, which has also contributed to raising the banks’ current account savings accounts (CASA) significantly.

    Reports showed some banks last year raised CASA to 28-30 per cent in the total structure of deposits. The large proportion of low-interest rate deposits has helped banks reduce mobilisation and operating costs, increasing profits and improving marginal interest in lending.

  • Lack of clarity will stump 5G growth

    Lack of clarity will stump 5G growth

    As the first commercial deployments of 5G start to appear, the stage is set for consumers finally to find out what the powerful next-generation mobile standard promises can bring: an ambitious and far-reaching technological advance that transforms virtually all aspects of human activity—how we experience life, conduct business, create goods, and build societies.

    That’s the theory and the hope.

    For many in the industry 5G will set the stage for incredible change. However with standards are still being rolled out, it remains a confusing landscape, with varied and sometimes conflicting interpretations of what 5G is and what to expect from it.

    This confusion is impacting not just consumers but also complicating the industry’s ability to measure itself against a standard set of 5G expectations and requirements.

    To optimize short-term and long-term 5G adoption, it is imperative that clarity regarding what 5G is and when each capability will be available is established for both consumers and the ecosystem. To that end, IHS Markit follows the official 3GPP definition of 5G but also believes that this description needs to be understood within the context of everyday experience and concepts.

    According to the IHS Markit whitepaper, The promise and potential of 5G, 5G will improve existing services and enable new use cases, such as driverless cars, immersive entertainment, zero-delay virtual reality, uninterrupted video and no-latency gaming. On the industrial front, 5G will be key to expanding and realizing the full promise of the internet of things (IoT), with the technology’s impact to be felt in smart homes, smart cities and smart industries.

    “The marketplace implicitly understands 5G represents an unprecedented growth opportunity, with the initial smartphone rollout set to generate record shipment volumes,” said Francis Sideco, vice president at IHS Markit. “However, fewer people understand the iterative nature of major technology rollouts such as the one we are going through now with 5G—a process involving multiple major updates that will add new capabilities in the coming years. With each of these updates having the potential to significantly disrupt the market’s competitive dynamics, it’s critical for companies to clearly understand the implications of each rollout or risk falling behind the competition.”

    New 5G technical standards will eventually enable the creation of applications that could open new opportunities, inform new business models and transform everyday life for multiple industries and billions of users throughout the world.

    However, many of these capabilities won’t be available in initial 5G rollouts, but instead will arrive in subsequent releases of the standard to be implemented over the next few years. Each of the releases will deliver new challenges and opportunities not only for the wireless industry but also every industry for which the new use cases are envisioned. To fully realize the potential of these opportunities, competitors will need to understand and capitalize on new capabilities even before they are fully introduced.

    The 5G standard’s next release is already on the horizon, with the expected introduction of Release 16 in late 2019. The upcoming release will deliver highly desirable enhancements, including far greater reliability and peak data rates of 20 Gbps downlink and 10 Gbps uplink.

    “This next phase of implementation and rollout will trigger a race among mobile network operators to meet and take advantage of these performance enhancements. The winners of this race are likely to gain a competitive advantage as they gear up for the next wave of growth,” Sideco said.

    Future revisions will spur similar competitive battles, as 5G adds major new capabilities and expands into other markets beyond mobile communications, such as mission-critical applications and massive internet of things (IoT) deployments.

    “For companies throughout the technology supply chain—from network operators, to smartphone brands, to industrial and automotive device manufacturers and electronics suppliers—it will become increasingly important to understand the changes brought by each phase of the 5G deployment and to be ready to capitalize on the latest capabilities to gain a competitive advantage,” concludes Sideco.

  • LVMH global revenue rises 16%

    LVMH global revenue rises 16%

    LVMH global revenue rose 16 per cent in the first quarter of this year, with Asia and every other geographical market fuelling growth.

    Organic growth – excluding acquisitions – was 11 per cent higher than the same period last year.

    The fashion-and-leather-goods business saw organic sales rise 15 per cent.

    “Louis Vuitton continued its remarkable growth across all of its businesses. Its performance was exceptional, its creativity ever more striking and innovative, and its men’s and women’s Autumn-Winter fashion shows were universally acclaimed,” the company said in a statement.

    “The transformational upgrade of its distribution network continued with highly successful and iconic re-openings, including Florence, London’s Sloane Street, Monaco and Shanghai IFC. Christian Dior Couture performed exceptionally well across all its product categories and regions. At Celine, the new Men’s and Women’s ready-to-wear collections arrived in stores as the new concept starts to be rolled out. Fendi, Loewe and Berluti are growing fast. Loro Piana’s vicuna and shoe collections performed well. The other Maisons continued to progress.”

    In selective retailing, organic revenue rose 8 per cent, with Sephora recording strong revenue growth and market share gains during the period.

    Online sales grew strongly and DFS grew “at a steady pace”.

    “The Gallerias of Hong Kong and Macao performed particularly well,” the company reported.

    Wine and spirits business sales rose a more modest 9 per cent in the quarter, however Hennessy cognac volumes increased by 11 per cent, driven largely by China and the US.

    In perfumes and cosmetics, organic revenue increased by 9 per cent in the quarter.

    Parfums Christian Dior had a standout quarter, helped by the launch of its new fragrance Joy.

    Louis Vuitton global revenue from watches and jewellery grew the slowest, at just 4 per cent, with watches lagging.

  • Indian startup WoodenStreet thrives with O2 Growth Hacking

    Indian startup WoodenStreet thrives with O2 Growth Hacking

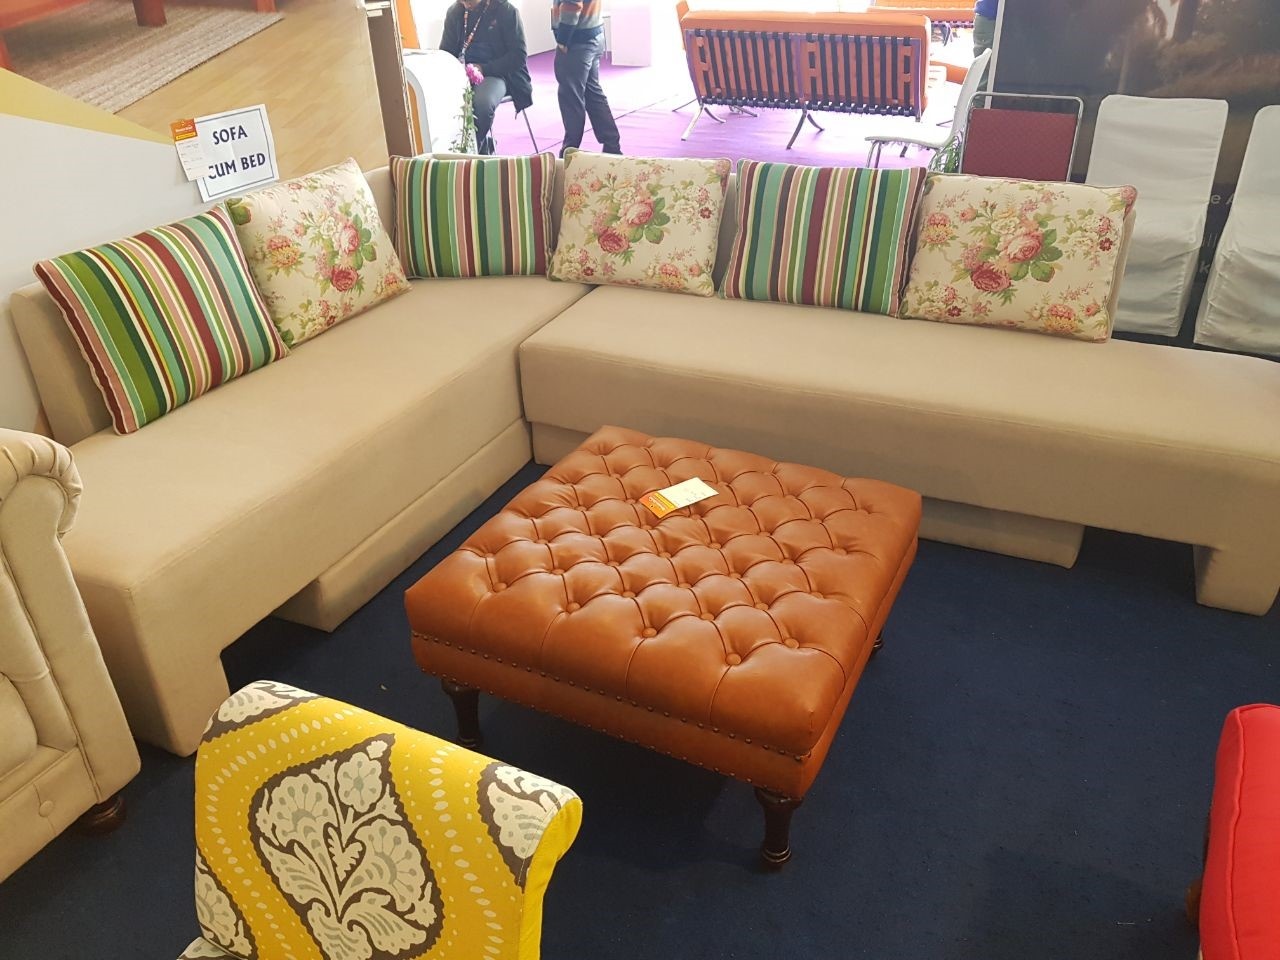
    Indian furniture startup WoodenStreet is targeting 15 additional experience stores in the territory by the end of the year.

    The firm, which specialises in customisable furnishings, currently operates 12 locations throughout India as well as more than 30 delivery hubs.

    “Our country is a diverse nation,” said the firm’s CEO Lokendra Ranawat, “which means that no two homes are the same. Our design tastes are influenced by our upbringing and our culture, so why should we be forced to buy furniture that does not match them? We want people to be free from such constraints.

  • ShopBack Secures Fresh New Funding

    ShopBack Secures Fresh New Funding

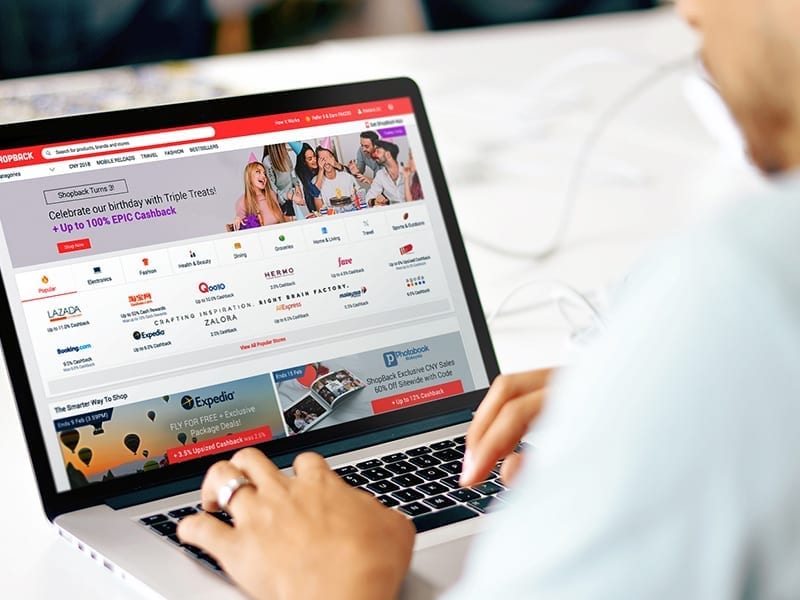
    Rewards program ShopBack has secured a further US$45 million in its latest funding round.

    Joining the shareholders’ register are newcomers including Japanese e-commerce giant Rakuten, EV Growth, and EDBI, a Singapore government-linked strategic investor.

    Amit Patel, CEO of Rakuten subsidiary Ebates and Willson Cuaca, managing partner at EV Growth, will join ShopBack’s board of directors. The new funding round takes the total investment in Shopback to $83 million.

    ShopBack has recently been expanding its core services beyond its original cashback service for online shoppers. Among them, Shopback Go, in partnership with Visa and Mastercard, which enables users to dine out and earn rewards.

    Last year, ShopBack experienced 250 per cent year-on-year growth in both orders and sales. The company powered more than 2.5 million monthly transactions for more than 7 million users in seven Asia-Pacific markets, and delivering close to $1 billion sales for more than 2000 merchant partners, both online and offline.

    ShopBack also entered Australia last year, its first market outside Asia, and opened research and development hubs in Vietnam and Taiwan.

    The company says the fresh funding will be invested in “simplifying shopping experiences, expanding data capabilities to fuel personalisation and business insights, as well as accelerating growth in key markets”.

  • Strong potential’ for sharing economy in China

    Strong potential’ for sharing economy in China

    New research suggests strong potential for the sharing economy in China, with just 30 per cent of consumers there saying they only want to use brand-new products.

    Mintel says the figures highlight the significant market for selling second-hand products and targeting consumers who will rent out rather than buy.

    Mintel says 91 per cent of Chinese consumers said they have rented or bought second-hand bicycles/electric bicycles in the past year. This was followed by cars (61 per cent), books/audio-visual products (25 per cent), digital products such as mobile phones and cameras (25 per cent), furniture (18 per cent) and home appliances such as fridges (12 per cent). While the clothes and accessories sharing category has been making headlines, just 9 per cent of urban Chinese consumers have rented or bought them second-hand.

    “The current consumer landscape in China shows great potential for the sharing economy to develop further,” said Mintel China associate research analyst Scarlett Zhao. “Largely driven by substantial promotions and subsidies, high penetration in rental and second-hand businesses is more focused on the transportation industry; including cars and bicycles. But while the sharing economy in China is dominated by transportation, we see this trend slowly extending to knowledge sharing through books or audio-visual products.

    “At the moment, consumers are not as open to other product categories in the sharing economy space such as clothes and accessories, probably because consumers have not yet cultivated the habit to rent or buy second-hand products. China’s sharing economy still stands in an emerging to growth stage, where market rules and regulations need to be further improved. As a result, this has caused many to remain on the sidelines just like when e-commerce was first introduced.”

    Mintel research reveals that the majority of consumers in China acknowledge the benefits of the sharing economy, with as many as 86 per cent of them appreciating the convenience that sharing products and services bring. Meanwhile, 59 per cent of Chinese consumers cite affordability as a reason to participate in the sharing economy, making it the greatest motivation for them to choose renting or buying second-hand products.

    Environmental factors are also proving important to consumers. Fifty-one per cent of urban Chinese consumers say that they will rent or buy second-hand products as it is good for the environment.

    “Under the healthy wave, consumers today not only look inward to their body health, but are also paying more attention to the whole ecosystem they are interacting with,” added Zhao. “When communicating with and marketing to consumers, companies in the sharing economy space can make consumers feel good about themselves by emphasising how this concept can help reduce the carbon footprint – benefiting the public and the environment.”

  • Nike sees steap growth numbers in Asia

    Nike sees steap growth numbers in Asia

    Sportswear retailer Nike has grown net income to US$1.1 billion over its third quarter, with the group’s consumer-direct  approach delivering growth across all four of its geographic regions.

    Revenues increased 7 per cent to $9.6 billion, up 11 per cent. The Nike brand contributed $9.1 billion of this, while footwear brand Converse brought $463 million – down 2 per cent compared to the prior corresponding period.

    “In Q3, our team once again drove strong, healthy growth across Nike’s complete portfolio,” Nike chairman, president and CEO Mark Parker said.

    “Our business momentum is being accelerated by our ability to scale innovation at a faster pace and expand new digital consumer experiences around the world.”

    In Asia-Pacific, the group saw footwear sales increase 3 per cent to $909 million, while apparel sales grew 6 per cent to $340 million.

    However, sales in the equipment category fell 8 per cent over the period, to $58 million.

    Greater China, saw equipment sales stay flat at $29 million, but experienced a strong 21 per cent growth in apparel sales to $444 million, and footwear sales 19 per cent above the prior period at $1.11 billion.

    The group’s gross margin increased over the period to 45.1 per cent, driven by higher selling prices, favourable changes in foreign currency exchange rates and growth in Nike Direct.

    Additionally, the group’s effective tax rate was 14.7 per cent, compared to 179.5 per cent during the same period last year, which included one-time charges related to the enactment of the US Tax Cuts and Jobs Act, which drove a $921 million loss.

  • Global legal cannabis market growth stable

    Global legal cannabis market growth stable

    The volume of the legal cannabis market is expected to soar nearly 14-fold within six years according to research by Euromonitor International. Legal cannabis sales reached US$12 billion globally last year with exponential growth ahead, will reach $166 billion by 2025, based on Euromonitor’s projections.

    The global cannabis market, both legal and illicit, stands at $150 billion today, according to the firm’s new white paper. By 2025, legal cannabis will represent 77 per cent of the global market.

    “Within 10 years, cannabis will be a regular part of daily routines,” said Zora Milenkovic, head of drinks and tobacco at Euromonitor International. “From a functional ingredient to an intoxicating buzz, cannabis will reshape fast-moving consumer goods, with food, beverages, beauty, health and tobacco having the most potential for disruption.”

    The greatest potential for cannabis is to capitalise on health and wellness trends that are shifting consumption habits and consumer preferences across industries.

    The growth of low- and non-alcoholic beverage consumption and the shift from cigarettes to vaping provide an opportunity for cannabis to replace alcohol and tobacco in social occasions.

    From 2018 to 2025, legal cannabis is estimated to grow more than 2000 per cent globally, compared to alcoholic drinks at 1.4 per cent and tobacco at 1.2 per cent, according to the report.

    In consumer health, Euromonitor expects vitamins and dietary supplements to be the largest cannabis-related category by 2025, with 2 per cent of sales to come from products containing THC or cannabidiol, better known as CBD. It projects global sales of packaged food with CBD to double over the next two years, further blurring the lines between consumer health and food.

    Last week a US analyst singled out Starbucks as one of the first major companies globally to adopt CBD ingredients in consumer products, however the Seattle-based company denied it had any plans to develop such beverages at this time.

  • Retail slow in January despite Luxury growth

    Retail slow in January despite Luxury growth

    While several retailers have talked about conditions improving since a somewhat dismal holiday trading period, the Australian Bureau of Statistics have released a more muted view of month of January, with retail sales having improved by 0.1 per cent.

    This increase followed a fall of 0.4 per cent over December 2018, and a 0.5 per cent increase in November off the back of successful Black Friday and Cyber Monday sales events.

    “While January hasn’t proved to be a ground-breaking month by any stretch, on the plus side it does indicate that retail is slowly picking itself up and heading in the right direction,” National Retail Association chief executive Dominique Lamb said.

    Department store spending saw a 2.1 per cent decline over the month, while spending on clothing, footwear and personal accessories dipped 0.3 per cent.

    Food retailing and cafes, restaurants and takeaway services saw spending 0.3 per cent higher than the month prior, while ‘other retailing’, which brings together several industries such as pharmaceuticals, books and recreational goods, saw a jump of 0.7 per cent.

    The increase in cafe spending could be indicative of consumers beginning to feel more comfortable spending on ‘little luxuries’, according to Australian Retailers Association executive director Russell Zimmerman.

    “We hope this trend will continue to increase and spill into other retail categories across the retail sector,” Zimmerman said.

    The NRA’s Lamb went on to point to the upcoming Federal Budget, stating the importance that the Government puts a focus on encouraging consumer spending.

    “Measures such as tax cuts, infrastructure spending and initiatives that ease the burden on small businesses can all help improve the economy and assist retail in getting out of this sluggish phase it’s experiencing,” Lamb said.

  • Malaysia’s economy expands 4.7% in Q4 2018

    Malaysia’s economy expands 4.7% in Q4 2018

    The Malaysian economy grew at a faster pace of 4.7% in the fourth quarter (Q4) of 2018 driven by private sector activity. This compares with a 4.4% growth in Q3 2018. For 2018 as a whole, the local economy also expanded 4.7%. According to Bank Negara Malaysia (BNM), a rebound in exports of goods and services contributed towards the positive growth of net exports.

    Headline inflation declined to 0.3% from 0.5% in Q3, mainly due to transport inflation turning negative.

    The zerorisation of the Goods and Services Tax and the implementation of the Sales and Services Tax continued to exert an overall downward impact to headline inflation during the quarter.

    BNM governor Datuk Nor Shamsiah Mohd Yunus said the Malaysian economy is expected to remain on a steady growth path with private sector demand being the main driver of growth.

    She said headline inflation is expected to average moderately higher.

  • Indonesian retail sales experiences rapid growth

    Indonesian retail sales experiences rapid growth

    Indonesian retail sales posted solid growth in December, according to a central bank survey. According to the data release, December sales grew at 7.7 per cent throughout the territory, a significantly faster rate than shown in figures from the year previous, are more than double November’s growth rate of 3.4 per cent.

    Sales throughout the month were predominantly underpinned by purchases of food, beverages and tobacco, alongside cultural and recreational goods.

    The survey predicts Indonesian retail sales will grow at a year-on-year rate of 4.8 per cent in January.

  • Asia-Pacific boosts Estee Lauder revenue

    Asia-Pacific boosts Estee Lauder revenue

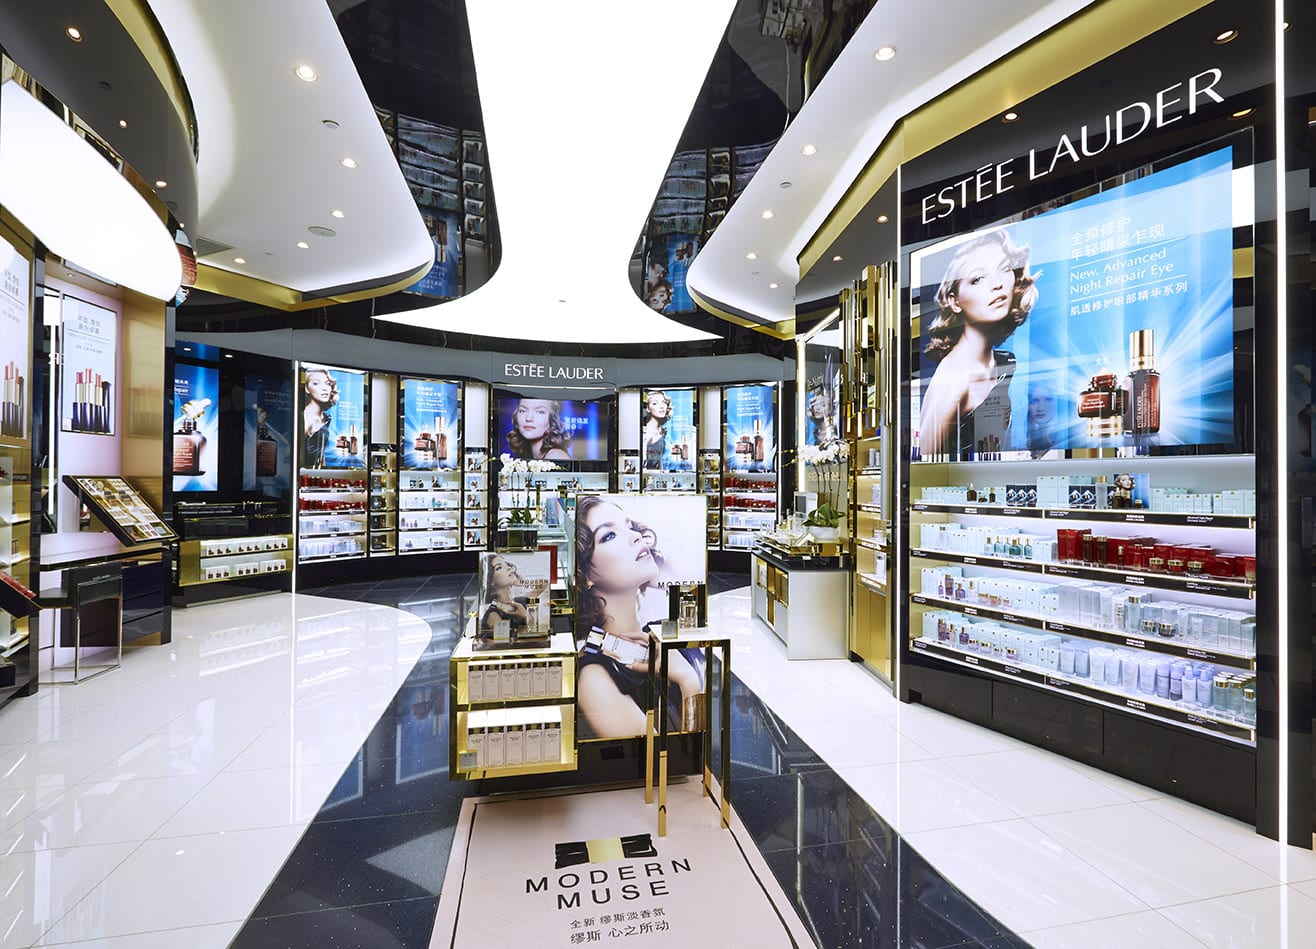
    Estee Lauder Asia-Pacific sales achieved double-digit growth in the December quarter. The beauty giant says the growth was broadbased, with nearly half of the markets in the region growing by double digits. “China, Hong Kong and Japan continued to deliver strong growth, and Korea net sales accelerated. Prestige beauty in China accelerated and the company continued to build share,” the company said in a statement.

    “[We] generated double-digit net sales growth in virtually every major product category and channel. Operating income increased, primarily due to higher net sales.”

    Globally, Estee Lauder sales exceeded US$4 billion for the first time, up 7 per cent from the same time a year earlier. Net earnings rose to $573 million compared with $123 million last year.

    “We delivered an excellent performance in our fiscal second quarter,” said president and CEO Fabrizio Freda. “Importantly, this was our eighth consecutive quarter of impressive net sales growth that met or exceeded our long-term goal, all while navigating many global macro issues.

    “Our sustained progress is the result of our multiple engines of growth strategy, and demonstrates our agility in moving resources to the best global opportunities,” he said.

    The strongest growth engines during the quarter included the skin care category globally, the Estee Lauder Asia-Pacific business, online and travel retail channels, and most brands, including Estee Lauder, La Mer, Mac and the company’s artisanal fragrance brands.

    “Despite a volatile and challenging backdrop, we are optimistic about our company’s long-term outlook. We are very well-positioned to build share in global prestige beauty,” Freda said.

    “We plan to increase our investments during the next six months behind our successful innovations, high-quality products, compelling digital advertising and effective commercial execution, while also enhancing our capabilities to strengthen our industry leadership and deliver long-term profitable growth.”

  • Indonesia’s E-commerce Market Larger Than Estimated; Consumer Habits Changing

    Indonesia’s E-commerce Market Larger Than Estimated; Consumer Habits Changing

    E-commerce accounted for 8 percent of total retail sales in Indonesia last year, on course to reach 18 percent by 2023, fueled by changing behavior among tech-savvy customers who are willing to spend more for convenience, according to a recent study by American multinational investment bank Morgan Stanley.

    The study estimates the size of Indonesia’s e-commerce market at $13 billion in 2018, having grown by 50 percent annually over the past two years. It suggests that the e-commerce market in Southeast Asia’s biggest economy may follow a similar growth trajectory to that of China and expand by at least 32 percent annually over the next five years to $52 billion in 2023.

    “This is notably above our previous estimate of $7.3 billion, or 4.4 percent of sales, partially due to better data availability but also due to the rapid growth in the user base… Indonesia is now only five years behind China in terms of penetration,” Morgan Stanley wrote.

    A separate study by global tech giant Google and Singapore’s Temasek, published last December, put the size of Indonesia’s e-commerce market at $12.2 billion in 2018 and $53 billion in 2025.

    The Morgan Stanley study, based on interviews with 1,582 respondents in eight Indonesian cities, suggests that the growth trend is still in an early stage, with many indicating that they only started shopping online in the past year.

    “Interestingly, 65 percent of the respondents in our survey had only started shopping online within the past year, and the majority believed e-commerce would become their main method of shopping over time,” the investment bank wrote in the report published on Tuesday.

    “There are 195 million smartphone users in Indonesia and only about 30 million online shoppers. The growth potential of the user base is still clearly huge,” it wrote.

    Apart from smartphone penetration, low data costs and the growing number of people with bank accounts serve as crucial enablers for continuing e-commerce growth, Morgan Stanley said. Data costs about 50 US cents per gigabyte in Indonesia, compared with $2.1 per gigabyte in China. About 49 percent of the adult population in Indonesia now has a bank account, compared with 20 percent in 2011.

    Apparel 

    Clothing and footwear fuel the sales growth, with 93 percent of respondents indicating that they bought items in this category online in the past 12 months. Half of them buy apparel at least once a month, Morgan Stanley said. In comparison, only 16 percent and 25 percent, reported that they purchased consumer electronics and mobile devices, respectively, which is the most common category in early state e-commerce.

    The study also noted changing customer behavior, which would likely affect their interaction with traditional brick-and-mortar stores. Three in every four customers said they would check for promotions or prices online before buying anything offline, Morgan Stanley reported.

    Seven in every 10 said they would continue shopping online, even if it meant they would have to pay for delivery. Morgan Stanley said this reflects consumers’ “willingness to pay for convenience.”

    “Fast shipping was the primary reason for preferring one website over another,” the bank said.

    Retailers 

    The trend presents challenges to traditional retailers to remain profitable and provides a powerful platform for small brands to challenge established manufacturers.

    “Our analysis reaffirms our medium-term concern for apparel-focused retailers like [Matahari Department Store]. The average transaction size for apparel online, per our survey, is similar to Matahari’s basket size,” Morgan Stanley said.

    “For beauty and personal care companies like Unilever, the combination of e-commerce and digital media is making it easier or cheaper for smaller companies to build brands and offer nationwide distribution,” it wrote.

    Everybody’s Game

    Investment in Indonesian internet companies has steadily risen over the past two years, which saw them attract at least $7.4 billion in capital in 730 deals.

    With all this potential growth, Morgan Stanley has yet to see clear winners in the country’s e-commerce market.

    Four players control most of the formal e-commerce sales: Lazada, Shopee, Tokopedia and Bukalapak, with the top three each controlling between 20 percent and 30 percent of the market. Bukalapak was in the low teens, according to the Morgan Stanley’s estimation.

    Lazada, a pioneer of e-commerce in Southeast Asia, is still the most preferred platform, according to the bank’s survey

    “Lazada had high usage rates across categories and genders. The cash-on-delivery option was one of the key drivers of the preference,” it said.

    Shopee was second overall in terms of usage and preference, being more popular in smaller cities and among people buying baby products, toys, and beauty and personal care products.

    “Tokopedia’s preference and usage were lower beyond Jakarta in our survey. Its usage rate was only 38 percent in second-tier cities like Surabaya, Medan and Bandung, compared to 62 percent in Jakarta,” Morgan Stanley said.

    A surprising find in the survey is that Tokopedia and Bukalapak both enjoy more than 80 percent customer recognition, but less than 50 percent had made purchases on their platforms within the past 12 months.

    “For Southeast Asia, we remain convinced that its e-commerce platform is being undervalued. Our survey not only confirms the popularity of Shopee but also that its users are willing to pay for delivery, which solidifies its path to profitability,” Morgan Stanley said.
  • Ride-Hailing Firms Enjoy Growth in Indonesia, but Face Fraud Challenge

    Ride-Hailing Firms Enjoy Growth in Indonesia, but Face Fraud Challenge

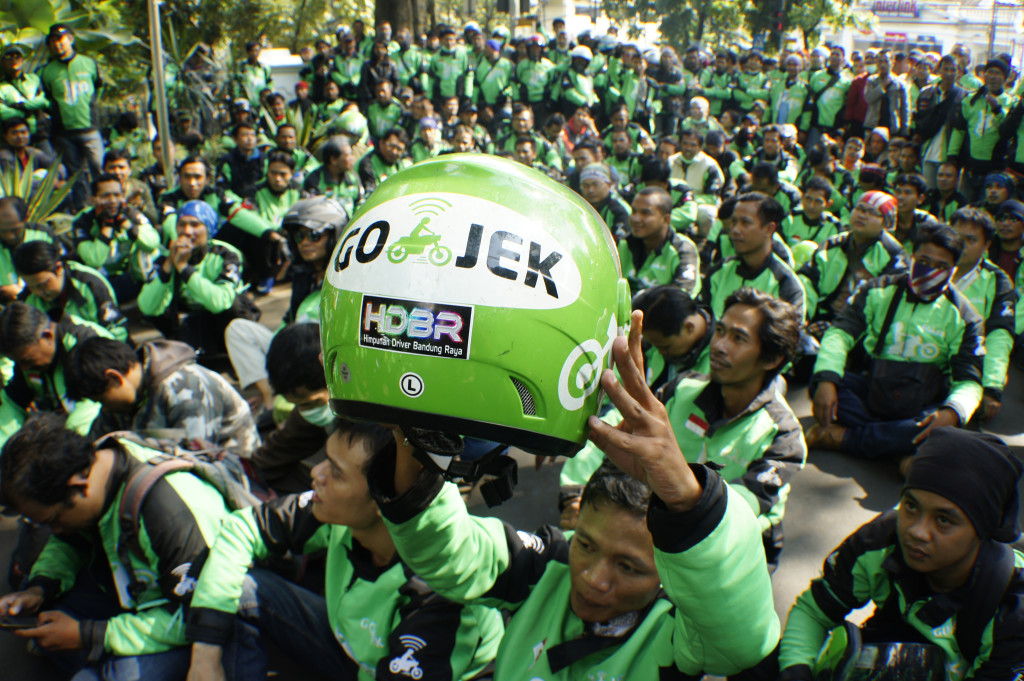
    Grab and Go-Jek, two of Southeast Asia’s biggest technology startups, have successfully grown their food delivery and ride-hailing services, but both must pay special attention to better detection of fraudulent orders, a recent study by Spire Research and Consulting Indonesia showed.

    The local unit of the Tokyo-based research company surveyed driver partners and customers to establish what ride-hailing services they prefer, based on various criteria, including consumer awareness, usage frequency and the use of e-money.

    Grab Leads in Product Usage

    Based on Spire’s consumer awareness survey, 75 percent of respondents said they used Grab’s services over the past six months, while 61 percent indicated that they had done so in the past three months.

    For Go-Jek, it was 62 percent and 58 percent, respectively.

    “Regardless, 50 percent of respondents agree that both Grab and Go-Jek are their favorite brands,” the consultancy said.

    Regarding product usage frequency, customers more often used Grab’s services than those of Go-Jek in the last quarter of 2018.

    The survey also found that 34 percent of GrabCar customers were more likely to use the service three to four times a week on average, while for Go-Car, 25 percent of customers were more likely to use the service once or twice a week on an average.

    Grab Leads in Four-Wheel Segment, Go-Jek Leads in Two-Wheel

    On the other spectrum of the survey, it found that Go-Jek’s Go-Ride was still the customer favorite, with 64 percent saying that they use the service once or twice a day, while for Grab it was 58 percent.

    “When it comes to food delivery, Go-Food is in the lead with 35 percent of respondents saying Go-Food was the brand they most often used, but Grab is catching up quickly with 27 percent saying they used GrabFood the most,” Spire said in a press release on Tuesday.

    E-Money

    As of 2018, both services introduced the use of e-money to facilitate digital payments.

    Grab launched an e-payment service in cooperation with OVO, while Go-Jek established its own, Go-Pay.

    “Based on the survey results, OVO usage exhibits strong O2O [online-to-offline] usage, while Go-Pay’s strength is in Go-Jek’s mobile app ecosystem. For example, OVO is the preferred payment for offline items like phone balance, parking bills and bills for nonfood merchants, while Go-Pay is used to pay food-merchant bills [Go-Food] and electricity bills through the Go-Jek app,” Spire said in the statement.

    Natural Selection

    Indonesia has seen monumental growth in the ride-hailing sector over the past few years, with the mergence of dozens of startup companies. However, natural selection resulted in only two surviving and dominating the market.

    Indonesia is still a magnet for tech companies, including ride-hailing services, thanks to the high consumption rate and mobility of its citizens.

    The two survivors have seen intense competition, with both drastically increasing their product offerings.

    Their services such as food delivery and ride-hailing are similar in nature, but the two companies’ more unique offerings are distinguishing factors.

    Fraud

    Spire said the most interesting finding of its study was the prevalence of fraud.

    “The most interesting finding by Spire is the existence of fraud and how the drivers perceive it,” Jeffrey Bahar, group deputy chief executive of Spire Research and Consulting, said in the statement.

    Spire said fraud in online ride-hailing services is an open secret among drivers and that most who commit it gave similar reasons for doing so, which is to increase their monthly earnings.

    Fraud is seen as a major threat to the industry as it results in economic losses to the companies and highlights vulnerabilities in their systems.

    Spire’s research showed that nearly 30 percent of Go-Jek’s total transportation orders might be fraudulent, compared with 5 percent for Grab.

    “This is based on an estimation of fraudulent orders against total orders. This is a systemic problem for both companies and one that Go-Jek needs to address,” Spire said in the statement.

    According to Spire’s driver survey, “as of 2018, nearly 60 percent of Go-Jek’s drivers say they commit fraud on a daily basis to boost their order numbers, which affect their bonuses and daily income.”

    The drivers who were surveyed said Go-Jek’s system was easier to trick by using applications that modify their location data. On the other hand, less than 10 percent of Grab’s drivers admitted to committing fraud.

    Grab’s drivers said the company’s system was not easy to trick and that the sanctions imposed for such offenses was a deterrent. Drivers also commented that both companies had been improving their systems to better detect fraud.

    “Overall, both companies are growing rapidly in food delivery and ride-hailing but special attention must be paid to the issue of fraud to ensure the healthy development of the technology ecosystem in the country,” Spire said.