Historical context correction (8 November 2026): This article concerns the takeover approach reported on 29 June 2012, not a new approach in 2026. ABC’s report from that date subsequently identified the bidder as EB Private Equity and described an initial A$1.65 billion proposal. ABC’s updated report recorded a 14.6% share-price rise; it does not verify the 12.3% / A$2.54 snapshot retained below. References to a forthcoming offer describe expectations at the time, not a live transaction. The broader commentary about online competition and lease risks is analysis, not a finding established by that ABC report.
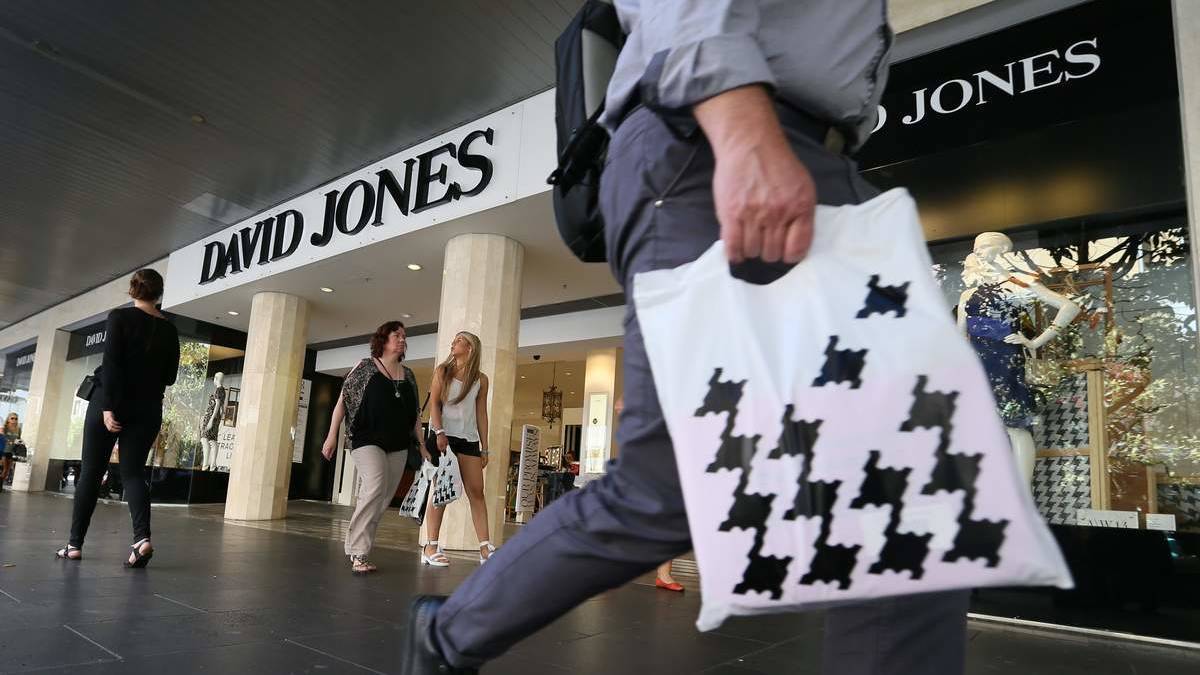
David Jones shares surged 12.3 per cent to Aus$2.54 on 29 June 2012 after the upmarket Australian department store received an unsolicited takeover approach from a mystery British bidder.
Early trading peaked with an intraday gain of more than 17 per cent before easing in the afternoon.
Unsolicited letter from an unincorporated entity
The Australian retailer confirmed receipt of an indicative letter from a non-incorporated UK business seeking to explore a buyout of the company. Board members stated they lack sufficient operational and financial detail to evaluate the proposal at this stage.
The directors do not believe they currently have relevant information to enable them to qualify or value the approach but, should this change, will advise the market accordingly.
Sector-wide rally across department store rivals
Trading desks reacted immediately across the broader Australian discretionary retail sector. Shares in key domestic rival Myer advanced more than four per cent to Aus$1.61 following the announcement.
Investors view the approach as an opportunistic bid to acquire prime retail footprint at discounted valuations. Department store operators across the region face margin compression, elevated leasing costs and intensifying competition from foreign e-commerce platforms.
Balance sheet pressures and online competition
Traditional multi-brand retailers in Australia continue to grapple with sluggish household spending and shifting shopping patterns. Physical department stores carry substantial fixed property overheads while digital pure-plays capture market share in apparel and beauty categories.
For institutional shareholders, an offshore buyout approach tests whether current trading prices reflect underlying asset backing. Commercial landlords face lease renegotiation risks if new ownership chooses to rationalise underperforming store space.
Profit downgrade set the stage for opportunistic bids
The takeover approach follows a difficult operational stretch for the Sydney-based retail group. In March, David Jones warned that full-year profit could drop by up to 40 per cent as stalled consumer demand and accelerating digital sales weighed heavily on store traffic.
At the time, attention focused on whether the approach would develop into a formal offer; this was a 2012 development, not a current transaction.
Leave a Reply