Category: Food

Retail News Asia is committed to providing both local and global retailers with the latest Food and Food & Beverage news throughout the Asian market. This on a daily base.

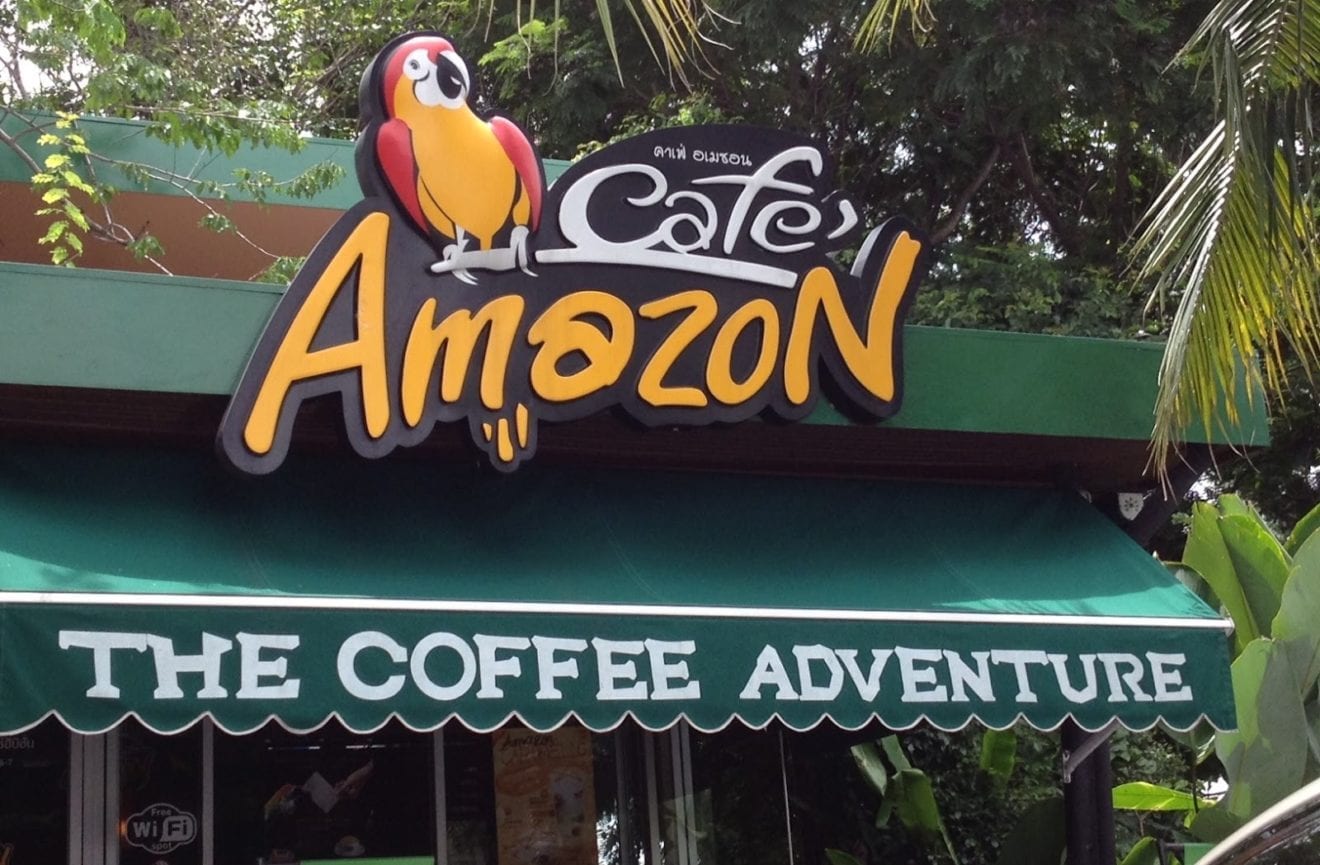
  • Café Amazon Rolls Out Canned Sparkling Coffee Across 7-Eleven Thailand

    Café Amazon Rolls Out Canned Sparkling Coffee Across 7-Eleven Thailand

    Café Amazon has launched Amazon Fizzpresso across 7-Eleven stores in Thailand. The product brings zero-sugar sparkling ready-to-drink coffee to convenience shelves nationwide.

    Two fruit flavours lead the debut: Yuzu and Peach. Both combine carbonated water with instant coffee notes to mimic a coffee soda. Earlier sparkling coffees in Thailand stayed in specialty grocers at premium prices. 7-Eleven’s retail footprint will test whether the drink works as an everyday convenience purchase.

    Formulation and convenience distribution

    The Peach variant contains water, 0.53 per cent concentrated peach juice, and 0.38 per cent coffee powder. Sucralose and acesulfame potassium replace sugar to keep the drink low-calorie. Acidity regulators and standard preservatives round out the shelf-stable formulation.

    Selling through 7-Eleven gives the chain immediate access to thousands of high-traffic locations across Bangkok and provincial hubs. In grab-and-go coolers, the product competes directly against carbonated soft drinks, energy drinks, and traditional canned milk coffees.

    Regional push into fizzy brews

    Sparkling coffee has seen mixed consumer reception across Southeast Asia, though regional chains continue to back the format. Malaysian operator ZUS Coffee introduced its canned Coffizz line in Original and Zesty Lime variants in 2024. Those cans remain on retail shelves despite polarized early feedback.

    Independent roasters and smaller regional players have treated sparkling coffee as a novelty drink. Café Amazon brings the manufacturing scale of parent group PTT Oil and Retail Business. The real test is whether repeat purchases hold up in convenience chillers once initial curiosity fades.
  • Comvita Swings to NZ$7.7 Million Annual Profit on Honey Reset

    Comvita Swings to NZ$7.7 Million Annual Profit on Honey Reset

    New Zealand Manuka honey producer Comvita swung to a net profit after tax of NZ$7.7 million for fiscal 2026, rebounding from a NZ$104.8 million loss a year earlier.

    Operating profit reached NZ$14 million for the twelve months ended June 30, reversing a NZ$29 million operating deficit booked during the previous financial year.

    Margin Recovery and Cost Discipline

    Gross profit climbed 38.8 per cent to NZ$114.8 million across the period. That performance expanded the group gross margin to 53.9 per cent as efficiency measures took hold across manufacturing and inventory handling.

    The return to the black follows an intensive reset programme that targeted operational costs after heavy inventory impairments and market softness damaged earnings in fiscal 2025.

    Asia Demand and Export Execution

    Comvita built its business on premium functional food demand across Greater China, Southeast Asia and North America. Premium specialty honey brands in the region spent the past two years battling cautious consumer spending, cross-border channel resets and distributor destocking across East Asian department stores and cross-border platforms.

    Market attention now turns to export volume trends in Asian retail channels over the first half of fiscal 2027 to verify whether the margin gains hold up in core consumer accounts.

  • It’s Olio Reaches Seven Figures and Targets $2 Million in Online Sales

    It’s Olio Reaches Seven Figures and Targets $2 Million in Online Sales

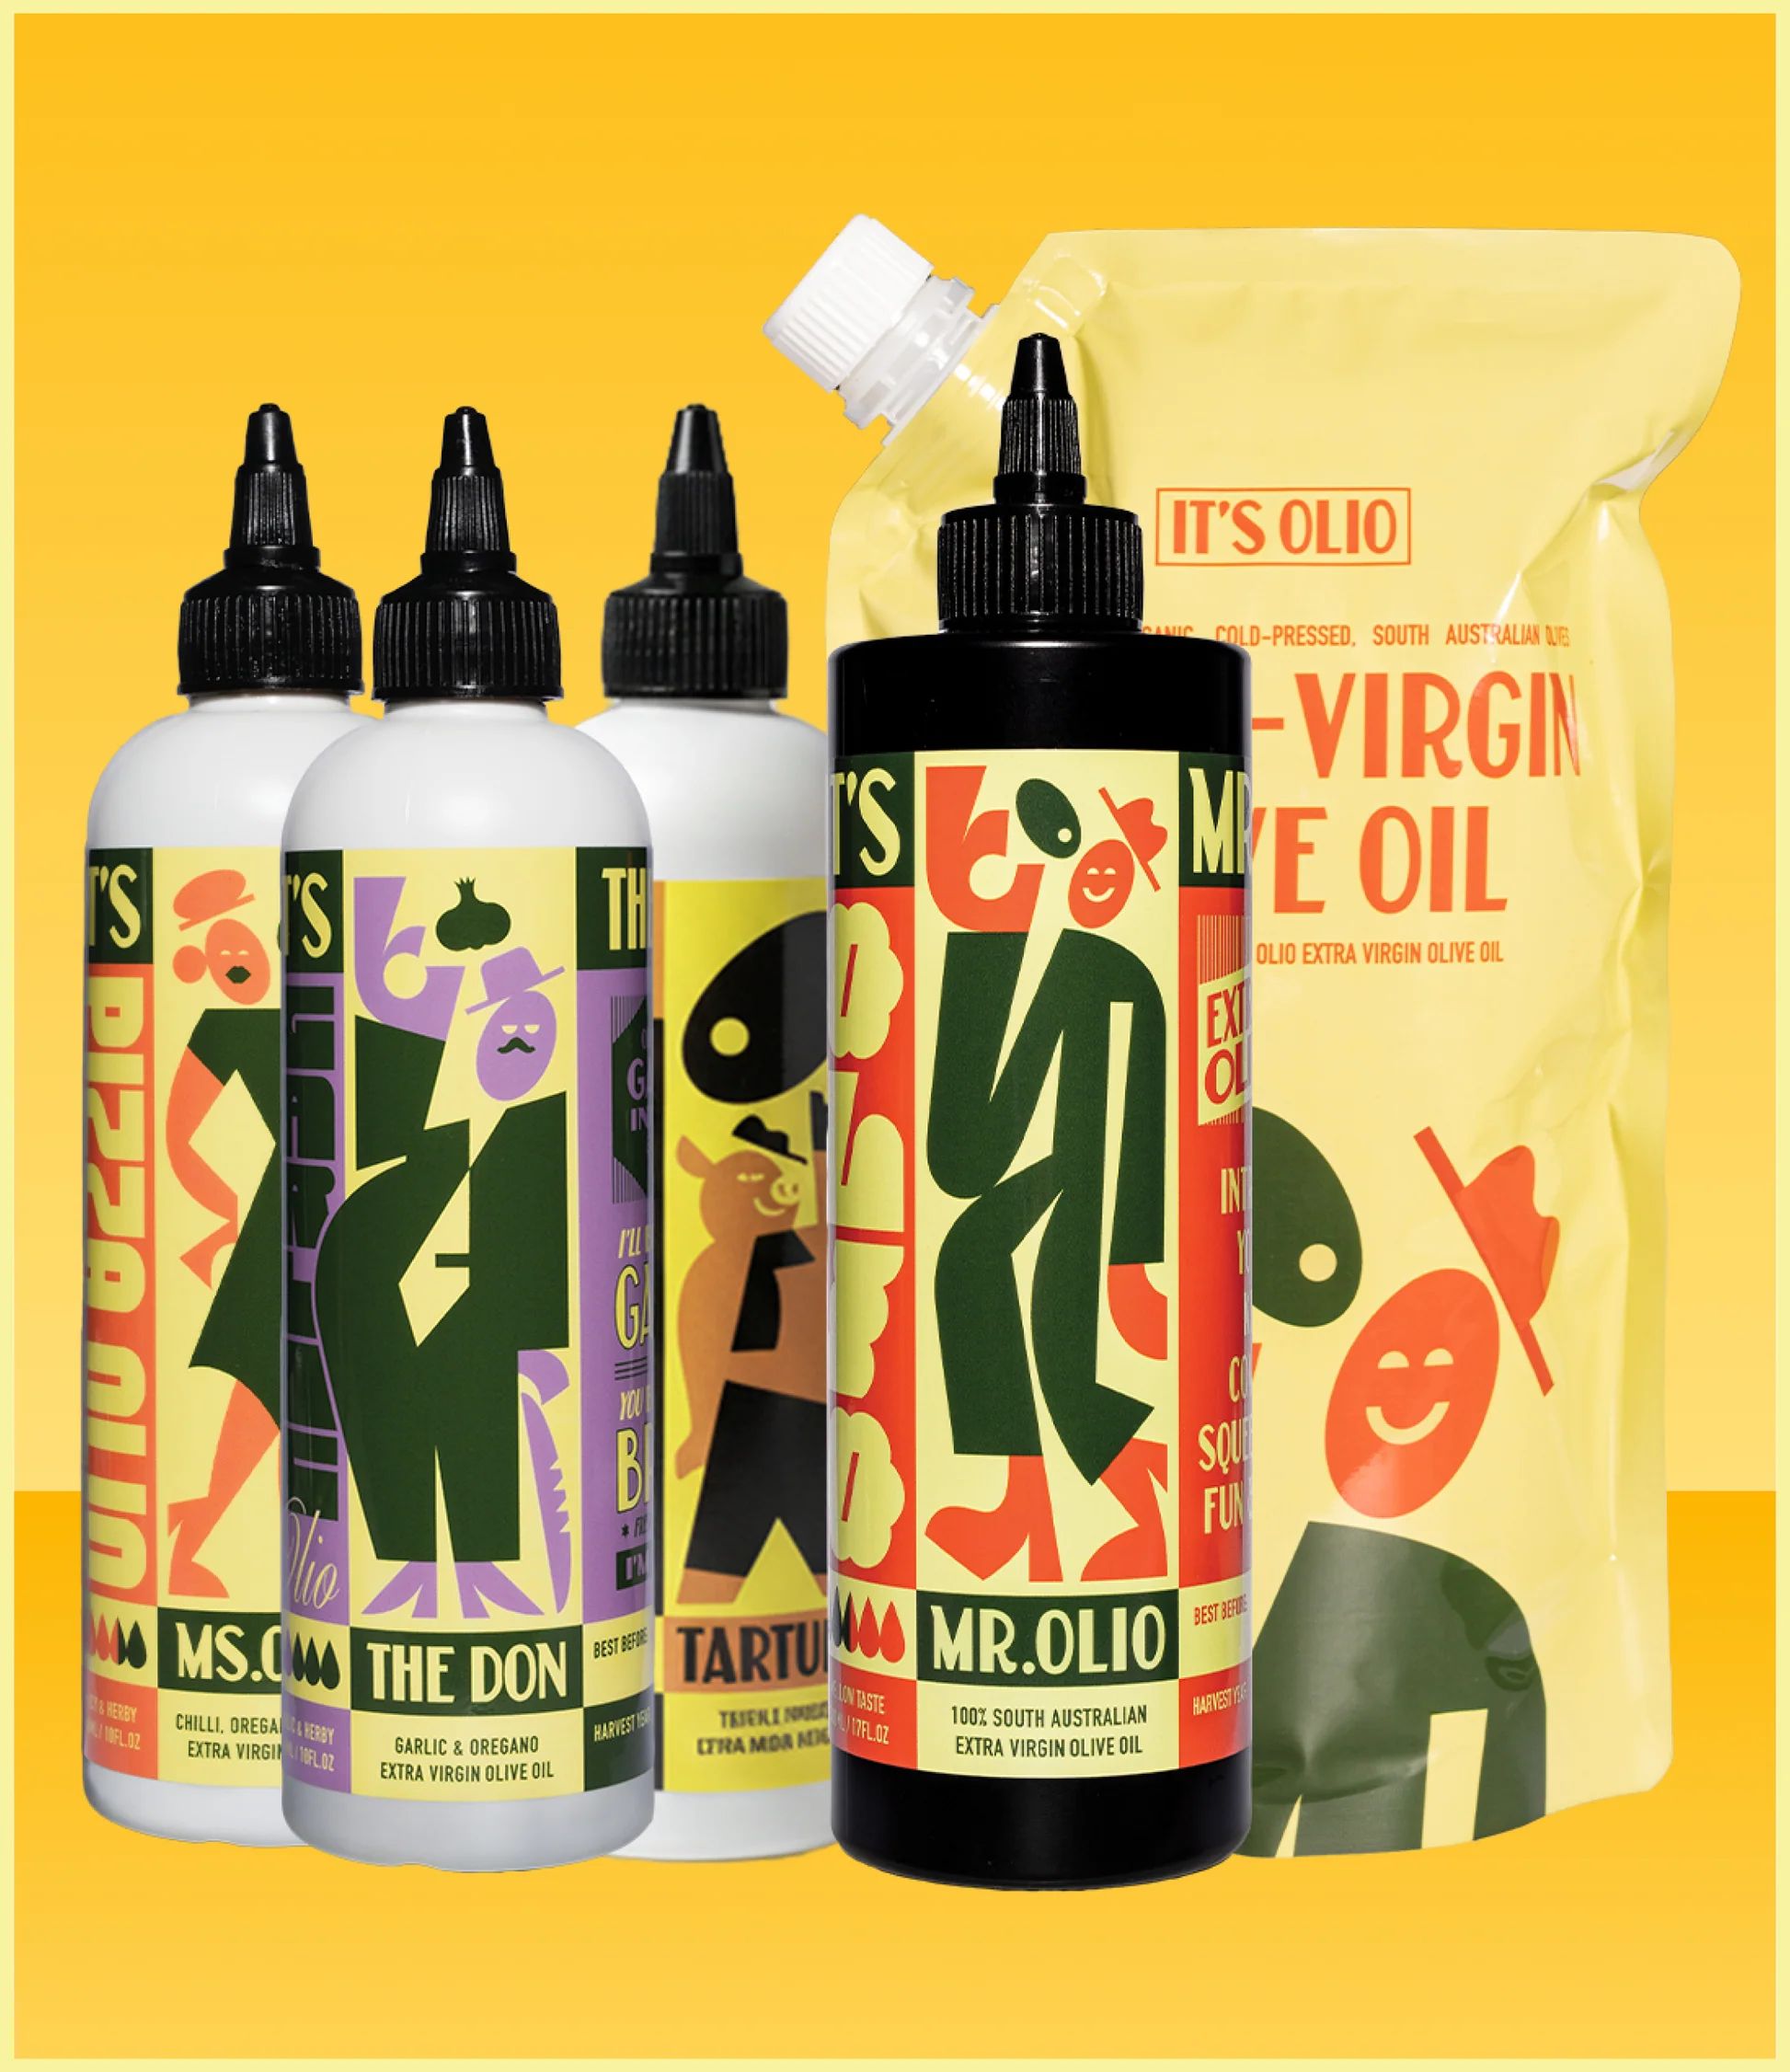
    South Australian olive oil brand It’s Olio has reached seven figures in revenue three years after launching on an initial budget of $10,000. The direct-to-consumer label now targets more than $2 million in online sales before the end of 2026.

    Founder Alec Randall conceived the business after travelling through Sicily in 2022 and attending local cooking classes. He started commercial operations the following year, focusing on premium olive oil marketing and digital direct sales.

    Cross-border digital distribution

    The business built its initial customer base in Australia before adding distribution across New Zealand and the United States. Online sales provide the core revenue engine, allowing the producer to handle fulfilment and marketing across three separate national markets.

    Self-funded pantry startups across the region increasingly bypass traditional supermarket contracts early in their lifecycles. High grocery shelf fees in major retail chains make pure-play e-commerce a leaner route to prove export demand before pursuing physical wholesale distribution.

    Targets for the current financial year

    Direct export logistics remain the main testing ground for boutique Australian food labels selling into North America and Australasia. Controlling fulfilment costs across multiple shipping zones will decide whether the brand maintains gross margins as volume scales.

    The company is now working to convert its offshore digital traffic into recurring subscriptions, with management targeting the $2 million online sales threshold before the close of the calendar year.

  • I’m Donut? Expands into Southeast Asia with Kuala Lumpur Store in September

    I’m Donut? Expands into Southeast Asia with Kuala Lumpur Store in September

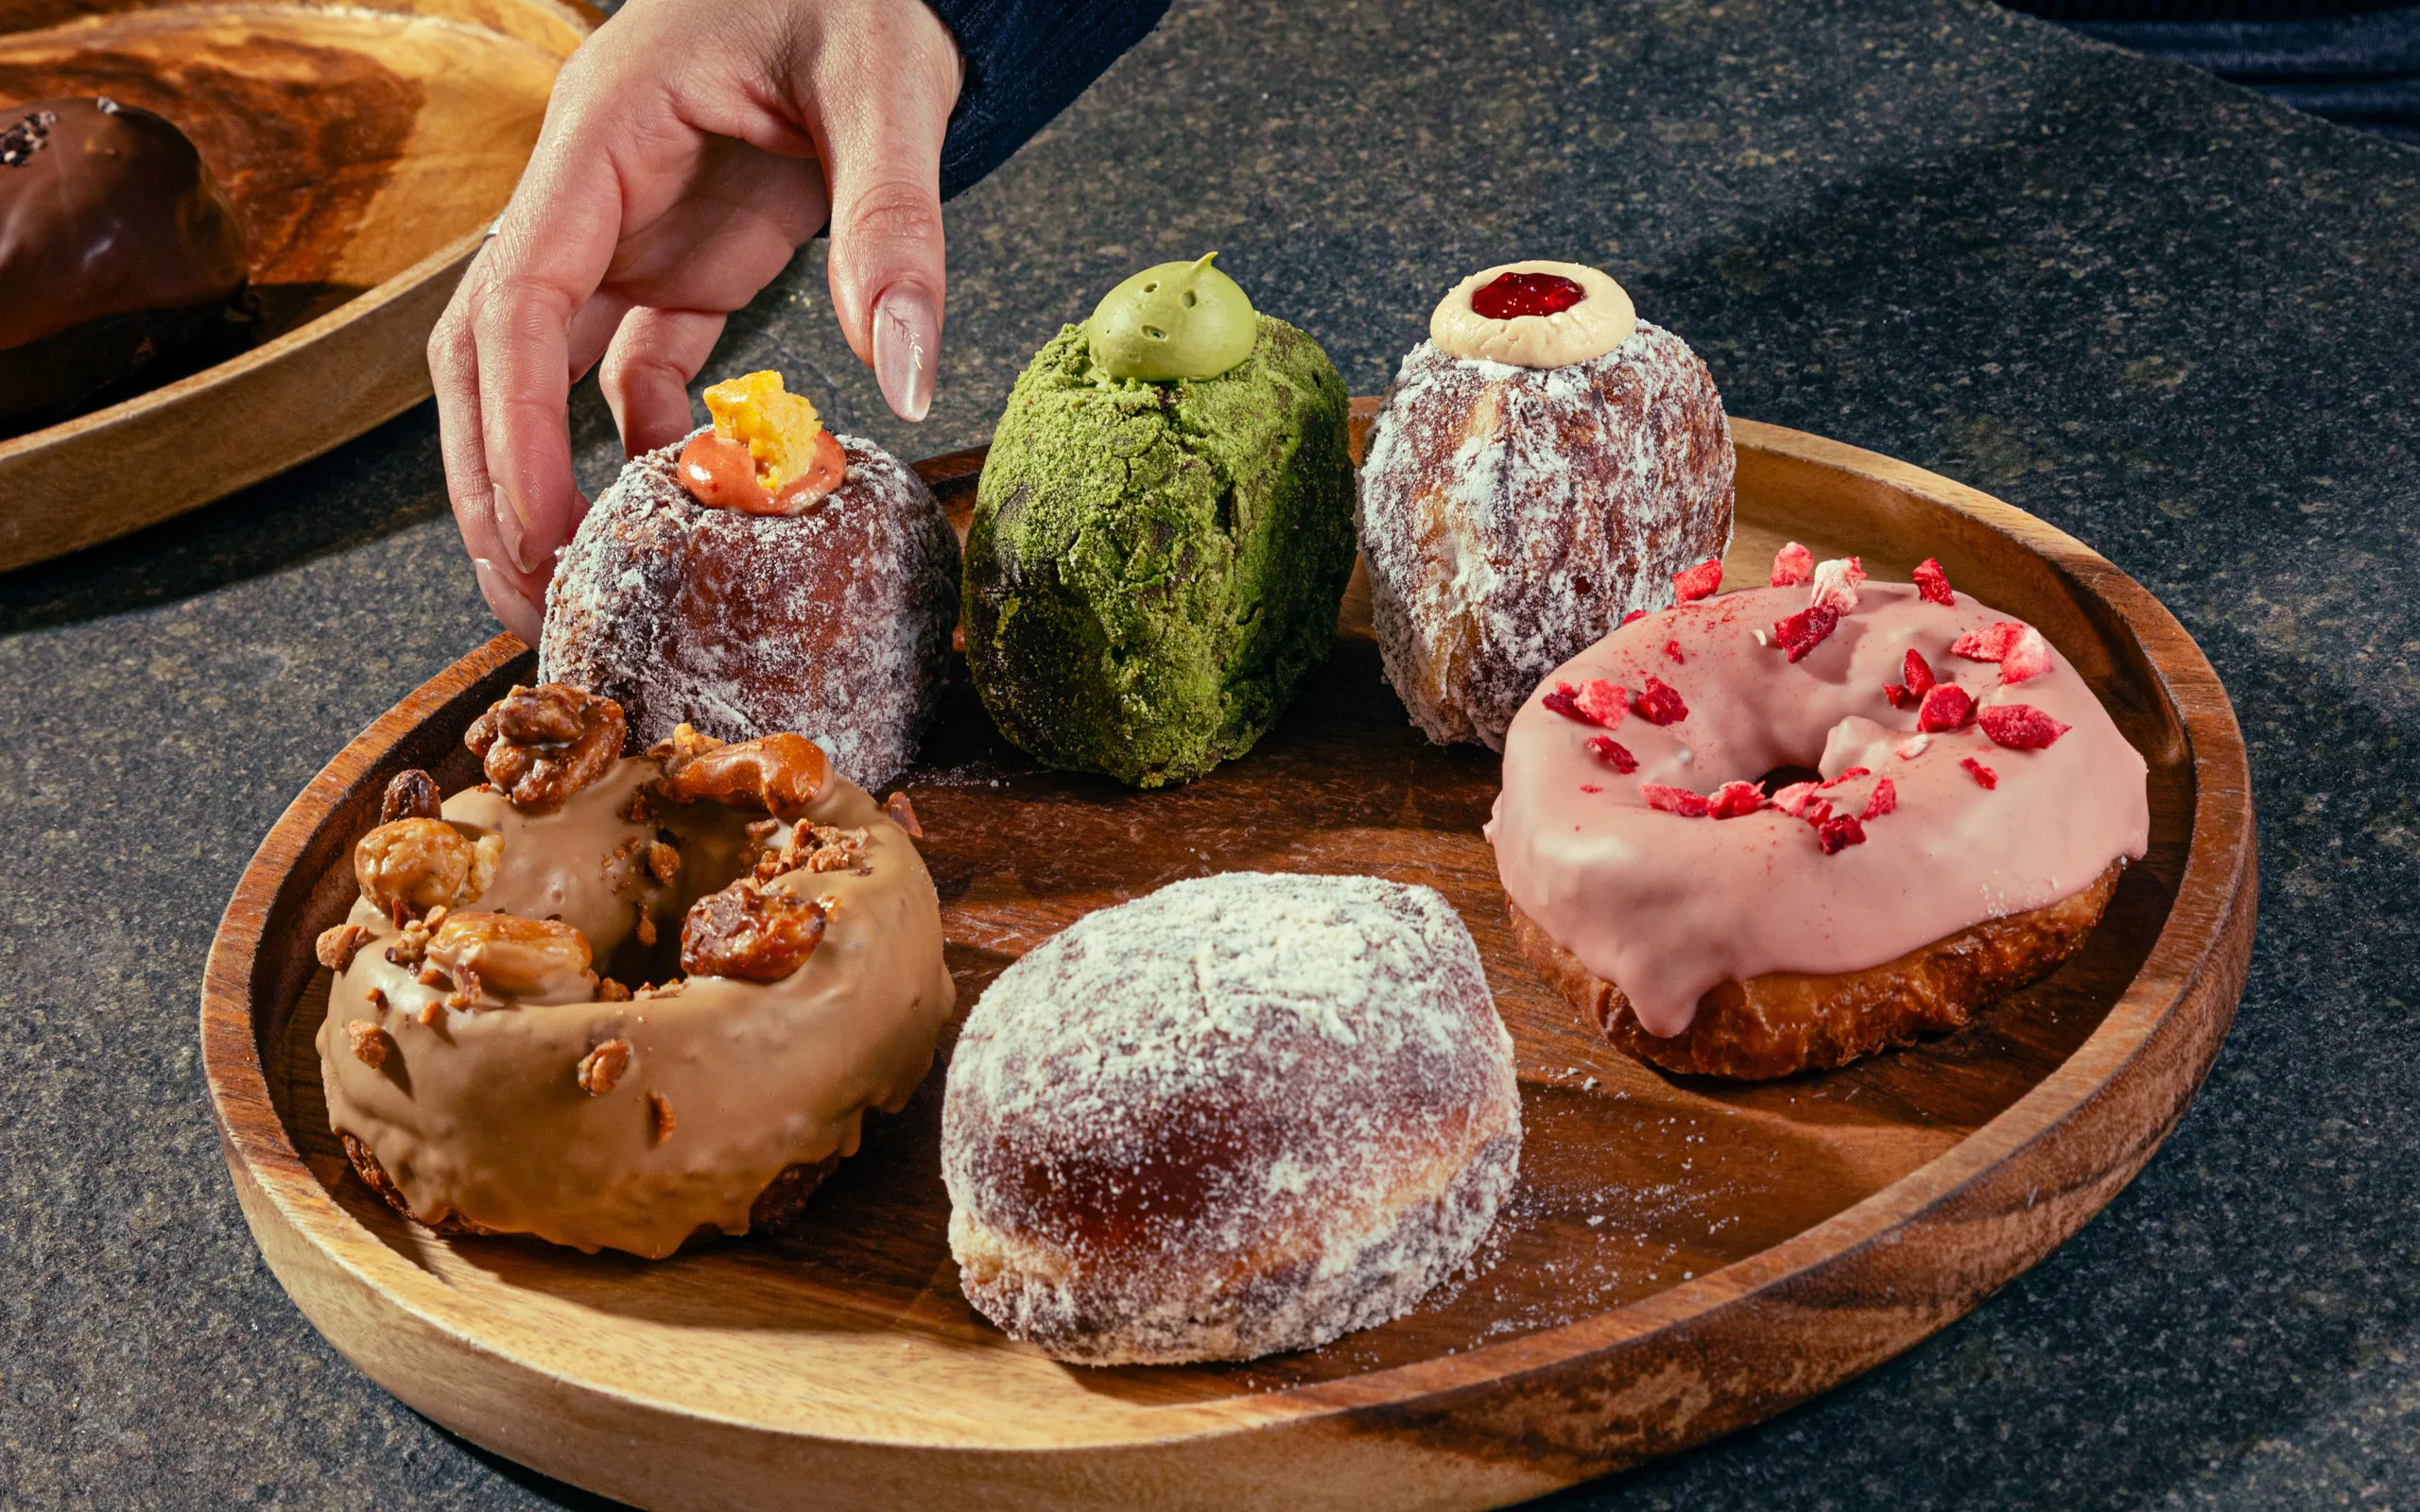
    Japanese bakery brand I’m donut? Will open its first Southeast Asian store in Kuala Lumpur this September. The store brings the company’s signature raw nama donuts to Malaysia for its regional debut.

    The concept built long queues across Tokyo with fried dough that uses pumpkin puree and high hydration to achieve a soft texture. The brand now enters Southeast Asia as international food and beverage operators target urban shopping destinations across the region.

    Expansion beyond Japan

    Malaysia frequently serves as an entry point for Japanese food brands testing regional appetites. Operators rely on high consumer familiarity with Japanese retail concepts and strong mall foot traffic in the Klang Valley to build brand momentum before expanding into neighbouring countries.

    Specialty dessert brands across Southeast Asia have shifted toward focused single-item menus. High-turnover bakery concepts allow operators to keep production footprints compact while driving customer traffic through distinct product formats.

    Competition in premium baked goods

    Artisanal bakery chains and overseas dessert operators are competing directly for prime retail space in major Malaysian retail centres. Premium baked goods have maintained steady foot traffic even as broader consumer discretionary spending faces pressure from food inflation and import costs.

    RetailNews Asia notes that dessert chains expanding internationally must balance localized supply chains with the need to match the taste profiles of their original domestic stores. The company plans to announce the exact retail site and opening schedule in Kuala Lumpur ahead of the September launch.

  • Suntory Oceania Expands Maximus Lineup with Pink Lemonade Sports Drink

    Suntory Oceania Expands Maximus Lineup with Pink Lemonade Sports Drink

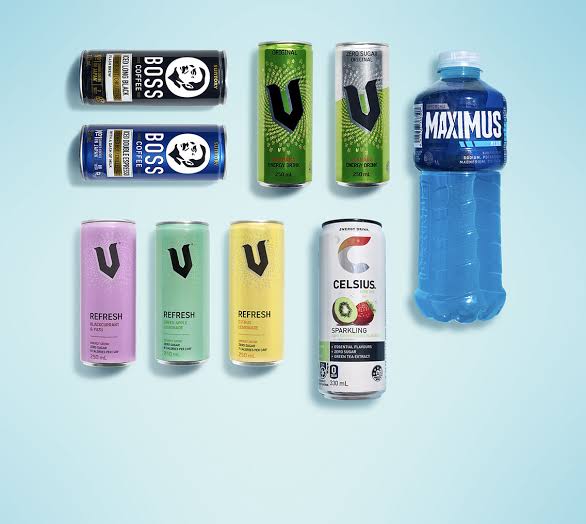
    Suntory Oceania launched a Pink Lemonade variant for its Maximus sports drink brand across Australia. The standard 1-litre bottle carries an RRP of $3.15.

    This addition expands the core beverage lineup. It follows reported incremental volume growth across the regional sports hydration category.

    Category Expansion and Flavor Lineup

    Shipments join existing Maximus varieties on retail shelves, including Blue, Mango Passionfruit, Grape, Red, and Lemonade Ice Block. Retailers are stocking the 1-litre single-serve bottle to capture commuter and athlete demand for high-volume functional drinks.

    Brand teams aimed the release at consumer demand for familiar citrus profiles in hydration. Maximus leans on its value-per-volume pitch against traditional 600ml rivals in convenience stores and supermarkets.

    Oceania Hydration Strategy

    Japanese parent firm Suntory Holdings consolidated its Australia and New Zealand commercial operations to speed up distribution across soft drinks, ready-to-drink options, and functional beverages. Maximus acts as the group’s primary volume driver against global incumbents in the regional isotonic category.

    Across Asia-Pacific, beverage makers face tighter shelf space as retailers cut underperforming SKUs for high-turnover line extensions. Suntory Oceania is pushing mainstream flavor profiles to secure fridge door share in independent petrol and grocery channels.

    Rollouts continue across major Australian retail chains and convenience networks this month. Sales velocity and inventory levels over the spring trading period will determine whether the flavor secures a permanent core ranking.

  • Moondarra Expands Dairy Line with Cranberry Vanilla Cream Cheese at Woolworths

    Moondarra Expands Dairy Line with Cranberry Vanilla Cream Cheese at Woolworths

    Australian dairy brand Moondarra Cheese has rolled out a cranberry and vanilla soft cheese across selected Woolworths supermarkets nationwide, priced at $4.20 for a 120-gram tub.

    The product uses the manufacturer’s triple cream cheese base blended with cranberries and vanilla. Alongside the new SKU, Moondarra refreshed the packaging design across its broader line of marinated cheeses to improve shelf visibility in the specialty deli and dairy aisles.

    Supermarket Dairy Competition

    Sweet and savoury combination cheeses have gained shelf space in Australian grocers as producers target entertaining platters and snacking occasions. Woolworths and rival Coles have both reshuffled their specialty cheese sets over the past two years, replacing slower-moving European imports with local flavoured cheeses that offer higher margins and shorter supply chains.

    For Moondarra, the rollout secures valuable facings in Australia’s largest supermarket network. Supermarket dairy aisles remain tightly contested as private-label options squeeze mid-tier branded producers on everyday staples, pushing commercial cheese makers toward higher-value sweet and marinated segments.

    Distribution and Retail Presence

    The new cheese formulation is now available in selected Woolworths stores across the country. Moondarra will monitor sales performance across the network ahead of the key summer entertaining season.

  • New Zealand Children Food Brand Odi Launches Direct Sales in Australia

    New Zealand Children Food Brand Odi Launches Direct Sales in Australia

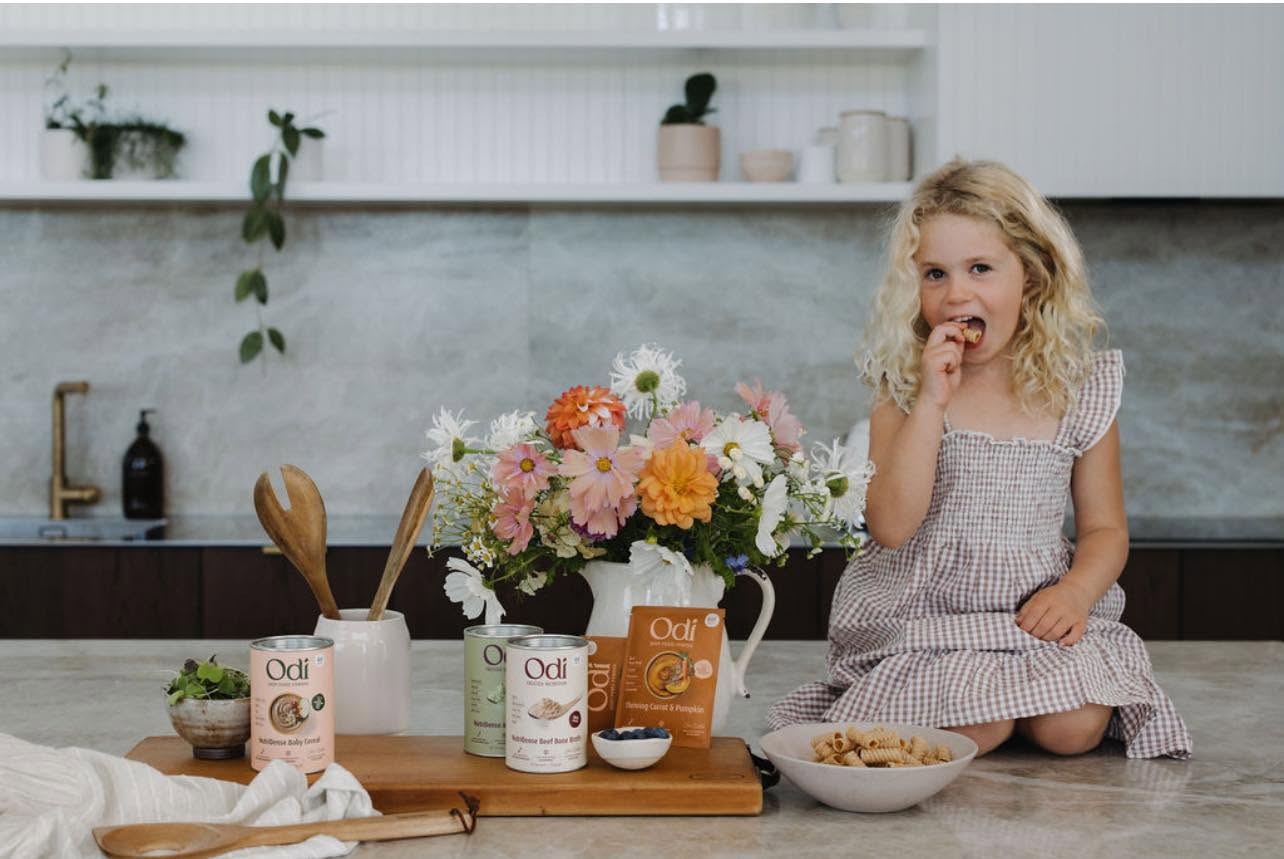
    New Zealand children’s food maker Odi entered Australia on August 28, 2026. The launch brings direct-to-consumer sales in the brand’s first international expansion outside its home market.

    Domestic retail distribution across New Zealand came first. Now, the company is targeting Australian shoppers through an online-first model.

    Direct Sales Before Supermarket Shelves

    Odi sells directly to households through its website during this initial launch. Later, it plans to secure distribution agreements with nationwide Australian grocery and food retailers.

    This export push tests whether New Zealand brand momentum translates across the Tasman without immediate supermarket placement. Direct shipping builds customer demand data first. That gives the brand use before it negotiates wholesale terms with major supermarket chains.

    Scrutiny on Infant Food Formulations

    Regulators in Australia are paying closer attention to packaged children’s food formulations. Government research found commercial infant and toddler products are major sources of dietary sugar. That finding puts pressure on established FMCG manufacturers to reformulate ranges.

    Retail buyers have responded by reviewing children’s food ranges, opening shelf space for newer independent labels. Direct sales offer New Zealand brands a fast entry point while buyers evaluate these category shifts.

    Odi will run direct fulfillment in Australia while it finalizes retail supply partnerships for a planned nationwide physical store rollout.

  • Vodka Reaches Record Share in India as White Spirits Surge

    Vodka Reaches Record Share in India as White Spirits Surge

    Vodka has taken a record share of India’s liquor market as demographic shifts push drinkers toward white spirits.

    Purchases by younger consumers and women are driving the category, altering demand patterns in a sector historically dominated by commercial whisky.

    Shift toward white spirits

    Distillers are adjusting their product mixes to capture changing consumer tastes across retail stores and bars. Radico Khaitan expanded its vodka operations over the past five years to secure stronger positions in urban retail channels. The change pulls volume away from entry-level brown spirits into clear, mixable drinks.

    Premiumisation drives portfolio overhaul

    Spirits makers are overhauling existing product lines to protect operating margins against rising bottling and raw material costs. Radico Khaitan upgraded its whisky portfolio into higher price bands, cutting its exposure to mass-market commodity liquor. Liquor retailers across India are allocating more shelf space to premium white spirits as manufacturers phase out unprofitable lower-tier labels.

    Investors and distributors now await next quarter’s sales filings to assess how volume gains in premium vodka balance margin declines in mass-market spirit lines.

  • Burger King Korea Opens Seoul Flagship Store as It Chases 1.1 Trillion Won in Sales

    Burger King Korea Opens Seoul Flagship Store as It Chases 1.1 Trillion Won in Sales

    Burger King Korea will open its first global flagship store in Seoul on September 10, backing a push to reach 1.1 trillion won in annual sales.

    The quick-service operator is targeting a network of more than 600 locations across South Korea this year, up from its current footprint.

    Located in the eastern district of Seongsu, the new format trades under the name Flameground. Local operator BKR designed the venue around exclusive menu items, branded merchandise and reservation-only dining, shifting away from standard counter-service fast food into experiential dining in one of Seoul’s busiest retail corridors.

    Private equity backing and store targets

    BKR operates both Burger King and Canadian coffee chain Tim Hortons in South Korea. The company entered the country in 1984 with an initial site in Jongno, changed hands to VIG Partners in 2012, and joined Hong Kong private equity firm Affinity Equity Partners in 2016.

    Affinity attempted to divest its Burger King operations in South Korea and Japan in 2022 before pausing the auction. In June, the buyout group restarted the sale process for BKR, seeking an exit four years after first testing buyer appetite.

    Shifting format in Seongsu

    Fast-food chains across East Asia are building larger experiential flagships in high-footfall neighborhoods to protect margins against rising ingredient costs and weaker discretionary spending. Seongsu has become the preferred testing ground for experimental retail formats, drawing both domestic fashion pop-ups and international food brands trying to appeal to younger consumers.

    BKR will open Flameground on September 10, with transaction advisers watching whether the higher-margin concept supports the ongoing sale process.

  • Domino’s China Operator DPC Dash Adds 235 Stores as Revenue Hits RMB3.13 Billion

    Domino’s China Operator DPC Dash Adds 235 Stores as Revenue Hits RMB3.13 Billion

    DPC Dash added 235 net new Domino’s Pizza stores in China during the first half of 2026. Group revenue rose 20.8 per cent.

    Revenue for the six months ended June 30 reached RMB3.13 billion (US$440 million). Net profit rose 22.9 per cent year on year to RMB81 million, supported by a 7.1 per cent lift in same-store transactions.

    That buildout took the chain’s network to 1,550 stores across 75 cities. The operator entered 15 new municipal markets during the period.

    Pushing Into Lower-Tier Markets

    Lower-tier Chinese cities now make up the bulk of the brand’s footprint. The operator runs 1,018 stores outside Tier 1 hubs, compared with 532 locations across primary metropolitan areas.

    DPC Dash holds exclusive master franchise rights for Domino’s in mainland China, Hong Kong and Macau. Chief executive Aileen Wang said the company will focus on lifting average transaction value and expanding customer volume as third-party food delivery subsidies diminish across the sector.

    Western fast-food chains in China have redirected capital expenditure away from saturated top-tier cities to capture cheaper real estate and consumer demand in secondary markets. While quick-service competitors battle heavy price discounting on aggregator apps, Domino’s relies on its own delivery network and lower operating costs to protect unit margins.

    Pipeline Toward 350 Openings

    Between June 30 and August 14, the operator launched another 27 stores across the country.

    Another 38 locations are under construction, with 36 additional leases signed or approved. Those sites keep the business on track toward its full-year target of approximately 350 net new store openings.

  • Chris Hemsworth Buys Stake in Archie Rose Distilling Co

    Chris Hemsworth Buys Stake in Archie Rose Distilling Co

    Australian actor Chris Hemsworth has acquired an equity stake in Archie Rose Distilling Co, partnering with founder Will Edwards to finance an international retail rollout.

    The Sydney-based spirits producer plans to use the capital injection to enter the United States later this year while introducing three new whiskies across Asia and New Zealand.

    Global push from Sydney

    Hemsworth will work directly on product development at the distillery alongside his co-ownership role. The collaboration focuses on blending three distinct whiskies tailored for regional export markets.

    Archie Rose has built its business on botanical gins, single malts, and rye whiskies in Australia. Securing high-profile backing reflects a broader push by independent Australian craft distillers to secure distribution shelf space in high-margin Asian retail channels and premium hospitality venues.

    Whisky demand in Asia

    Regional consumers across Southeast Asia and East Asia continue to trade up into premium and craft brown spirits. Independent distillers often struggle against established global liquor conglomerates for retail distribution in major commercial hubs without significant marketing support.

    The company plans to complete its initial US market entry before rolling out the three Hemsworth-backed whisky releases to Asian retail partners in the coming months.

  • Lark Distilling Sales Rise 15% to $18 Million on Asia and Travel Retail Push

    Lark Distilling Sales Rise 15% to $18 Million on Asia and Travel Retail Push

    Tasmanian single malt whisky maker Lark Distilling Co lifted annual net sales 15.1 per cent to $18 million for the year ended June 30.

    Export expansion and global travel retail channels drove the performance, offsetting softer broader consumer spending in mature domestic bottle shops.

    Export Demand Drives Gains

    International sales jumped 69 per cent to $1.8 million during the 12-month period. Global travel retail delivered $2.2 million in sales, representing an increase of 43 per cent over the prior year.

    Lark now distributes its spirits across 10 Asian markets. Regional airport duty-free counters and specialty spirits retailers served as the primary entry points for the Tasmanian brand as it built overseas distribution volume.

    Regional Premium Spirits Shift

    Australian craft distillers are increasingly targeting Asia-Pacific travel corridors to find higher margin buyers for aged stock. Demand for premium brown spirits across North and Southeast Asia has created an opening for niche single malts outside traditional Scottish and Japanese categories.

    Distributors will track whether Lark can sustain double-digit overseas momentum as additional export inventory arrives across its newer Asian accounts in the coming quarters.

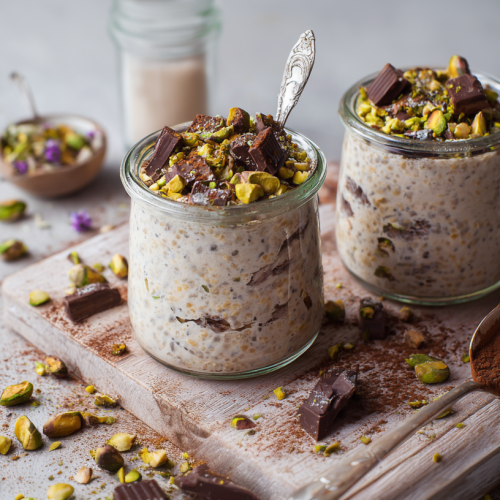
  • F&N Expands NutriWell Line with Pistachio Chocolate Oat Milk

    F&N Expands NutriWell Line with Pistachio Chocolate Oat Milk

    Fraser and Neave launched NutriWell Pistachio Chocolate Oatmilk in Singapore this week, adding a flavored nut-and-grain blend to its packaged wellness beverage portfolio.

    The formulation pairs dairy-free oat milk with pistachio and chocolate flavoring, positioning the product directly at shoppers looking for plant-based indulgence.

    Flavour Blends in Plant Milk

    NutriWell formulated the new release entirely free of dairy to cater to lactose-intolerant consumers and vegan shoppers. The recipe pairs oat milk with pistachio, a flavour that has gained rapid traction across regional bakery, ice cream, and specialty coffee menus over the past twelve months.

    Packaged in ready-to-drink cartons, the drink provides an alternative to conventional chocolate cow milk and plain soya drinks. F&N designed the line to sit in chilled retail cabinets alongside standard dairy items rather than specialty vegan shelves.

    Chilled Dairy Alternatives in Southeast Asia

    Regional beverage makers across Southeast Asia have shifted away from plain soy and almond bases toward composite grain formulations. Major bottlers now combine oat bases with dessert-inspired profiles to protect shelf space as standard plant milk volumes plateau in mature supermarket channels.

    Retail distribution is rolling out across Singapore supermarkets and convenience outlets this month, with regional channel expansion across Malaysia scheduled for the following quarter.

  • Chinese Restaurant Chains Target US Market as Domestic Growth Slows

    Chinese Restaurant Chains Target US Market as Domestic Growth Slows

    Chinese restaurant chains are expanding across the United States to offset slowing growth at home, betting American diners are finally ready to embrace authentic regional menus.

    The push enters a market that already counts more Chinese dining spots than individual locations of almost any major American fast-food chain. For decades, those menus relied heavily on Westernised adaptations like chop suey and fortune cookies, both created in the United States rather than mainland China. Traditional fare struggled to gain traction during the twentieth century as immigrant chefs navigated widespread consumer resistance and discrimination.

    Shifting from takeout staples to authentic menus

    Domestic headwinds across China’s dining sector are now accelerating the overseas push. Operators face tighter consumer spending and intense margin pressure in their home cities, making international expansion an urgent priority rather than a long-term experiment.

    Instead of modifying dishes to suit Western palates, newer entrants are bringing specialized formats straight from the mainland. Concepts range from high-end Michelin-starred Peking duck houses to regional hotpot and noodle formats. The shift reflects growing diner familiarity with authentic Chinese culinary traditions, moving the market away from generic takeout boxes toward distinct regional identities.

    Navigating saturated overseas markets

    Breaking into the American market presents operational hurdles despite the historical presence of Chinese food. Mainland chains must manage higher labor expenses, complex local supply chains, and entrenched domestic competitors while maintaining recipe authenticity.

    The test for Chinese operators is whether authentic regional concepts can capture mainstream suburban foot traffic or remain confined to dense urban centers with established Asian diaspora populations.

  • Australian Certified Organic Sales Hit AU$1.02 Billion

    Australian Certified Organic Sales Hit AU$1.02 Billion

    Australia certified organic sector generated AU$1.02 billion in annual sales during the 2024-25 financial year. The total represents the first time the market cleared the billion-dollar threshold, driven largely by supermarket shelves and household pantry purchases.

    Retail sales for take-home consumption reached AU$657.6 million, climbing 11.9 per cent year on year, according to the Australian Organic Market Report 2026 released by Australian Organic Limited. The growth in household buying outpaced broader packaged grocery volume across major Australian supermarket chains.

    Supermarket Aisles Drive Revenue Gains

    Packaged food and fresh produce accounted for the bulk of retail spend, with shoppers prioritizing chemical-free certifications despite broader inflationary pressures on household food budgets. Certified supply chains kept up with the volume demand, helping standardise shelf placements across national grocery operators.

    The AU$1.02 billion total spans domestic agriculture, food manufacturing and retail channels across the country. Commercial operations continued converting conventional acreage to certified standards to capture premium wholesale margins.

    Wholesale Margins and Export Volumes

    Across the Asia-Pacific region, premium food producers face tight price sensitivity, yet certified organic goods continue to hold distinct price premiums in tier-one retail channels. Australian producers are positioning their certified output against competing high-end food exports from New Zealand and Europe.

    Industry bodies will monitor whether retail volume growth holds through the 2025-26 period as supply contracts renew and private-label organic ranges expand in major supermarket chains.