Tag: E-Commerce

  • Bukalapak Posts IDR 821 Billion Half-Year Loss on Investment Decline

    Bukalapak Posts IDR 821 Billion Half-Year Loss on Investment Decline

    PT Bukalapak.com Tbk reported a net loss of IDR 821 billion for the first half of 2026 in Jakarta, dragged down by an IDR 1.74 trillion investment loss.

    The result followed a loss of IDR 426 billion in the first quarter and a further shortfall of IDR 395 billion in the second quarter. Top-line performance moved in the opposite direction, with revenue rising nearly 30 percent year on year to IDR 3.99 trillion across the six-month period.

    Gaming Carries Top-Line Growth

    Gaming generated IDR 3.48 trillion during the half, making up 87.31 percent of total revenue. The division delivered an operating profit of IDR 76.3 billion, anchoring the company’s core earnings.

    Online-to-offline operations brought in IDR 326 billion in revenue and generated an operating profit of IDR 10.45 billion. Retail revenue contributed IDR 139 billion, while investment income added IDR 44.4 billion and corporate revenue stood at IDR 1.83 billion.

    Investment Portfolio Weighs on Corporate Segment

    Losses in non-core units offset the gains made by gaming and merchant networks. The corporate division posted the steepest deficit at IDR 885 billion, primarily reflecting the IDR 1.74 trillion drop in the value of its investment holdings.

    Financial statements showed a net cash outflow of IDR 2.32 trillion from investing activities during the half. Bukalapak directed IDR 3.07 trillion toward additional investments and allocated IDR 70 billion in capital injections to associated entities.

    Shift Away From Marketplace Operations

    Bukalapak exited its traditional e-commerce marketplace in early 2025. That decision eliminated the heavy merchant subsidies and logistics spending that weighed on cash flow for years, reorienting the business toward digital item distribution and treasury management.

    The pivot leaves the Emtek Group-backed company operating more like an asset allocator with a digital entertainment distribution engine than a conventional shopping platform. While gaming provides cash generation, corporate earnings remain exposed to public equity valuations and mark-to-market adjustments.

    Digital Banking Exposure and Market Pressure

    Much of that valuation pressure stems from listed holdings acquired during the tech boom. Bukalapak has held an 11.49 percent equity stake in PT Allo Bank Indonesia Tbk since January 2022, when the digital lender traded above IDR 5,000 per share.

    Shares in the digital bank have fallen to IDR 900 each, dropping almost 40 percent since the start of 2026. Investors will watch whether the board adjusts its marketable securities portfolio before third-quarter financial results are filed later this year.

  • Australia Post Prepares for 120 Million Parcels as Peak Volumes Rise 7.8 per Cent

    Australia Post Prepares for 120 Million Parcels as Peak Volumes Rise 7.8 per Cent

    Australia Post expects to handle more than 120 million parcels during the year-end shopping period, recruiting 3,900 casual staff after volumes rose 7.8 per cent over four weeks.

    The postal carrier projects total seasonal volume growth between 6 and 8 per cent compared to the same stretch last year. Logistics managers and retail executives outlined their operational readiness during Australia Post’s Peak Halftime Huddle briefing, detailing delivery cut-offs, inventory flows and margin pressures across the Australian retail sector.

    Network Deadlines And Labour Capacity

    StarTrack Road Express shipments face a final lodgement deadline of December 19 to guarantee delivery before Christmas Day. Standard Parcel Post items must enter the network by December 21 for most Australian destinations. Express Post, StarTrack Premium and metro services maintain operations until December 23.

    Shane Plant, executive general manager of network operations at Australia Post, confirmed the 7.8 per cent jump in lodgements recorded across the preceding four-week window. The state-owned carrier is deploying temporary sorting labour across major hubs to clear intake spikes before parcel bottlenecks reach regional distribution centres.

    Carriers across the Asia-Pacific region face similar volume concentrations as year-end discount events pull fourth-quarter demand forward. Australian merchants run narrower transport buffers than regional counterparts in Japan or Singapore because of domestic transit distances, leaving little margin for warehouse sorting delays or misrouted freight.

    Australian Retail Council chief executive Chris Rodwell warned that higher gross sales do not guarantee healthy earnings. Heavy promotional discounting across Cyber Weekend threatens net profit margins if retailers rely entirely on markdown pricing to hit revenue targets before trade slows in January.

    Discount Fatigue And Margin Protection

    Consumer behaviour shows tighter spending discipline despite rising parcel volumes. Research cited by Victoria Devine, founder of financial education platform She’s On The Money, showed 81 per cent of Australian shoppers compare prices across multiple merchants before buying. Another 59 per cent stated they refuse to purchase products at full ticket price.

    Early buying patterns have also shifted. Last year, 29 per cent of consumers completed their holiday purchases early, compared with just 8 per cent who waited until the final weeks of December. Retailers face shoppers who are prepared to delay purchases until automated price drops trigger.

    Kip&Co chief executive Chris Miles said the homewares merchant is introducing exclusive product ranges and partner collaborations rather than discounting entire core catalogues. Wesfarmers Health general manager of e-commerce and loyalty Leela Sennitt reported that its Pulse Rewards program is deploying value-add incentives, early access windows and member gift packs to protect base product margins.

    Store Operations And Click And Collect

    Adairs Group is handling higher store pickup traffic to bypass peak courier charges and delivery cutoff constraints. Chief executive Elle Roseby reported double-digit growth in click-and-collect orders, prompting the business to overhaul store fulfillment processes and eliminate split-order shipments from separate regional warehouses.

    Physical store networks provide crucial fulfillment relief when carrier collection windows close. Retailers that integrate inventory systems between point-of-sale registers and distribution centres convert foot traffic into incremental sales, capturing add-on purchases when shoppers arrive at stores to collect parcels.

    Earlier supply chain audits across the Australian retail sector identified split fulfillments as a primary driver of customer support costs and freight surcharges during the 2023 holiday rush. Resolving order grouping before dispatch protects trading margins against multiple last-mile courier fees.

    Fulfillment Errors And Packaging Friction

    Automated sorting systems face processing disruptions from unreadable barcodes and non-standard parcel dimensions. Australia Post executive general manager for parcel post and e-commerce services Gary Starr pointed to warehouse labelling standards as a critical factor in network throughput.

    “It sounds really basic, but a bad label can’t get read, goes around the machine three times, takes up a cell that another parcel could have been on,” Starr said.

    Retailers are running out of time to reconfigure packing lines before Cyber Weekend lodgements peak in late November. Carrier sorting centres will begin applying standard processing cutoffs as the December 19 freight deadline approaches.

  • Maldives Delays 17% Tax on Foreign Travel Platforms to April

    Maldives Delays 17% Tax on Foreign Travel Platforms to April

    The Maldives has delayed its planned 17 percent tax on foreign tour operators and digital booking platforms until April 1 next year. The levy was scheduled to take effect on October 1.

    Tourism and Civil Aviation Minister Mohamed Amin announced the deferral during National Tourism Day celebrations. The decision followed pushback from international travel agencies and tour operators. The tax applies to overseas suppliers and digital aggregators that sell resort stays and packages without maintaining a physical office in the country.

    How the Registration System Works

    Under the revised Tourism Goods and Services Tax framework, offshore booking channels and outbound wholesalers must register directly with Maldivian tax authorities. The government expects the broadened net to generate MVR1.6 billion ($104 million) in additional revenue ahead of its Visit Maldives 2027 promotional campaign.

    Foreign distributors warned that adding a 17 percent assessment onto wholesale margins would force immediate retail price hikes across key feeder markets. Travel sellers in Europe and Asia raised concerns. The sudden rollout left no time to reprice contracted resort inventory or update customer billing systems.

    Margin Pressure on Asian Wholesalers

    For online travel platforms and regional wholesalers, the Maldives represents one of the highest average-order-value destinations in Asia-Pacific. Direct registration and local tax remittance mirror digital services taxes introduced across Southeast Asia. Still, applying the full 17 percent rate directly to foreign intermediaries creates immediate friction for packaged holiday sellers.

    India remains one of the largest source markets for Maldivian resorts. That makes Indian travel operators particularly sensitive to the fiscal shift. The Outbound Tour Operators Association of India warned that the additional tax burden and registration compliance would make vacations uncompetitive against alternative island destinations in the region.

    European Operators Seek Legal Clarity

    European industry bodies lobbied Maldivian authorities to scrap or defer the measure, arguing that tour operators would either absorb steep margin losses or pass costs onto travelers already facing higher airfares. Because the underlying legislation had technically taken effect on October 1, distributors faced weeks of legal ambiguity before the minister announced the delay.

    Until there is official confirmation and proper engagement between the Government and industry, the situation remains difficult for members.

    Officials at the U.K. Association of British Travel Agents pointed out that formal administrative circulars must follow public speeches to provide legal certainty for travel sellers holding future bookings.

    Target Date for Final Compliance Rules

    The six-month reprieve gives the Ministry of Tourism and tax authorities time to publish technical registration guidelines before the new April 1 deadline. Travel sellers are watching for detailed rules on how offshore portals must file returns and whether existing wholesale contracts signed for early 2027 will receive transitional exemptions.

  • Boody Adds $700,000 in Annual Sales by Replacing Tape Measures with Guided Sizing

    Boody Adds $700,000 in Annual Sales by Replacing Tape Measures with Guided Sizing

    Australian apparel brand Boody generated an estimated $700,000 in extra annual revenue across Australia and New Zealand after replacing static size charts with guided sizing software.

    A split test run across 230,000 shopper sessions from August 28 revealed that roughly one in eight first-time buyers abandoned purchases when forced to use traditional measurement tables.

    The Conversion Cost of Tape Measures

    Boody started testing Magic Fit software in March 2026 to resolve sizing drop-offs across its bamboo viscose underwear and wire-free bra collections. Because the brand produces bras in sizes XS to 4XL across three cup ranges rather than traditional band-and-cup measurements, shoppers struggled to match their dimensions to products.

    A post-purchase survey of 816 shoppers who used the tool found that 41 per cent did not own a soft measuring tape, could not locate one, or refused to use it while shopping online. For the remaining 59 per cent who owned measuring tapes, confusion over non-standard sizing categories remained the primary barrier to purchasing.

    Repeat Orders and Lower Return Rates

    Shoppers assigned to the guided sizing tool reordered 19 per cent more frequently over a 90-day tracking window than those who used standard size charts. Of the survey respondents whose parcels had arrived, 97 per cent kept their items, with fit-related returns and exchanges dropping to 3 per cent.

    Magic Fit generates size recommendations in two clicks by drawing on a proprietary dataset of more than 100,000 body scans compiled over a decade by sister apparel label Citizen Wolf. The tool aims to cut friction before checkout rather than relying on post-purchase return logistics to sort out sizing mismatches.

    What Sizing Friction Means for Online Retailers

    For direct-to-consumer apparel brands across Asia-Pacific, static measurement guides have become an expensive point of friction. Online shoppers increasingly purchase on mobile devices where switching tabs to look up body dimensions reliably kills conversion.

    Retailers that rely on proprietary fabrics or non-standard fit profiles carry the highest risk of abandonment. When brands force customers to calculate their own measurements, they transfer the burden of fit accuracy to the buyer, driving up customer acquisition costs and depressing lifetime value.

    Evolution of Boody’s Digital Operations

    The sizing overhaul follows Boody’s broader push to expand its basic-wear footprint across regional digital channels. The brand previously relied on manual dimension tables across its localized storefronts in Australia and New Zealand before rolling out algorithmic recommendations.

    Magic Fit co-founder Zoltan Csaki is now offering 30-day split tests to other regional apparel merchants to benchmark checkout drop-offs against their existing size tables.

  • DuitNow Caps Singapore Cross-Border Fund Transfers at RM3,000 a Day

    DuitNow Caps Singapore Cross-Border Fund Transfers at RM3,000 a Day

    Malaysian merchants processing cross-border remittances through the national DuitNow payment network face an outbound ceiling of RM3,000 a day for fund transfers to Singapore as of October 2026.

    Domestic business transfers across the same network clear up to RM10 million per transaction, highlighting the gap between local retail payment rails and regional settlement links.

    Operated by Payments Network Malaysia, known as PayNet, the retail payments platform functions under the primary ownership of Bank Negara Malaysia alongside commercial lenders. The infrastructure connects commercial banks and non-bank e-wallets into a single interoperable clearing system. Retailers and suppliers send and receive funds using proxy identifiers including mobile numbers, identity card records and verified Business Registration Numbers issued by the Companies Commission of Malaysia.

    Domestic Transfer Limits and Merchant Fees

    Consumer transactions clear up to RM50,000 per transfer through commercial banking applications, with transfers up to RM5,000 processed without consumer transaction charges. Above that threshold, financial institutions may levy a 50 sen fee, though individual retail banks retain discretion to waive the charge. Commercial users maintain higher headroom, clearing up to RM10 million per transaction subject to institutional credit and fraud underwriting terms.

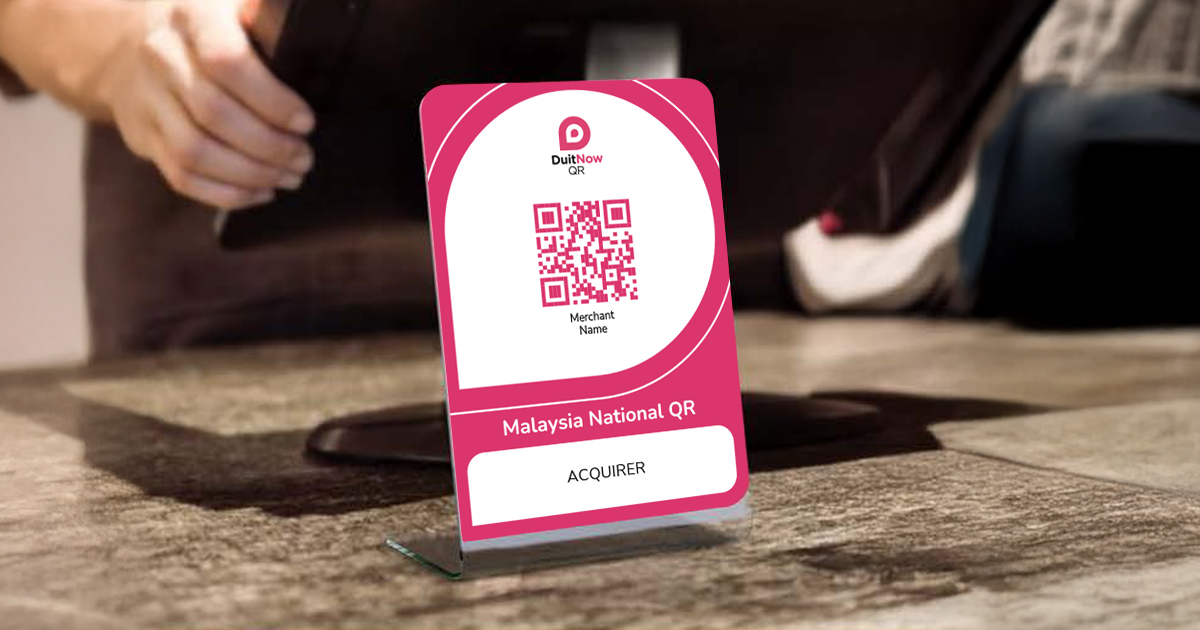
    Point-of-sale retail payments operate through unified QR standards. Merchants deploy a single static or dynamic QR code that accepts clearing requests from all domestic mobile banking applications and licensed e-wallets. Consumer payments remain fee-free at retail counters, while merchant discount rates apply to retail enterprises depending on their merchant acquirer contract.

    E-commerce checkout integrations route directly through DuitNow Online Banking and Wallets, bypassing traditional payment card rails. The direct routing pulls cleared funds directly from buyer accounts without requiring debit card credentials. For recurring invoicing, the network deploys AutoDebit protocols that clear utility billings, subscriptions and recurring wholesale invoices under pre-authorised value limits without recurring manual approvals.

    Regional Settlement Links and Currency Controls

    Inbound cross-border retail acceptance currently covers visiting consumers from six Asian economies: China, Indonesia, Singapore, Thailand, South Korea and Cambodia. Tourists and business travellers scan local merchant QR codes using their domestic banking apps. Settlements convert automatically, crediting Malaysian merchant bank accounts exclusively in Malaysian ringgit.

    Merchants cannot hold foreign currency balances directly inside the DuitNow clearing architecture. Exchange rates for incoming tourist QR spending are determined by the originating overseas payment application at the point of interaction. This leaves cross-border sellers exposed to conversion markups set by foreign issuing institutions.

    Outbound commercial transactions across the border face structural barriers. While the bilateral corridor with Singapore enables retail peer-to-peer transfers, the daily cap of RM3,000 or S$1,000 restricts corporate trade settlement. Companies paying overseas manufacturers, regional software vendors or inventory partners require separate international clearing rails or multi-currency corporate banking accounts.

    Payment Rail Fragmentation Across Retail Chains

    Retail chains across Southeast Asia are weighing single-currency domestic payment rails against cross-border fintech platforms. The local DuitNow architecture eliminates domestic card processing interchange fees, yet fails to provide working capital accounts in trade currencies such as the US dollar.

    Cross-border procurement teams that purchase stock from Mainland China or regional suppliers cannot use PayNet rails to settle trade invoices. The limitation forces operators to run dual payment workflows: national QR and real-time bank transfers for domestic store sales, and cross-border platforms such as WorldFirst or SWIFT wire transfers for import settlement. For high-volume retail chains, maintaining dual clearing mechanisms adds operational reconciliation costs and exposure to retail foreign exchange spreads.

    The operational split gives pure-play international corporate treasury providers an opening against state-backed retail clearing systems. Commercial banks capture high spreads on foreign exchange wire transfers, driving online sellers and cross-border merchants toward multi-currency accounts that issue local clearing details in overseas markets.

    Building the Regional Payment Network

    PayNet developed DuitNow to consolidate a fragmented mobile payment sector where competing digital wallet operators deployed incompatible proprietary QR codes. The central bank intervened to mandate standardisation, creating a shared national QR code and central proxy registry.

    The central bank expanded the domestic retail clearing platform through bilateral central bank linkages, starting with Thailand and Indonesia before connecting Singapore PayNow. The bilateral linkages aim to reduce regional reliance on traditional card networks and correspondent banking systems for micro-transactions and tourism spending.

    Bank Negara Malaysia and regional central banks continue testing multilateral clearing arrangements across ASEAN economies, with broader business settlement ceilings remaining the key requirement for commercial supply chain operators.
  • FairPrice Deploys 3,000 Smart Trolleys as Retailers Turn to In-Store Media

    FairPrice Deploys 3,000 Smart Trolleys as Retailers Turn to In-Store Media

    Retailers are expanding into advertising, fintech services, and data monetisation as intensifying competition puts pressure on product margins.

    FairPrice Group has deployed about 3,000 smart trolleys across selected stores ahead of a wider rollout planned for 2027, linking carts to shopper app accounts to personalise ads and offers.

    Speaking at the Retail Asia Summit 2026 in Singapore, Sanjay Singh, senior vice president for the Investor Transformation group at Frost & Sullivan Asia Pacific, said retail media can become a profit engine for physical stores by connecting demand, inventory, payments, and fulfilment.

    Smart Carts and Targeted Health Campaigns

    Grocery operators are using point-of-sale data to sell brand campaigns inside physical aisles. Rajiv Singh, head of the retail media network at FairPrice Group, said an in-store initiative run with Singapore’s Health Promotion Board shifted 12 percent of approximately 500,000 targeted shoppers toward lower-sodium product alternatives. The state health agency is now doubling the budget and scale of the campaign.

    Ad deals are benchmarked on incremental return. The grocer measures exact sales generated per marketing dollar spent. Linking smart shopping trolleys directly to the FairPrice mobile app allows the chain to trigger personalized promotions as shoppers navigate aisles.

    Packaged goods manufacturers gain direct access to verified purchase histories through these retailer-owned networks. Brands pay premiums for verified basket conversions rather than broad digital impressions across open web platforms.

    Extending Sales Windows Beyond the Store

    Duty-free and department store operators are adjusting checkout rules to capture spending outside physical premises. The Shilla Duty Free now allows travelers to purchase merchandise via the iShopChangi platform up to 30 days after their trip, according to Joanne Soh, head of consumer marketing and e-commerce at the travel retailer.

    A wider post-travel purchasing window lets airport retailers recover sales lost to tight flight schedules and carry-on luggage limits. Physical airport storefronts become discovery showrooms backed by centralized domestic delivery.

    Department store operator Metro Singapore is reallocating floor space toward targeted customer problems. Henry Christian, head of loyalty, marketing and partnerships at Metro Singapore, pointed to the retailer’s Sleep Lab concept, launched on World Sleep Day on 15 March. The format evaluates brand participation and customer discussions alongside standard sales volumes.

    Micro Occasions and Quick Commerce Channels

    Food makers are mining retailer transaction data to generate sales outside traditional peak holidays. Kenneth Lau, global digital commerce excellence lead at Mondelēz International, said digital commerce accounts for roughly 41 percent of the company’s sales this year. That channel delivers 61 percent of its total growth.

    In China, Mondelēz partnered with on-demand delivery giant Meituan to target office afternoon tea breaks, tailoring Oreo product selections specifically for immediate local fulfillment. The confectionery group also created an exclusive digital-commerce gift box for its BTS brand collaboration priced at about $15, selling out 20,000 packs on Shopee across Southeast Asia within seven days.

    Furniture retailer Castlery is focusing investments strictly on measurable omni-channel systems. Leah Howatson, general manager for international markets at Castlery, said the company synchronizes online shopping carts with physical store systems so staff can complete purchases started online, while scaling back curated experiential events that failed to deliver adequate return on investment.

    Balancing Capital Outlays Against Ad Revenue

    Retail media networks are creating a split between high-volume grocers and discretionary specialty chains. Supermarket operators control the recurring transaction volume required to justify in-store screens, trolley hardware, and data infrastructure. Discretionary chains lack that visit frequency. They struggle to build ad scale, forcing them to focus on cart synchronization and extended checkout windows instead.

    Physical rollouts still face operational hurdles from hardware maintenance, screen vandalism and basement mobile network dead zones. Retailers that over-invest in in-store hardware without securing long-term brand ad commitments risk adding capital costs without lifting net margins.

    Attention now turns to FairPrice’s planned 2027 fleet expansion for smart carts across its full Singapore footprint, which will test whether ad-supported trolley systems generate sustainable yields across suburban store formats.

  • SurfStitch Cuts Annual IT Costs to $400,000 in Marketplace Overhaul

    SurfStitch Cuts Annual IT Costs to $400,000 in Marketplace Overhaul

    In October 2026, ten months into a restructuring led by Olvera Advisors, Australian online retailer SurfStitch has rebuilt its operating model as a curated marketplace, cutting annual fixed IT costs from close to $1.2 million to around $400,000.

    The business now hosts roughly 75 predominantly domestic labels on a variable-cost architecture powered by Shopify and HubSpot, ditching wholesale inventory risk to arrest years of margin erosion.

    Rewriting the commercial terms for brands

    Under the restructured model, participating labels manage their own fulfillment and pricing rules while agreeing to keep core product lines at full price outside scheduled promotional windows. The platform prohibits wholesale inventory dumping, preventing suppliers from using the digital storefront as a discount clearance outlet. Brands must match their own direct-to-consumer digital pricing rather than undercutting the channel.

    Restructuring lead Damien Hodgkinson has limited total seller onboarding to protect vendor visibility. Rather than competing against thousands of merchants on catch-all apparel portals, sellers on the platform retain category focus across surf, outdoor, street and coastal lifestyle lines.

    Building utility to drive repeat visits

    Traffic generation has shifted from discount email blasts to editorial and activity hubs designed to capture search intent. The storefront now operates three recurring services: a daily surf report tracking swell and tide across 100 Australian beaches, a dedicated trail guide for hikers, and a coastal live music directory.

    These utility features funnel organic visitors directly into targeted product categories such as apparel, technical footwear, surfboards, water bottles and electric bikes. Customer browsing history across the guides feeds behavioral profiles, replacing broad discounting campaigns with targeted gear suggestions.

    Shifting wholesale pressure across Asia-Pacific e-commerce

    Pure-play apparel retail across the Asia-Pacific region is colliding with the limits of discount-led customer acquisition. Regional aggregators that built scale on debt and perpetual clearance sales have faced severe margin contraction as performance marketing costs climbed and global labels pulled back inventory allocations. By offloading inventory risk directly to brand partners, marketplace operators shift working capital burdens back upstream.

    The critical vulnerability sits in customer retention. Retraining a legacy database conditioned on clearance coupons to pay full retail price routinely triggers high churn rates. If converted shoppers bypass the marketplace to transact directly on brand websites once discovery happens, take rates will not cover customer acquisition overhead.

    From insolvency proceedings to solvent platform

    Best Markets Group acquired SurfStitch from Alquemie Group in March 2025 before a dispute with a landlord and petitioning creditor Nike forced the business into voluntary administration. Turnaround firm Olvera Advisors took control of the asset, securing creditor approval for a Deed of Company Arrangement before overhauling the underlying software stack and vendor contracts.

    Management plans to expand the product catalogue into winter snowsports next season, with overall transaction volume on the restructured platform serving as the benchmark for sustained solvency.

  • Pakistan Ad Market Shifts to Influencers as Social Media Reaches 80 Million Users

    Pakistan Ad Market Shifts to Influencers as Social Media Reaches 80 Million Users

    Pakistan’s advertising market is shifting toward content creators as of October 2026, with the country recording around 80 million adult social-media user identities.

    TikTok alone has an advertising reach approaching 80 million adults, while YouTube reaches around 54 million and Instagram reaches approximately 22 million.

    Individual creators are amassing major audiences, including Jannat Mirza with over 25 million TikTok followers, Hania Aamir with over 20 million Instagram followers, Ducky Bhai with over 10 million YouTube subscribers, and Rajab Butt with around 9 million.

    Performance Models Replace Flat Sponsorship Fees

    Commercial deals are shifting from flat fees to direct affiliate commissions. Smaller creators take free merchandise or modest cash retainers, while top celebrities still charge premium rates. Retail brands now deploy trackable discount codes and custom referral links.

    A merchant offering unique promo codes across 100 creator accounts can measure exact conversions within days. That turns endorsements into direct sales channels. For consumer startups and domestic cosmetic lines, performance deals offer instant distribution without the steep upfront costs of television runs.

    Niche Conversion Challenges Follower Scale

    Relevance now matters more than raw follower totals in campaign planning. A specialised account with 50,000 motorcycle enthusiasts regularly delivers higher conversion rates for vehicle parts suppliers than a general entertainment channel with five million subscribers.

    This mirrors digital commerce across Southeast Asia and China, where live-stream selling ties demonstrations straight to payment and fulfilment. Pakistan holds the same ingredients: expanding smartphone adoption, digital payment rails and a young urban population accustomed to mobile buying.

    Metrics Move Toward Acquisition and Retention

    Rapid growth has brought friction over audience authenticity and transparency. Brands face risks from synthetic engagement, bought follower counts and unclear commercial disclosures. These hazards run highest in regulated sectors like consumer health and financial services.

    Marketing teams now evaluate creator deals against customer acquisition costs, basket sizes and repeat order rates instead of vanity impressions. That demand is fueling dedicated talent management agencies, affiliate platforms and analytics firms across Karachi and Lahore.

    Traditional Media Monopolies Recede

    Billboards, print ads and television commercials still draw institutional budgets, but legacy networks no longer control consumer reach. Independent creators now build audiences larger than broadcast stations from home setups.

    Budgets will track verified checkouts as consumer brands watch whether creator live streams deliver steady sales through upcoming festive shopping cycles.

  • Former Flipkart Staff Mobilise for Share in Proposed $2 Billion Share Buyback

    Former Flipkart Staff Mobilise for Share in Proposed $2 Billion Share Buyback

    A group of former Flipkart executives has launched a campaign to mobilise up to 30,000 former staff across India. They are demanding inclusion in a proposed $2 billion share buyback.

    The petition started on October 10. It targets parent company Walmart, which refused to guarantee immediate liquidity for vested options held by departed workers.

    Organisers represent alumni from the core marketplace alongside group subsidiaries Myntra, Cleartrip, Shopsy, Super Money and ANS Commerce. They want Walmart to open the upcoming repurchase pool to former staff rather than restricting payouts to current employees.

    Three Demands Put To Bentonville

    This campaign sets out three operational demands for Walmart and Flipkart leadership before the $2 billion deal closes.

    First, the group wants the exercise window for vested stock options extended until a liquidity event takes place. Second, ex-staff seek full participation rights in the buyback on identical terms to current workers, rejecting any nominal allocation. Third, the petition demands a formal corporate liaison to negotiate directly with an elected alumni committee.

    Former employees frame the campaign as an invitation to commercial dialogue rather than a legal dispute. Early staff took pay cuts and career risks during Flipkart’s early growth. In exchange, they received equity that has remained illiquid for over a decade.

    Escalating Pressure After Leadership Letter

    An earlier October 1 letter went directly to Walmart’s board from several former operating leaders. Signatories included Myntra cofounder Mukesh Bansal, former Flipkart group chief financial officer Sanjay Baweja and former chief business officer Ankit Nagori.

    Those executives asked for an exit route for options granted between 10 and 15 years ago. Walmart’s legal counsel responded that former staff would be considered during an eventual initial public offering. Counsel offered neither a timeline nor a binding commitment.

    Alumni pushed back against the stance. Without a filed prospectus and in volatile markets, waiting for a listing creates open-ended holding risk for departed option holders.

    The Valuation Divide In Indian Tech

    For technology operators and private equity backers across Asia, the Flipkart dispute reflects broader friction over long-dated employee equity. Indian tech platforms routinely issued options instead of cash compensation during market-share battles between 2012 and 2020. Listing timelines now stretch from five years to fifteen. Those incentive structures leave buyers with heavy balance sheet overhangs and reputational exposure.

    Walmart ring-fenced previous cash distributions for active staff to protect employee retention in India. In July, Flipkart ran a $50 million liquidity round letting eligible current staff cash out up to 5 percent of their vested options at a $38.2 billion valuation. Excluding alumni while paying current staff deepens the rift between early builders and incoming corporate managers.

    Redomiciling And Listing Uncertainty

    Flipkart cleared a major corporate hurdle in March by moving its corporate domicile from Singapore back to India. The tax restructuring clears a path for a domestic listing. Still, the group has not filed a schedule with market regulators.

    Speaking on the company’s listing road map in a July interview, Flipkart group chief executive officer Kalyan Krishnamurthy said:

    We don’t have any timeline right now and, to be very clear, we never have had any timeline for going public. It’s not a management-only decision that can be made.

    Walmart has not responded publicly to the broader staff petition. Attention now turns to whether the retailer finalises the terms of the $2 billion buyback without an alumni carve-out before the end of the financial quarter.

  • Bukalapak Appoints Natalia Firmansyah Acting CEO After IDR 3.1 Trillion Profit

    Bukalapak Appoints Natalia Firmansyah Acting CEO After IDR 3.1 Trillion Profit

    Indonesian technology company Bukalapak has appointed Natalia Firmansyah as acting chief executive officer, succeeding Willix Halim following shareholder approval at the company’s 2026 annual general meeting of shareholders.

    Firmansyah, who has served as Bukalapak’s chief financial officer since 2018, will lead the company until a permanent CEO is appointed in accordance with recommendations from the nomination and remuneration committee.

    The leadership transition follows Bukalapak reporting its first annual net profit since listing, posting earnings of IDR 3.1 trillion (US$174 million) in 2025 after pivoting away from physical goods sales toward higher-margin digital businesses.

    Board Overhaul in Jakarta

    Shareholders also approved wider governance changes across the leadership team. Victor Putra Lesmana was reappointed to the board of directors. He retains his operational focus across the company’s financial services and commercial units.

    Former Indonesian National Police chief Sutarman joined the board of commissioners as independent commissioner and president commissioner. The company said his appointment strengthens oversight in risk management and cybersecurity. Meanwhile, Yenny Wahid concluded her term as independent commissioner and environmental, social and governance ambassador.

    Pivoting from Marketplace Burn

    Across Southeast Asia, the executive reshuffle reflects the end of subsidized physical e-commerce battles against deep-pocketed regional rivals. Competing directly with platforms funded by regional conglomerates drained cash for years. That pressure forced Jakarta-listed tech firms to rethink their core units.

    Bukalapak chose to retreat from direct physical goods sales. It shut down physical product operations and cut headcount to stem operating losses. That decision redirected capital into virtual items, gaming product distribution, specialized investment services through BMoney, and the Mitra Bukalapak offline merchant network.

    Turning Cash Flow Positive

    That retreat delivered the IDR 3.1 trillion net profit recorded in 2025. It proved that trimming gross merchandise value in physical retail can protect margins. Operating across gaming, online-to-offline, investment and corporate segments allowed the platform to monetize higher-margin digital traffic instead of funding delivery logistics.

    Risk now shifts from cash preservation to revenue growth. The company proved it can run profitably without subsidizing consumer deliveries. Next, the new leadership team must demonstrate that specialized digital services and offline kiosk networks can expand their revenue base in secondary and tertiary Indonesian cities.

    Next Steps for Management

    Founded in 2011, the company raised US$1.5 billion in its initial public offering in Jakarta in 2021 before burning capital in general e-commerce competition. Its pivot toward virtual items and offline merchant services then formed the blueprint for the 2025 financial turnaround.

    Looking ahead, the nomination and remuneration committee has yet to set a deadline for its permanent chief executive recommendation. Until then, Firmansyah will steer corporate strategy and product integration across all five operating divisions.

  • Bukalapak Captures 584 Million Dollars Across Ten Private Funding Rounds

    Bukalapak Captures 584 Million Dollars Across Ten Private Funding Rounds

    Indonesian e-commerce operator Bukalapak accumulated 584 million dollars across 10 private financing rounds before leaning into financial services and merchant digitisation in Jakarta.

    Institutional backing from 26 corporate and venture investors financed the marketplace through six late-stage rounds, three early-stage rounds and a single seed injection.

    Capital allocations peaked during a Series G sequence between late 2020 and April 2021. Microsoft led the platform’s largest single transaction with a 234 million dollar round on April 14, 2021, drawing capital from Singapore sovereign wealth fund GIC, media conglomerate Emtek, SC Ventures, South Korea’s Naver, Mandiri Capital Indonesia, BRI Ventures and Bank Rakyat Indonesia.

    The Capital Structure Behind Series G

    The final private funding push followed a 200 million dollar tranche led by Standard Chartered in January 2021 and an initial 100 million dollar Microsoft-led commitment in November 2020. The trio of late-stage injections provided Bukalapak with balance sheet stability to build out merchant banking integrations and enterprise services across secondary Indonesian cities.

    Strategic investors dominated the share register over financial venture firms. State lenders Bank Rakyat Indonesia and Bank Mandiri entered through their corporate venture arms to link offline retail kiosks, known locally as warungs, directly into banking and payment networks.

    Valuation Milestones and Early Backers

    Bukalapak achieved unicorn status in November 2017 following a Series C round backed by GIC and Ant Group that valued the business at 1 billion dollars. Subsequent rounds pushed that valuation upward, reaching 1.2 billion dollars in January 2019 after a 50 million dollar Series D round led by Naver and Mirae Asset Global Investments, with participation from Ant Group and Endeavor Catalyst.

    Valuation numbers peaked in private markets at 2.5 billion dollars in October 2019 during a Series F round led by South Korea’s Shinhan Financial Group alongside Emtek. Early development had relied on smaller regional funds, beginning with an undisclosed seed round from Batavia Incubator in July 2011 and early venture rounds from Japan’s Strive, 500 Global, Aucfan, IREP and KMK Online between 2012 and 2015.

    Shifting Focus From Consumer Marketplaces

    Competition in Southeast Asian e-commerce forced Bukalapak to pivot away from direct consumer subsidies against rivals Shopee and Lazada. The platform redirected capital into Mitra Bukalapak, supplying fast-moving consumer goods and digital billing terminals to neighborhood mom-and-pop stores that represent the bulk of Indonesia’s retail economy.

    Specialist digital investment platforms such as Ajaib, which raised 515 million dollars across six rounds including a 270 million dollar Series C to reach a 1 billion dollar valuation, increased competition for consumer retail savings. Bukalapak countered by integrating investment products and micro-insurance distribution directly into its offline agent network.

    Investor Networks and Next Operational Targets

    Global funds continue to monitor Southeast Asian digital retail assets as broader ecosystem funding recovers. Endeavor Catalyst closed its 320 million dollar Fund V to back growth-stage operators across emerging markets, maintaining a portfolio that includes Bukalapak alongside automotive platform Carsome and fintech group Advance Intelligence.

    Management attention now centers on widening transaction margins across offline retail fulfillment lines and preserving cash reserves as digital commerce platforms navigate tighter lending conditions across Southeast Asia.

  • Bukalapak Extends Positive EBITDA Streak in Q2 Despite First-Half Net Loss

    Bukalapak Extends Positive EBITDA Streak in Q2 Despite First-Half Net Loss

    Bukalapak extended its run of positive adjusted EBITDA through the second quarter, maintaining operating profitability across core business units despite reporting a net loss for the first half.

    The Indonesian tech group balanced tighter operational spending across its marketplace and merchant network against bottom-line pressures that kept first-half net earnings in negative territory.

    Operating Discipline Across Units

    Second-quarter performance showed steady cost control across business segments. Management kept overhead tight while protecting revenue from offline-to-online merchant partners and specialized online commerce categories.

    Operating expenses fell in key administrative and marketing lines. That disciplined spending allowed adjusted earnings before interest, taxes, depreciation, and amortization to stay positive for consecutive reporting periods.

    Shifting Focus to Core Margins

    Merchant solutions and offline partner services formed the primary engine for the operating result. The company focused resources on profitable transactions rather than subsidizing top-line gross merchandise value across low-margin consumer retail categories.

    For investors, the divergence between positive EBITDA and a statutory net loss points directly to non-operating factors. Net results reflect mark-to-market adjustments on investments and financial assets rather than everyday cash burn from core commercial units.

    Regional Platform Competition

    Across Southeast Asia, online marketplaces have abandoned customer acquisition subsidies to protect cash reserves. Bukalapak took that step earlier than its regional peers, pivoting away from direct competition in mass consumer e-commerce to protect its balance sheet.

    Competitors across Indonesia continue to face intense margin pressure from social commerce platforms and fast-delivery networks. By prioritizing specialized commerce niches and physical kiosk networks, the group avoided the heavy promotional spending draining rival platforms.

    Balance Sheet and Next Steps

    Earlier quarters established the foundation for this operating run as leadership cut peripheral projects and reduced headcounts. The first-half figures confirm that core operations can run without burning operating capital, even as accounting valuations weigh on statutory net income.

    Attention now turns to the third-quarter earnings release, where sustained adjusted EBITDA and narrowing bottom-line losses will determine whether full-year operational targets stay on schedule.

  • Loyalty Management Spending Hits $17.38 Billion as Platform Costs Surge

    Loyalty Management Spending Hits $17.38 Billion as Platform Costs Surge

    Global spending on retail loyalty management tools reached an estimated 17.38 billion dollars this year, up from 5.5 billion dollars in 2020, even as operational expenses rose by more than 200 percent.

    While frequent shoppers spend 12 to 18 percent more than average store visitors, analysis from Korn Ferry highlights mounting fatigue as retailers face steep technology costs that complicate returns on complex app-based reward systems.

    The Rising Cost of Digital Points

    Running a modern loyalty scheme requires substantial capital. Retailers now buy dedicated software stacks, maintain integration with point-of-sale hardware, and pay ongoing fees for automated communication engines. These platform expenses rose more than 200 percent over the past six years. At the same time, consumers face friction from multi-step point activations, short redemption windows, and restrictive product exclusions that dilute the original incentive.

    Korn Ferry data shows that four out of five elite frequent fliers feel unrecognised by their airline programmes, pointing to similar fatigue across retail store chains. Many shoppers treat points programmes as simple commodities or gamify them to extract discounts on third-party products without building direct brand allegiance.

    Loyalty programs have become a mathematical game to maximize revenue that has little to do with loyalty.

    Shifting Value for Regional Operators

    Retailers across the Asia-Pacific region spent the last five years retiring physical stamp cards in favour of proprietary mobile applications. Department stores, pharmacy chains, and beauty retailers added tier structures, automated notifications, and points multipliers to capture granular transaction data. Yet the operational overhead of servicing those digital platforms now squeezes store margins during a period of cautious consumer discretionary spending.

    The strategic risk rests with mid-tier operators who lack the scale to run custom artificial intelligence programmes but carry enterprise software bills. Luxury retailers outperformed broader retail segments by maintaining high-touch store interactions rather than relying strictly on automated tier discounts. Mass-market merchants that rely purely on discounting points risk training customers to shop only on margin-eroding promotions.

    Automation Replaces Personal Touch

    Before the current wave of app consolidation, merchants relied on simple reward systems with immediate redemption. As software vendors expanded loyalty platform capabilities, programmes grew into distinct profit centres, selling customer data and co-branded financial products. This financialisation created multi-layered rulebooks that alienate core customers while customer service desks shifted to automated chatbots.

    Enterprise software budgets for retail marketing stacks will face their next formal audit cycle in the first quarter of 2027, when operators renegotiate multi-year platform contracts against actual member retention rates.

  • Wpay Processes over 1.55 Billion Transactions Annually Across ANZ

    Wpay Processes over 1.55 Billion Transactions Annually Across ANZ

    Australian payment provider Wpay processed over 1.55 billion transactions across Australia and New Zealand in October 2026. Merchants are overhauling disconnected point-of-sale and digital payment networks.

    Enterprise store operators face heavy pressure to link in-store payment terminals with online checkout engines. Software stacks across Australasian retail chains remain fragmented. This setup causes operational friction. Store staff cannot view cross-channel customer histories or process instant returns.

    Rebuilding Cross-Channel Checkout Systems

    Payment architectures across the region remain divided between legacy physical registers and digital gateways. When these systems run on separate databases, customer records fracture. Data splits across store registers, mobile apps, and e-commerce websites.

    Retailers are fixing this split by adopting universal identifiers, including Payment Account Reference codes and payment tokens. These network identifiers track shoppers across physical card taps and in-app transactions. They protect customer privacy by concealing raw card numbers. Operators also link these tokens directly to loyalty programs and gift card balances. That delivers accurate data on basket size and repeat visits.

    This engineering shift changes daily store operations. Integrated systems allow partial and multiple payment captures against a single authorization code. This step prevents payment failures during split shipments and deferred fulfillment orders. Shoppers who buy online can receive immediate terminal refunds in physical stores directly back to their cards. Store staff can also push refunds to original online payment methods.

    Integrating AI Agents into Payment Rails

    Beyond traditional point-of-sale hardware and mobile applications, Australian retail networks are preparing infrastructure for automated agentic commerce. Autonomous artificial intelligence agents are entering consumer markets. These bots search product catalogues, negotiate pricing, and execute transactions directly on behalf of shoppers.

    Non-human buyers demand structural changes to transactional payment architecture. Automated purchasing requires programmable, permissioned authorization protocols and hard spending limits to avoid erroneous transactions. Heavy bot traffic also demands multi-gateway routing engines. Fraud detection must operate at machine speed.

    Modern payment platforms treat automated agents as an integrated retail channel. They direct machine sales through the same settlement, inventory, and reporting databases used by physical cash registers. This safeguards supply chains against double-booking stock. It also prevents errors in daily cash reconciliations.

    Network Resilience and Offline Store Infrastructure

    Store chains in regional Australia and New Zealand face recurring telecommunications disruptions that threaten register uptime. Register downtime leads to lost sales. It also triggers long checkout queues during peak trading periods.

    To keep lanes open, retailers are installing payment terminals equipped with local store-and-forward offline processing alongside automated 4G cellular failover connections. When primary fixed-line connections drop, registers continue logging and clearing card taps locally. Normal synchronization resumes once data links restore.

    Back-end reporting tools aggregate physical register receipts and digital gateway feeds into one central balance sheet. This direct integration eliminates the need for manual end-of-day register reconciliation across regional store footprints.

    What Enterprise Retailers Face Next

    The operational divide between single-channel terminals and unified commerce platforms will drive retail technology spending across Australasia through 2027. Retailers that delay system overhauls will struggle to support combined click-and-collect fulfillment, split shipments, and cross-channel loyalty redemption.

    Technology directors now face the task of upgrading legacy enterprise systems without disrupting live checkout lanes. Artificial intelligence buying services are entering digital marketplaces. Store operators will need payment gateways capable of authorizing automated machine transactions while maintaining strict fraud thresholds.

  • Mars Study Projects AI-Driven Retail to Reach 788 Billion Dollars by 2035

    Mars Study Projects AI-Driven Retail to Reach 788 Billion Dollars by 2035

    Automated AI agents will handle everyday consumer purchases over the next decade. At the same time, global retail will shift toward experiential spaces, according to research from Mars, Kantar and Synthesis.

    Researchers analysed more than 180,000 data signals across four continents. The goal was to evaluate how consumer purchasing habits and retail platforms will operate through 2035.

    The report identifies three primary shifts: algorithmic purchasing automation, granular personal curation, and experiential physical and digital storefronts. Intelligent software assistants will handle recurring household restocking. As a result, physical shops must transform from functional transaction points into entertainment and community destinations.

    Automated repeat purchases and agentic commerce

    Software agents now manage routine consumer replenishment without manual order placement. They process purchase histories, individual preferences and live inventory levels in real time. Artificial intelligence referrals to e-commerce brands jumped 752 per cent year on year during the 2025 holiday shopping season, according to data from BrightEdge. The firm projects that AI-driven commerce transactions will expand to $788 billion globally by 2035.

    This dynamic splits retail into two separate tracks. Basic household necessities and staple groceries move into frictionless background fulfilment. Meanwhile, discretionary shopping becomes an intentional activity centred on product discovery.

    Balancing personal curation with data governance

    Consumer expectations for customised digital interactions continue to climb across retail categories. Research from TransUnion shows that 39 per cent of consumers now expect personalised online shopping experiences.

    Tailored product recommendations require retail platforms to process deeper customer data streams. That requirement raises compliance demands around customer consent, data storage and cross-border consumer protection standards across international operating territories.

    Physical stores pivot to entertainment

    Physical stores and digital platforms are responding to automated replenishment by turning shopping trips into sensory destinations. Experiential brand venues recorded 15.3 per cent year on year growth, according to tracking data from Emarketer.

    Online channels follow a similar path toward active engagement. Emarketer figures show that 22 per cent of United States digital buyers already purchase products directly through livestream broadcasts.

    Snacking brands confront disappearing impulse buys

    Background replenishment threatens traditional impulse-driven consumer packaged goods categories. Packaged food manufacturers built their distribution models around checkout aisles, end-cap displays and point-of-sale visibility in convenience stores and supermarkets. When automated algorithms reorder groceries based on historical basket data, unprompted impulse sales drop sharply.

    Brand owners now need direct interactive touchpoints to introduce new items before algorithms lock shoppers into rigid consumption loops. Regional supermarket operators must redesign floor layouts away from dense shelving and toward dedicated sampling zones and interactive kiosks.

    Retail chains started testing automated inventory reordering and cashierless checkout networks in late 2025. Consumer packaged goods manufacturers now face the 2026 holiday retail cycle as the next test of whether interactive digital activations can defend impulse purchase volumes against automated buying agents.