Tag: E-Commerce

  • Sixty-One per Cent of Shoppers Use AI for Grocery Decisions, EY Finds

    Sixty-One per Cent of Shoppers Use AI for Grocery Decisions, EY Finds

    Sixty-one per cent of respondents have used artificial intelligence to help make grocery decisions, according to a report released by EY in September 2026.

    The study, titled What Happens When Shoppers No Longer Do the Shopping?, found that almost half of surveyed consumers would likely use a tool that reliably sourced their usual basket across several supermarkets, though only 17 per cent were very likely to do so.

    Richard Rome, associate director for consumer industry at EY, examined whether shoppers would allow an AI assistant to plan, compare and purchase groceries, noting that the shift represents a more human-centric model with less human touch rather than humanless shopping.

    What Drives Automated Basket Decisions

    Cost reduction remains the main hurdle before consumers surrender control of their shopping carts. EY found that 40 per cent of respondents demand clear financial savings on their total grocery bill before delegating purchases to an automated system.

    Time savings offer a faster route to practical adoption. Fifty-eight per cent of shoppers said they would hand over an online order if software saved them up to 30 minutes a week, while 47 per cent would do so for trips to physical stores. Another 25 per cent pointed to practical assistance with dietary rules, label verification, health goals and ethical sourcing as sufficient incentive to use automated tools.

    Families Lead Early Adoption Rates

    Younger households with children show the highest appetite for delegating routine shopping chores. In the EY data, 70 per cent of families with children under 18 ranked as potential early adopters, followed closely by consumers aged between 18 and 34, full-time workers and higher-income earners.

    The concentration among busy households points to an immediate opportunity for automated replenishment tools. Consumers with packed schedules want to eliminate the mental friction of tracking household staples, checking ingredient lists and comparing pack sizes across multiple store apps.

    Why Supermarkets Face Platform Risk

    Retail incumbents such as Woolworths and Coles face a structural shift if third-party software takes over product discovery. When an independent algorithm chooses brands based on unit price or nutritional parameters, traditional investments in eye-level shelf placement, endcap displays and on-site search advertising lose their pull.

    Trust in automated shopping requires tools to remain entirely neutral between competing retail chains. Software created by a single supermarket chain restricts the selection pool, opening the door for price comparison portals, payment platforms, meal planners and standalone AI applications to capture the customer relationship instead.

    How Suppliers Must Structure Product Data

    Packaged goods manufacturers now need clean, machine-readable specifications to ensure autonomous agents select their items. If an algorithm filters out products lacking explicit dietary tags, standardized ingredient data or clear unit pricing, those products drop out of the basket before a human ever sees them.

    The research builds on earlier consumer shifts across Asia-Pacific toward algorithmic grocery planning and quick-commerce meal kits. Richard Rome, associate director for consumer industry at EY, will present detailed data from the report during an Australian Food & Grocery Council webinar on October 28.
  • Amazon Rolls Out Agentic AI Service for Third-Party Sellers

    Amazon Rolls Out Agentic AI Service for Third-Party Sellers

    Amazon on Wednesday, September 25, 2026, introduced a new agentic artificial intelligence service for third-party sellers on its main e-commerce site, expanding automation for listing and inventory management.

    The service performs multiple actions with little to no human intervention and is free and optional for any seller to use, according to Amazon vice president Mary Beth Westmoreland.

    How the autonomous workflows operate

    Known as “workflows,” the system runs continuously through the Seller Assistant platform to carry out prompts such as alerting sellers if ratings drop, monitoring product pricing, and connecting to Anthropic’s Claude and Amazon’s Quick.

    Amazon built the capability into its Seller Assistant platform. The system stores merchant profiles to generate recommendations for discount schedules, promotions, and reorders.

    Integration with external models

    Plug-ins connect the service directly to third-party artificial intelligence platforms. The initial rollout supports connections to Amazon Quick and Anthropic’s Claude models.

    Mary Beth Westmoreland, vice president of worldwide selling experience at Amazon, said the agentic tool is free and optional for registered merchants. Sellers also control the volume of operational and personal account data shared with the system.

    Shift toward autonomous seller operations

    Platforms across Asia and Western markets already use generative tools for copywriting. Agentic systems shift the focus to operational execution. Cross-border sellers managing thousands of stock keeping units across multiple time zones can modify listings without waiting for staff review.

    Risks center on algorithmic errors and sudden price wars. Margin compression can accelerate across crowded product categories when thousands of automated agents adjust pricing at the same time.

    Platform automation timeline

    Over the past two years, platform automation has expanded from listing summaries to predictive warehouse inventory placement. Multi-step software agents represent the next stage in reducing support overhead.

    Adoption rates across North America, Europe, and Asia-Pacific regional hubs will determine whether Amazon expands plug-in access to more external AI models later this year.

  • Amazon Blocks Meta Shopping Bot as Agentic E-Commerce Hits $7.7 Billion

    Amazon Blocks Meta Shopping Bot as Agentic E-Commerce Hits $7.7 Billion

    Amazon has blocked Meta’s artificial intelligence agent Muse from its storefront. A platform battle is brewing as agentic e-commerce transactions reach 7.7 billion dollars globally in 2026.

    The dispute centers on unauthorized bot browsing, privacy safeguards, and proprietary customer access. Autonomous tools are starting to execute purchases without direct human navigation.

    Bot Access Battles at the Storefront

    Amazon stated that Muse entered its retail site without clearance, triggering security and privacy protocols. Meta disputed parts of the claim. It wants open access so Muse can compare listings and complete purchases directly for users.

    This conflict extends beyond simple web scraping. Retailers must now deal with autonomous agents that parse catalog data, evaluate pricing, and place binding orders within milliseconds. The shift turns digital storefronts from consumer destinations into backend suppliers for third-party software.

    To protect its ecosystem, Amazon deployed AgentCore Web Bot Auth. The system uses cryptographic verification to evaluate incoming bots and enforce merchant access rules. Simultaneously, the Fast Identity Online alliance began drafting authentication standards to govern automated purchasing agents across retail domains.

    India Prepares Infrastructure for Automated Orders

    In India, the operator of the Unified Payments Interface is developing protocols to clear AI agents for independent payment execution. This blueprint will govern automated consumer spending across domestic retail networks.

    Domestic platforms including Flipkart, Reliance, Meesho, and Myntra face immediate commercial exposure. When autonomous agents replace human shoppers, traditional revenue drivers lose impact. Search ads, sponsored placements, and banner promotions suddenly carry less weight.

    Market power shifts toward the entities controlling the primary agent interface. If a few dominant models decide which merchants surface during an automated query, regional sellers risk losing direct relationships with shoppers. Their only defense may be launching proprietary purchasing bots of their own.

    Legal Precedents and Security Thresholds

    Cyber boundaries around retail data access remain contested in court. In August, a United States appeals court lifted a preliminary injunction that had restricted search startup Perplexity from deploying agentic browsing across Amazon’s catalog. The broader legal dispute remains unresolved.

    Platform operators now face a dual risk. Allowing unrestricted bots creates cybersecurity vulnerabilities and inventory distortion. Conversely, erecting restrictive technical firewalls reduces merchant visibility across emerging consumer search platforms.

    Attention now shifts to whether the UPI automated payment framework establishes workable compliance benchmarks before major marketplaces implement universal bot blocks across South Asia.

  • Lazada Maps Carbon Footprint and Claims 1.1 Million Ecosystem Roles

    Lazada Maps Carbon Footprint and Claims 1.1 Million Ecosystem Roles

    Lazada Group logged 1.1 million economic roles across its Southeast Asian e-commerce network. The tally appeared in its inaugural sustainability report alongside its first operational greenhouse gas baseline.

    This benchmark inventory covers operations in Indonesia, Malaysia, the Philippines, Singapore, Thailand and Vietnam. It forms the foundation for a wider decarbonization plan.

    Carbon accounting and logistics operations

    Prepared against the Global Reporting Initiative Standards 2021, the FY2022 review details the group’s first group-wide carbon inventory. The baseline identifies primary emission sources across fulfillment hubs and transport networks. That data will help steer fleet contracts toward third-party logistics operators using electric vehicles.

    Packaging reduction programs ran alongside the emissions audit. In the Philippines, the LazGoGreen initiative recorded sales of 70,000 alternative material pouches in March 2020. Thirty-five sellers switched entirely away from conventional plastics. By the end of that year, 18 national plastic collection hubs were operational.

    Merchant enforcement and counterfeit screening

    On compliance, a dedicated Intellectual Property Rights team introduced automated detection tools in March 2020. That system removed 98 percent of flagged counterfeit listings in 2021 before shoppers completed a transaction.

    Information security across the six regional markets secured certification under the ISO 27001:2013 standard. Local business units also ran joint consumer data protection campaigns with state agencies. Partners included the Department of Trade and Industry and the National Privacy Commission in Manila.

    Workforce programs and regional read-across

    Merchant training ran through Lazada University alongside the Lazada Learning Festival 2022 for small businesses. Separately, a specialized technical scholarship with For The Women placed 70 percent of its female data science graduates into formal technology positions.

    Emissions tracking gives institutional investors standard data points, but implementation across independent fleets remains uneven. Company-owned sorting centers can enforce strict packing rules. Even so, tens of thousands of third-party merchants still use standard plastic mailers because sustainable alternatives cost more per unit.

    Rival platforms face identical packaging friction across Southeast Asia. Low average order values make merchants resistant to packaging surcharges. Marketplaces that mandate compliance without absorbing packaging overhead risk driving small vendors toward competing platforms.

    Corporate footprint across Southeast Asia

    Founded in 2012, Lazada became the Southeast Asian flagship platform for Alibaba Group in 2016. Over the following decade, the marketplace built proprietary logistics and payments infrastructure across six core territories. It now runs localized operations in each market.

    Operations across the region are geared toward a target of serving 300 million consumers by 2030.

  • Shein Net Profit Drops 67 Percent to 228 Million Dollars as Air Freight Squeezes Margins

    Shein Net Profit Drops 67 Percent to 228 Million Dollars as Air Freight Squeezes Margins

    Shein reported a 66.6 per cent slump in second-quarter adjusted net profit to $228 million, hit by surging air cargo rates and falling revenue in Western markets.

    Net profit margins narrowed to 2.1 per cent from 6.2 per cent a year earlier, even as the platform fulfilled 298 million orders between April and June.

    Group revenue inched up 0.9 per cent year-on-year to $11.08 billion during the period. Active customers climbed to 291 million over the 12 months to June, up from 254 million, but shoppers spent less per order while overhead surged.

    Higher shipping costs hit the bottom line

    Fulfillment costs surged 18.1 per cent during the three-month period. Shein relies on direct air shipments from contract factories in southern China to consumers worldwide, leaving operating margins exposed to sudden swings in aviation fuel and commercial cargo pricing caused by Middle East route disruptions.

    Growth in Latin America compensated for contractions in primary markets, preventing top-line sales from shrinking outright. Total order volume increased by 21 million transactions compared with the second quarter of last year.

    Tariffs and parcel fees bite in the West

    Revenue from Europe fell 13.9 per cent to $3.77 billion as Shein pulled back on digital marketing spend and lifted retail prices ahead of regional regulatory changes. The European Union introduced a flat 3-euro customs fee on low-value e-commerce packages on July 1.

    United States revenue declined 6 per cent to $2.5 billion. Price adjustments followed the removal of de minimis duty exemptions by US authorities, which had previously allowed parcels valued under $800 to enter the country free of import tariffs.

    Warehouses and premium labels

    Cross-border operators in Asia now face the end of the frictionless air-freight model that built ultra-fast fashion. Temu and AliExpress face identical regulatory scrutiny in Brussels and Washington, but Shein carries heavier direct inventory risk as it attempts to reposition itself toward higher-priced apparel categories.

    Shifting higher up the price ladder creates direct competition with established European apparel chains such as Inditex and H&M without guaranteeing the same local store network or brand equity. Shein must absorb heavy fixed property costs across Europe while defending its low-cost apparel base against newer discount apps.

    Hong Kong stock slides

    The company listed in Hong Kong on September 1 at an offer price of HK$48.56 per share. Trading has dropped 27.3 per cent since the debut, reflecting investor concern over margin erosion and sluggish Western revenue.

    To reduce dependence on individual air parcels, the group is expanding land-based logistics hubs inside the European Union. Shein opened a 740,000-square-metre distribution facility in Wroclaw, Poland, in December and leased an additional 66,000 square metres of warehouse space from industrial developer CTP earlier this year.

    Investors now await third-quarter earnings figures in November, which will show the full impact of the European Union’s 3-euro parcel surcharge during the peak autumn trading period.

  • DHL Express Names Julian Neo Managing Director for Hong Kong and Macau

    DHL Express Names Julian Neo Managing Director for Hong Kong and Macau

    DHL Express appointed Julian Neo as managing director for Hong Kong and Macau on October 1. He brings 25 years of company experience to the regional role.

    Neo led operations across Malaysia and Brunei from 2019. Over that period, he delivered consecutive gains in revenue and operating earnings.

    His career across the logistics group spans commercial, sales and regional management roles in Singapore, Malaysia and the wider Asia-Pacific territory. Before running the Malaysian unit, Neo served as vice president for global multinational customers across the region. He succeeds Andy Chiang.

    Leadership change in Hong Kong and Macau

    Neo takes on the role with extensive commercial experience in Southeast Asia. Hong Kong serves as a primary air express gateway for the Pearl River Delta manufacturing region, handling high-value tech components, cross-border e-commerce parcels and time-critical trade documentation.

    Annual price adjustment from January 1, 2027

    DHL Express will raise average shipping rates in Hong Kong and Macau by 4.9 per cent on January 1, 2027. According to the company, it adjusts its prices annually to account for inflationary pressures, currency fluctuations and industry-specific cost developments.

    Investment in air freight capacity and security

    DHL Express has completed deliveries for its global order of 28 Boeing 777 dedicated freighters. The aircraft add long-range capacity while reducing fuel burn per ton-kilometer.

    The company also surpassed 500 Transported Asset Protection Association (TAPA) certified sites globally in 2026 and expanded deployment of its MyExpress cross-border shipping platform.

  • Chinese Visitors Spent A$11.2 Billion in Australia as Brands Shift to RedNote

    Chinese Visitors Spent A$11.2 Billion in Australia as Brands Shift to RedNote

    Retailers and tourism operators across Australia and New Zealand are shifting digital marketing budgets to Chinese lifestyle platform Xiaohongshu, known internationally as RedNote, according to Jeffrey Hau, CEO of digital marketing agency Prizm Group.

    Chinese travelers spent A$11.2 billion in Australia in 2025, up 39 per cent year on year, cementing China as the country’s second-largest inbound tourism market, according to data from Tourism Research Australia.

    Search Behavior Replaces Social Broadcasting

    Unlike Western platforms such as Instagram or TikTok where visual polish and direct checkout links drive engagement, Xiaohongshu operates primarily as a recommendation search engine. Users rely on user-generated reviews, detailed itineraries, and sizing guides to make purchase decisions before visiting stores or booking attractions.

    This dynamic shifts the marketing model from broad awareness campaigns to answering specific consumer queries. In Australia, more than 730,000 residents were born in mainland China, according to the Australian Bureau of Statistics. 24 per cent of Chinese arrivals enter on student visas compared to 7 per cent across all international markets, creating multi-year domestic spending cycles across retail, groceries, telecommunications, and housing.

    Tourism Campaigns Drive Measurable Search Volume

    Destination marketing boards have already tested the platform at scale. Tourism New Zealand ran dedicated campaigns on the network that generated more than 500 million impressions and drove a 127 per cent increase in searches for New Zealand travel guides.

    Commercial operators are tracking similar conversion patterns. BridgeClimb Sydney structured its campaigns around Mandarin-language climb options, family packages, and photography pricing, fielding direct queries in comment sections and routing prospective climbers directly to official booking channels.

    Localized Creator Networks Alter Campaign Economics

    For sportswear and fashion retailers, influencer pricing and reach metrics operate under different thresholds in Oceania than in East Asia. Retailer JD Sports activated local creators in Australia and New Zealand during Lunar New Year, using tracked promotional codes to connect creator posts directly to online checkouts and physical store traffic.

    Agency data shows a top-tier creator in the Australian market typically commands between 50,000 and 200,000 followers. In mainland China, that follower count represents only a mid-tier account, giving local brands access to influential community voices at lower production costs.

    The Operational Shift for Asia-Pacific Retailers

    Targeting Chinese-speaking consumers through native platforms requires brands to rethink customer support and community management. Comment sections on Xiaohongshu function as customer service desks where users demand immediate answers regarding sizing, inventory availability, and localized payment options such as Alipay and WeChat Pay.

    Brands that treat the network as an image repository fail to generate sales traction. The operational risk lies in resource allocation: businesses must maintain active, Mandarin-literate moderators to convert queries into completed transactions before prospective shoppers look elsewhere.

    Consumer brands across Sydney, Melbourne, and Auckland are now aligning their upcoming seasonal inventory plans with regional travel calendars, targeting the Golden Week and Lunar New Year retail cycles.

  • Shein Second Quarter Profit Plunges 67 per Cent to US$228 Million

    Shein Second Quarter Profit Plunges 67 per Cent to US$228 Million

    Shein posted an adjusted net profit of US$228 million for the second quarter, down 67 per cent from a year earlier. Freight costs surged while sales across Europe fell.

    Net margin shrank to 2.1 per cent from 6.2 per cent a year ago. Flying low-cost parcels directly from Asian factories to consumers worldwide became far more expensive. Total revenue edged up 0.9 per cent to US$11.08 billion for the three months to June 30. Gains in Latin America counterbalanced declining receipts in Western markets.

    European sales dropped 13.9 per cent to US$3.77 billion during the quarter. The retailer raised prices and trimmed marketing budgets across the region ahead of July 1, when the European Union introduced a 3-euro customs charge on low-value parcels. United States revenue declined 6 per cent to US$2.5 billion. That drop continued a slide that began after American authorities ended duty-free treatment under de minimis rules last year.

    Air Freight and Customs Squeeze Margins

    Conflict in the Middle East disrupted aviation routes and pushed up jet fuel prices. That drove an 18.1 per cent increase in quarterly fulfillment costs. Shein’s direct-to-consumer model depends entirely on affordable air cargo capacity out of southern China. When air freight rates spike, the margin on five-dollar apparel vanishes.

    Shares in Hong Kong have fallen 27.3 per cent below their HK$48.56 offer price since the company went public on September 1. Institutional investors had already priced in regulatory scrutiny. Even so, the rapid deterioration in core operating earnings caught market analysts off guard.

    European Warehouses and On-the-Ground Logistics

    Shein is shifting inventory onto European soil to insulate operations from cross-border customs fees and volatile air cargo rates. The group opened a 740,000-square-metre logistics hub in Wroclaw, Poland, in December. It secured an additional 66,000 square metres of Polish warehouse space through developer CTP earlier this year.

    Holding stock locally cuts delivery transit times and skirts per-parcel import tariffs. Yet it also creates lease liabilities and inventory holding risks the platform once avoided. For suppliers in Guangdong province, bulk sea shipments to European distribution centres require longer production planning cycles. That slows down the ultra-fast test-and-reorder batches that built the brand.

    Pivot to Higher Price Points and Brand Acquisitions

    Executive leadership plans to adjust the product catalogue toward higher price tiers to rebuild profitability. Moving beyond ultra-cheap garments requires winning market share from established mid-market apparel groups. It also means managing higher marketing and acquisition costs.

    “As the product mix shifts towards brands at higher price points, the platform’s overall average selling price will rise accordingly,” Shein chief executive and chair Yangtian Xu said in a statement.

    Potential fast-fashion acquisition targets are under review as the company seeks to build a portfolio of distinct labels across different price tiers. Buying regional brands gives the group immediate recognition in overseas territories. It avoids relying purely on paid online advertising to acquire customers.

    Next Steps on Customs and Third Quarter Results

    Second-quarter figures reflect business conditions before the European Union’s 3-euro parcel levy took effect in July. Shein cautioned that the full financial hit could exceed the disruption caused by the end of American de minimis exemptions.

    Investors will watch third-quarter trading updates to see whether European warehouse operations can restore gross margins before the peak year-end holiday shopping rush.

  • JD.com Pushes Past 700 Million Active Shoppers on Repeat Buying

    JD.com Pushes Past 700 Million Active Shoppers on Repeat Buying

    JD.com has passed 700 million annual active customers in China. It is expanding offline stores and after-sales networks to generate repeat business beyond discount promotions.

    During the 2025 11.11 shopping festival, the Beijing-based group lifted shopper numbers by 40 per cent year on year. Order volumes climbed nearly 60 per cent across digital and physical channels.

    Building Out Physical Malls and Services

    Customer retention now relies on in-house procurement, fulfilment, and post-purchase service rather than livestream discounts alone. That operational backbone gave JD.com an edge in high-consideration categories like smartphones, personal computing, and home appliances. In these segments, punctual delivery and installation support drive buyer choices.

    Store expansion through JD Mall sites and electronics outlets now runs alongside new service categories. The group added food delivery, travel bookings, and home repair services to generate daily touchpoints that funnel transactions into core retail channels.

    Targeting High-Value Brand Alliances

    Pitching cross-border trade to international suppliers, the platform is targeting high-retention consumer tiers. Marcia Mao of JingDong Cross-Border spoke at the 2026 UK-China Brand Excellence Summit. She told overseas merchants that sustainable entry requires targeting specific buyer profiles instead of chasing raw traffic.

    This strategy contrasts with rivals using heavy subsidies and flash sales to inflate gross merchandise volume. JD.com gives foreign brands direct control over inventory authenticity and customer service. That protects brand equity while domestic consumer spending stays cautious.

    Running owned warehouses, installation crews, and shopping centres in lower-tier cities carries steep capital costs. Competing discount platforms run asset-light marketplaces with lower take-rates. Those setups give sellers cheaper entry points when consumer demand for general merchandise softens.

    From Scale to Shopping Frequency

    JD.com built its scale by investing billions of yuan in nationwide logistics hubs, promising next-day delivery across hundreds of mainland cities. The network proved essential when domestic e-commerce competition escalated in 2024. The group defended market share by turning reliable service into repeat purchases.

    Chief executive Sandy Xu pointed to user engagement as the main driver for the company’s next stage of growth.

    “We are also seeing encouraging signs from new initiatives, and we believe these emerging opportunities will further position us for long-term, high-quality growth,” Xu said.

    The Next Test for Everyday Consumption

    Management now faces the challenge of converting foot traffic from regional JD Malls into daily online orders across tier-two and tier-three cities.

  • Marketplaces Surpass Specialist Beauty Retailers in Australia as Online Market Nears $2.2B

    Marketplaces Surpass Specialist Beauty Retailers in Australia as Online Market Nears $2.2B

    Marketplaces outpaced Australia’s leading beauty chains online for the first time in late 2025, taking e-commerce sales past the combined total of Mecca, Sephora, Adore Beauty and Chemist Warehouse.

    The shift comes as Australia’s online beauty and personal care market heads toward 47 per cent growth to reach $2.2 billion by 2030, according to Pattern’s State of Beauty & Personal Care in Australian Ecommerce report.

    Amazon Expands Category Grip

    Online marketplaces generated roughly $200 million in Australian beauty sales during the fourth quarter of last year. That total cleared the $199.3 million recorded by Mecca, Sephora, Adore Beauty and Chemist Warehouse combined.

    Amazon drove much of the advance. Its local beauty and personal care turnover rose by $66.7 million year on year, lifting the marketplace operator to a 19.9 per cent share of Australia’s total online beauty spend.

    Shopper intent points to further gains. Pattern found 71 per cent of Australian digital beauty shoppers plan to purchase products on Amazon over the next twelve months, while 43 per cent say they will switch to an alternative brand if their first choice is out of stock.

    Consumers aren’t thinking about a brand’s distribution strategy. They simply expect beauty products to be available through the channels they use, and they’re willing to switch brands for that convenience.

    Fragmented Social Discovery Funnels

    Discovery patterns are pulling shoppers away from traditional storefront browsing. Nearly half of surveyed beauty shoppers reported buying items based on creator recommendations, compared to just 15 per cent across non-beauty retail sectors.

    Instagram and Facebook each shaped purchase intent for 47 per cent of beauty shoppers, followed closely by YouTube and TikTok. Yet discovering an item on social networks rarely results in a direct in-app checkout.

    Instead, 39 per cent of buyers who spot products on social feeds complete their transactions on standalone retailer or brand websites. Another 32 per cent head directly to Amazon to finish the order.

    Algorithmic Search and AI Assistants

    Artificial intelligence assistants are now actively routing consumer purchase paths. The data shows 38 per cent of Australian beauty shoppers use AI tools more frequently than they did last year to search for products online.

    Roughly 27 per cent of consumers have relied on ChatGPT or comparable conversational tools to research or buy cosmetics, and 55 per cent express confidence in AI-generated product advice. Global beauty conglomerates are taking notice: Estée Lauder Companies recently partnered with marketing startup Profound to optimize brand visibility across generative platforms including ChatGPT and Google Gemini.

    What the Shift Means for Specialty Retail

    For dedicated beauty retailers, the loss of market share to general merchandise marketplaces threatens the high-margin basket sizes that have long supported domestic store networks. Department stores and specialty chains can no longer rely on exclusive supplier arrangements to protect digital footfall when marketplace logistics offer faster shipping and lower barriers to checkout.

    Brand owners face an equally sharp operational trade-off. Direct-to-consumer storefronts carry heavier customer-acquisition costs as search engines and social platforms shift toward algorithmic discovery, forcing brands to list on Amazon or risk losing sales to competing formulations.

    The critical metric for retailers heading into 2027 will be whether specialist chains can defend their remaining 80 per cent market share as marketplace volume accelerates toward the $2.2 billion category ceiling.

  • Guinness Launches Zero Alcohol Stout in Singapore Across Retail and on Trade Channels

    Guinness Launches Zero Alcohol Stout in Singapore Across Retail and on Trade Channels

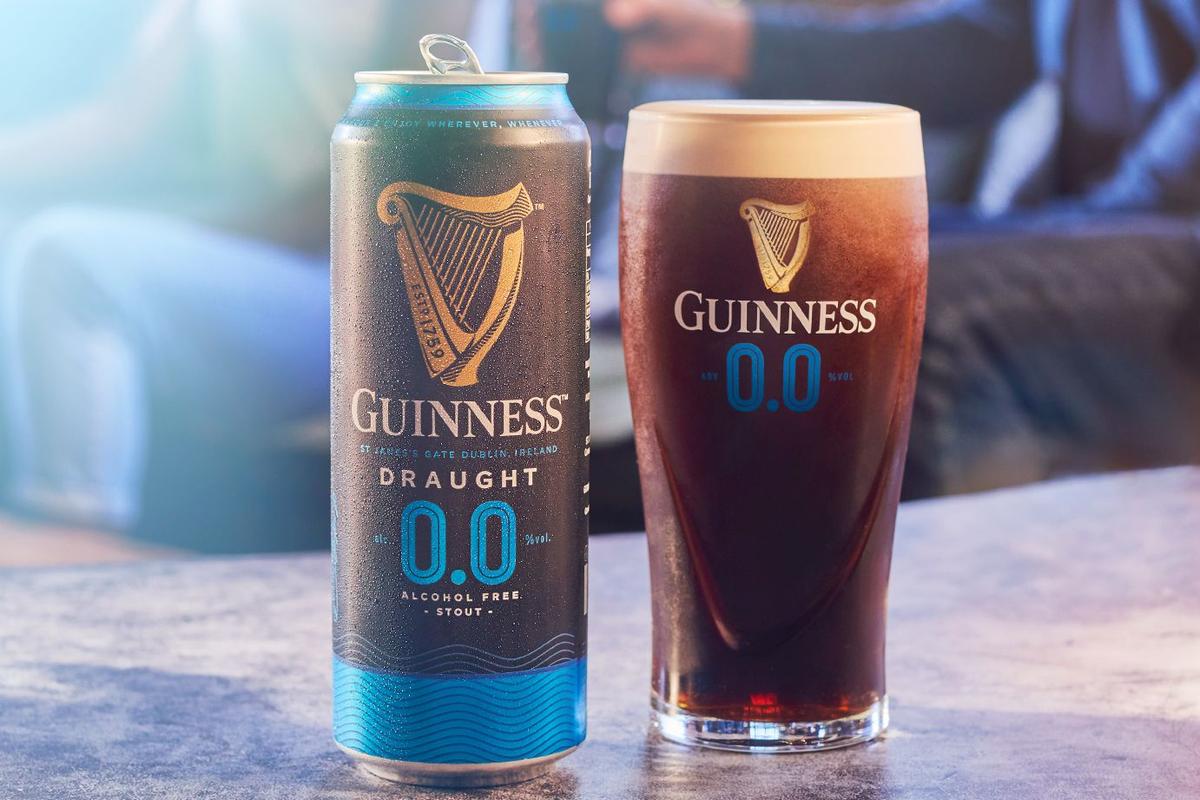
    Diageo will roll out Guinness 0.0 across Singapore on October 26, 2026. The debut introduces the non-alcoholic stout to Southeast Asia for the first time.

    Distribution covers on-trade venues, grocery chains and online merchants across the island. The rollout expands an alcohol-free lineup that previously reached 12 international markets.

    Shelf space and supply lines

    Supermarket distribution covers selected outlets of FairPrice Finest, Cold Storage and Sheng Siong. Online shoppers can order through RedMart, PandaMart and Shopee. Kegs and cans will also pour at participating pubs, bars and restaurants.

    Guinness spent four years developing the zero-alcohol stout at its St James’s Gate brewery in Dublin. Brewers make standard stout first. They then extract the alcohol through cold filtration without heat, preserving the roasted barley profile and creamy head.

    Promotion ties directly into Diageo’s sponsorship as the official beer and non-alcoholic beer of the English Premier League. Guinness also partnered with Singaporean illustrator Tobyato on retail merchandise. Shoppers who spend at least S$55 (US$43) on participating items receive a limited-edition football jersey.

    Shifting beer economics

    On local shelves, Guinness 0.0 joins existing lines including Guinness Draught, Nitrosurge and Foreign Extra Stout. Alcohol-free extensions give grocers and bar operators standard retail margins without alcohol excise duties. That makes shelf space far more profitable.

    Global data from IWSR shows no-alcohol beer volumes across 21 major markets grew 8 percent in 2025. Total beer consumption contracted 1 percent during the same period. Pricing power is shifting upward too, with premium-and-above tiers taking 29 percent of non-alcoholic volumes in 2025, compared to 20 percent in 2019.

    Singapore gives Diageo a dense, high-income test market. If operators sell non-alcoholic draught near standard pint prices, the format generates higher gross margins. It also helps fill slow weekday shifts when alcohol sales dry up.

    Regional track record

    Earlier iterations of non-alcoholic dark beer have tested Southeast Asia before, under different distribution models. Diageo introduced a coffee-formulated Guinness Zero in Indonesia in 2014 to navigate local retail bans on standard beer sales.

    Recent corporate filings show Diageo now sells non-alcoholic brands across 17 countries, as noted in its 2026 annual report. Rival international brewers already run non-alcoholic lager taps across Singapore. Stout remains one of the few open premium categories.

    What to watch next

    Activations and roadshows will run through November to test repeat grocery purchases after the initial merchandise push. Sell-through rates at FairPrice and Cold Storage during late 2026 will determine whether Diageo expands Guinness 0.0 to Malaysia and Thailand in 2027.

  • Global Planner Notebook Market to Grow 3.2 Percent Annually Through 2035

    Global Planner Notebook Market to Grow 3.2 Percent Annually Through 2035

    The global planner notebook market is projected to expand at a compound annual growth rate of 3.2 percent from 2026 to 2035, according to a report published by IndexBox in September 2026.

    Market value growth is set to outpace volume growth over the forecast period as consumers increasingly opt for higher-priced, benefit-led products, lifting the sector index to 137 by 2035 from a base of 100 in 2025.

    Asia-Pacific will remain the largest consumer market globally, supported by population scale and rising disposable incomes, while North America and Europe lead adoption across premium product categories.

    How Price Tiers Split the Retail Shelf

    The global retail landscape has split into two separate operating tracks. On one side sits a high-volume, commoditized mass-market segment dominated by supermarket distribution, back-to-school promotional discounting, and heavy private-label competition. On the other side is a high-margin premium segment where direct-to-consumer digital channels and specialty bookshops sell brand equity, lifestyle aesthetics, and tactile user experiences.

    Mainstream mid-tier brands face the sharpest margin squeeze. Mass merchandisers and drugstores continue to expand their private-label stationery assortments, undercutting standard branded notebooks on price. To defend gross margins, branded manufacturers are moving upmarket into benefit-led products that combine habit tracking, mindfulness prompts, and bullet journaling layouts that private-label lines struggle to replicate.

    North America holds 25 percent of the global market and Europe claims 20 percent, with both regions leading in average selling price. Latin America and the Middle East and Africa each represent 10 percent of worldwide consumption, where demand remains focused in urban centers and reliant on imported inventory.

    Supply Chain Decoupling and Manufacturing Shifts

    Production models have adapted to this bifurcated retail demand. Basic component manufacturing, standard paper milling, and entry-level binding stay concentrated across large-scale industrial bases in Asia, giving mass-market suppliers the scale required for low-cost volume contracts.

    Finishing, custom embossing, and high-spec packaging for premium lines are increasingly localized or handled through regional direct-to-consumer fulfillment hubs. This split allows stationery companies to manage raw material price swings in paper pulp and shipping freight while selling personalization features at substantial retail markups.

    Direct-to-consumer e-commerce acts as the main customer acquisition engine for specialized brands. Instead of relying purely on physical stationery retail, producers use online platforms to sell accessories, page refills, and digital courses alongside physical books, increasing lifetime customer spending and insulating margins from distributor cuts.

    Japanese Makers Set the Standard in Asia

    Stationery brands in Japan, China, and South Korea have built strong domestic followings that now drive export volume into Western markets. Japanese producers such as Hobonichi, Kokuyo, and Muji established early commercial footholds by treating daily planners as cultural staples rather than basic office supplies.

    Hobonichi built a global cult following around its daily techo planners, proving that premium paper quality and functional layout design command high overseas shipping premiums. Western players like Moleskine, Leuchtturm1917, and Erin Condren must now compete directly against Asian precision stationery brands across both physical specialty stores and international e-commerce marketplaces.

    Digital substitution remains the primary operational threat to paper planners, especially among younger demographics who rely on free smartphone calendar applications. Successful stationery makers counter this attrition by positioning paper as a tactile digital detox tool, while introducing hybrid products featuring QR codes, app syncing, and scannable templates.

    Historical Groundwork and Category Benchmarks

    Between 2012 and 2025, stationery manufacturers weathered repeated waves of digital calendar adoption by transitioning away from utilitarian office pads toward lifestyle and personal productivity systems. That commercial pivot established the pricing tiers that now govern the retail trade.

    Corporate procurement has also stabilized around hybrid work arrangements. While enterprise software handles shared team scheduling, corporate gifting and branded desk merchandise continue to provide steady contract volume for high-end notebook makers.

    Category operators are now locking in their product catalogs and channel allocations for the next academic and calendar cycle, with brands watching whether raw paper input costs stabilize before committing to wholesale discount schedules for 2027.

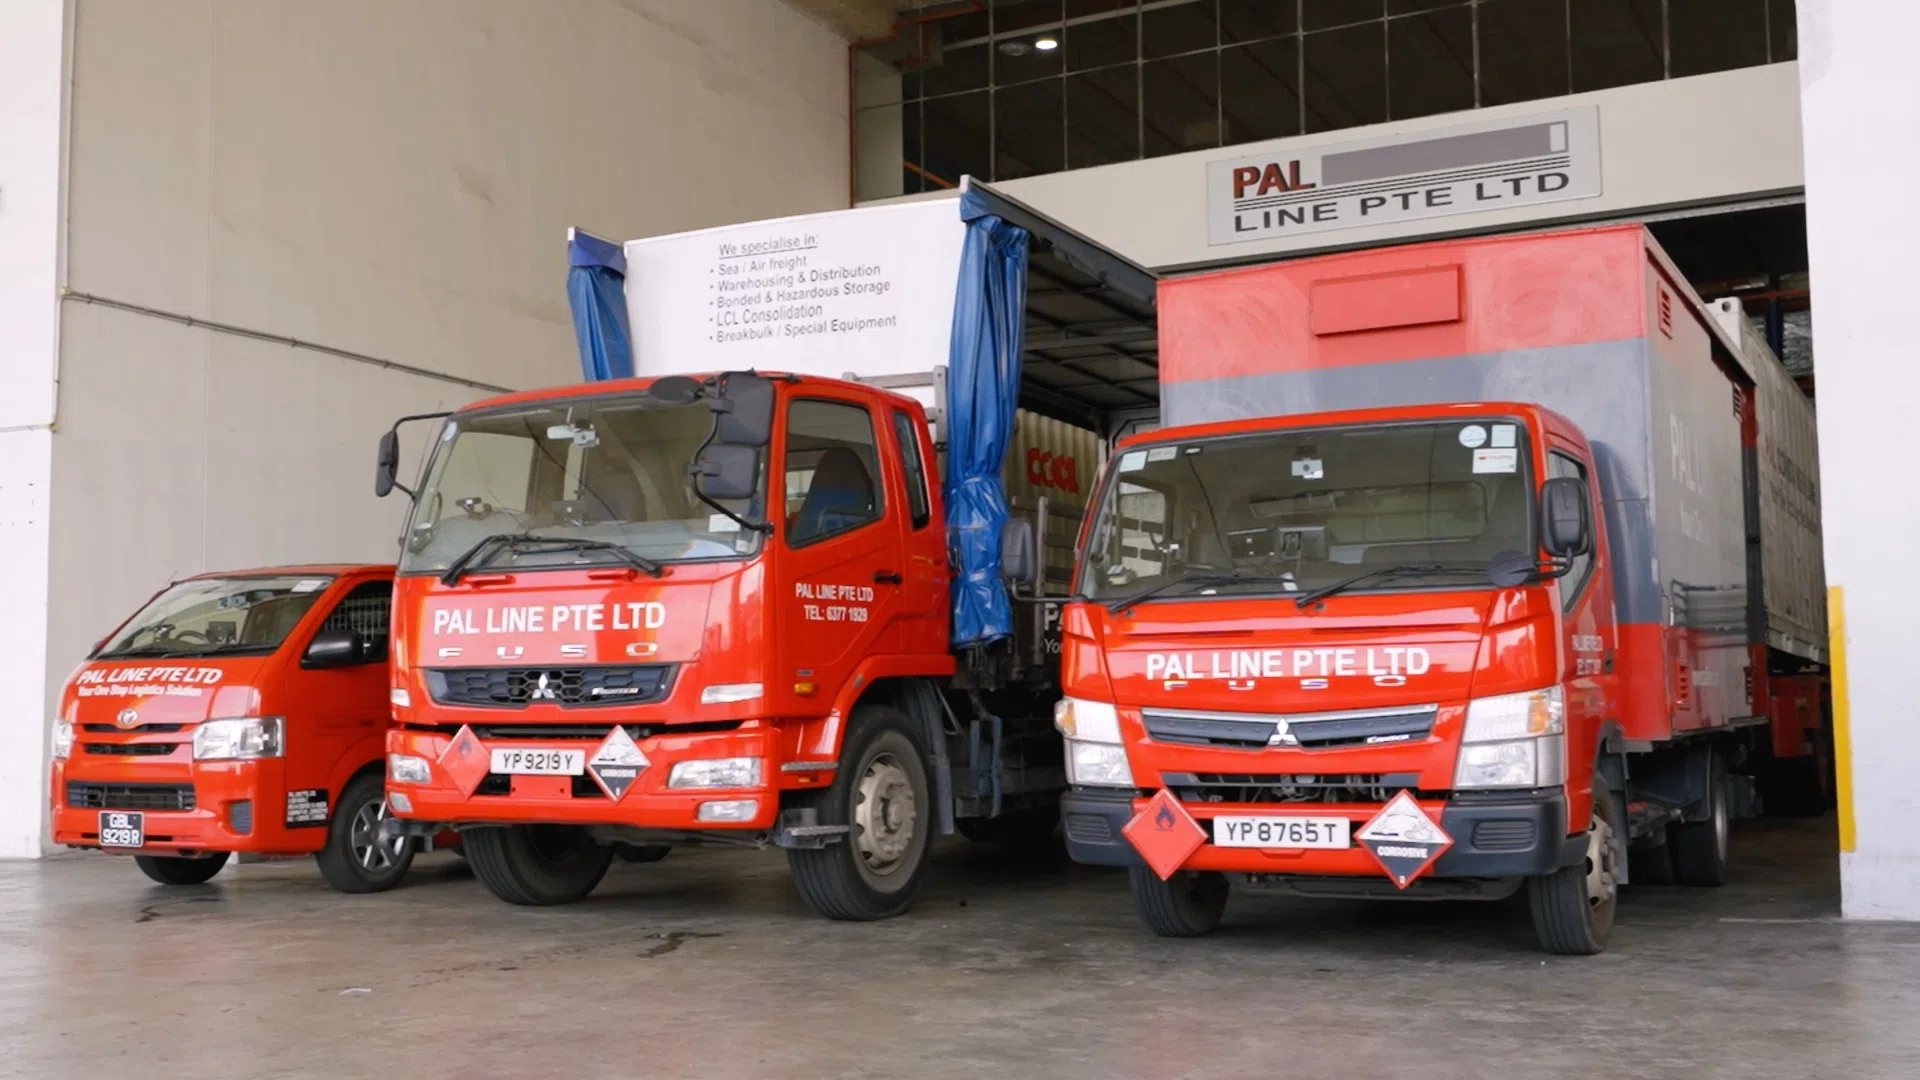
  • Singapore Logistics Group PAL Line Targets 30 per Cent Energy Cut by 2026

    Singapore Logistics Group PAL Line Targets 30 per Cent Energy Cut by 2026

    Singapore freight forwarder PAL Line is converting 70 per cent of its warehouse fleet to electric power while targeting a 30 per cent cut in facility energy use by 2026.

    The company operates across five Asian markets and manages more than 50,000 square feet of climate-controlled warehousing linked to an automated sorting platform for regional e-commerce shipments.

    Automating regional fulfillment

    PAL Line runs warehouse facilities equipped with real-time inventory tracking, climate controls and automated sorting machinery handling cargo from consumer electronics to heavy industrial equipment. The centralized system connects inbound receiving directly to outbound linehaul trucking and freight operations across Southeast Asia.

    Live tracking dashboards feed stock data directly to corporate shippers, allowing inventory managers to alter replenishment schedules while shipments move through the hub. Automated sorting has cut unit handling costs and reduced dispatch errors for cross-border merchants selling into regional markets.

    Electrification and network routing

    Ground operations inside the company’s hubs now rely on electric forklifts for 70 per cent of daily load transfers. Transport routes outside the gates run on GPS telematics designed to cut idling time and lower overall diesel burn.

    Facility retrofits completed since 2021 include low-draw LED systems and recycled packaging standards across all active regional sites. Management aims to lower baseline electricity consumption across its real estate footprint by 10 to 30 per cent before the end of 2026.

    The regional mid-tier squeeze

    Mid-sized logistics operators across Southeast Asia face intense pressure to match the technological scale of global forwarders without matching their capital budgets. By building proprietary digital tracking into mid-sized facilities, regional specialists can retain mid-market retailers that require specialized customs handling and flexible storage without paying tier-one enterprise rates.

    Risk remains concentrated in cross-border execution. Expanding physical routes between Singapore, Thailand, Malaysia, Myanmar and mainland China exposes forwarders to shifting customs enforcement, variable border wait times and uneven road infrastructure that can disrupt automated delivery promises.

    Cross-border footprint since 2008

    PAL Line started as a basic freight forwarding operation in Singapore in 2008 before rolling out customs brokerage, contract logistics and trucking services. Regional expansion began in 2013 with market entries into Malaysia, Thailand, Myanmar and China.

    A major overhaul in 2016 introduced the group’s centralized warehouse management software, shifting the firm from manual forwarding to digital contract logistics. The company secured a place on Singapore’s Enterprise 50 list in 2024 following its cross-border warehouse expansion.

    The key milestone to watch is the delivery of the 2026 warehouse audit, which will measure whether PAL Line meets its 30 per cent energy reduction target across its Southeast Asian facilities.

  • Southeast Asia Savvy Online Shoppers Spend 31% More at $11.5 Billion

    Southeast Asia Savvy Online Shoppers Spend 31% More at $11.5 Billion

    Discerning online buyers in Southeast Asia spend 31 per cent more each month than general consumers. Across six regional economies, they will generate 11.5 billion dollars in annual marketplace sales in 2026.

    A joint study from Lazada and commerce analytics group Cube defines roughly 24 per cent of regional consumers as savvy shoppers. Another 18 per cent sit immediately below that threshold. These buyers demonstrate distinct commercial habits. They cross-check merchandise across channels, inspect merchant credentials, and routinely pay premiums for guaranteed authenticity and transaction safeguards.

    How purchasing behavior splits across markets

    Penetration of these higher-spending consumers varies widely by country. The Philippines leads Southeast Asia with 36 per cent of its online buyers qualifying as savvy. Indonesia follows at 28 per cent and Vietnam at 25 per cent. Thailand registers 22 per cent, while Malaysia records 20 per cent. Singapore sits at the bottom of the regional ranking at 9 per cent.

    Friction points also differ across borders. Shoppers in Malaysia and Vietnam report product verification as their primary hurdle during online purchases. Buyers in Singapore, Indonesia, and the Philippines cite buyer protection and seller confidence as their main challenges. Thai consumers report an even split between verification and security concerns.

    Value replaces pure price discounts

    Shoppers across Southeast Asia show an increased willingness to invest time to secure better transactions. About 43 per cent of surveyed consumers spend extra time searching for improved offers. Another 41 per cent delay purchases to find better timing. Meanwhile, 36 per cent conduct detailed price comparisons before checking out.

    Price concessions lose traction when they compromise trust. Only 14 per cent of consumers say they would sacrifice authenticity indicators for a lower price. Just 13 per cent would forfeit purchase protections to obtain a steeper discount. Among savvy buyers, 47 per cent state they will pay extra fees for certified order protection, compared to 30 per cent among general consumers.

    Discovery moves outside marketplace walls

    Transaction journeys now start well before buyers enter marketplace apps. The study finds that 83 per cent of savvy consumers discover products outside primary marketplace catalogs, compared to 42 per cent of general buyers. 86 per cent consult third-party information channels during purchase evaluation. A full 91 per cent verify seller track records across external web sources.

    Savvy consumers also buy more frequently and spread their spending across competing channels. Some 58 per cent shop online several times each week, compared to 35 per cent of baseline consumers. Mall environments capture 53 per cent of this cohort, compared to 40 per cent for general shoppers. Multi-homing is standard practice. About 82 per cent of savvy shoppers actively use all three major marketplace platforms across the region, against 61 per cent among the general shopper base.

    Commercial demands on digital merchants

    For marketplace merchants and brand principals, the findings demand a recalibration of promotional spending. Pure discounting drives immediate volume. However, higher-value shoppers demand verified supply chains, fast dispute resolution, and consistent branding across external touchpoints before committing their baskets.

    “Southeast Asia’s eCommerce market is no longer defined by whether consumers shop online, but by how confidently and effectively they do so,” said Simon Torring, Co-Founder of Cube.

    Platform operators now face the operational task of retaining these multi-homing consumers as growth shifts from user acquisition to basket optimization. Marketplaces that fail to guarantee authenticity will see the most profitable quartile of regional demand migrate to rival platforms offering tighter brand verification standards.

  • 85 Percent of Consumers Cut Spending After Poor Service, Genesys Finds

    85 Percent of Consumers Cut Spending After Poor Service, Genesys Finds

    A survey by software company Genesys found that 85 percent of consumers globally have either spent less with a brand or stopped buying from it after experiencing poor customer service.

    In the Philippines, a 2025 study by market research and analytics firm Milieu Insight revealed that 55 percent of online shoppers are more likely to buy from sellers who communicate responsively and provide timely updates.

    Top service rankings across retail and hospitality

    Okada Manila, Grand Hyatt Manila and Dior led the overall rankings in the Philippine Daily Inquirer and Statista Philippines’ Best Customer Service 2027 study, which evaluated 306 companies across 78 categories based on more than 90,000 customer assessments.

    Customer recommendation rates drove half of each brand’s overall score. The remaining weight evaluated five touchpoints: system accessibility, customer focus, clear communication, professional competence, and the range of services at checkout and post-purchase resolution.

    The cost of automated service breakdowns

    Automated support systems create retention risks when software fails to track customer history across channels. Twilio research shows 73 percent of Filipino consumers encounter automated systems that lose earlier context.

    Losing that thread carries a direct cost. When bots drop conversational history, 73 percent of affected local shoppers abandon them to find human staff or cancel the purchase. For 4 percent, repeated technical friction prompted an immediate, permanent exit from the brand.

    Operational shifts for Southeast Asian merchants

    Philippine store operators and e-commerce platforms must treat support infrastructure as core merchandise rather than back-office overhead. Merchants who replaced floor staff and help desks with uncalibrated bots face rising cart abandonment.

    Most friction occurs during the handoff between automated triage and live resolution. Front-line human agents remain essential for complex order disputes, returns, and luxury transactions where automated workflows fail.

    Tracking service metrics into 2027

    A divide is widening between premium operators with dedicated channels and discount platforms relying on automated scripts. Tracking retention rates and first-contact resolution speeds will determine which Philippine retail chains hold market share through 2027.