Category: Food

Retail News Asia is committed to providing both local and global retailers with the latest Food and Food & Beverage news throughout the Asian market. This on a daily base.

  • Metcash Boosts Sales 2.8 per Cent but Warns of Food Margin Pressures

    Metcash Boosts Sales 2.8 per Cent but Warns of Food Margin Pressures

    Wholesaling giant Metcash lifted sales by 2.8 per cent in the first 18 weeks of the financial year, excluding tobacco, but warned investors that elevated food inflation could dent profit margins.

    Hardware and tools led the gains with a 6 per cent rise, while wholesale liquor climbed 5.1 per cent over the same period.

    Hardware and Drinks Outpace Core Food

    Core food expanded 2.6 per cent against the previous year, with group chair Peter Birtles noting that cost inflation continues to challenge the company’s bottom line.

    Logistics and retail expenses stayed elevated. Supply lines held stable, however, with no material disruption from Middle East shipping conflicts.

    Birtles told investors that Metcash’s “diversified portfolio, disciplined execution” and independent retail model have supported resilience despite external challenges.

    Cost Pressures Squeeze Independent Grocers

    For independent supermarkets, rising wholesale prices present a direct dilemma. Passing costs to shoppers risks losing market share to dominant chains. Absorbing them erodes thin retail margins.

    Margin pressure shifts the burden onto wholesale inventory. Distributors must lean on categories like trade hardware and commercial tools, where pricing flexibility beats daily grocery staples, to protect profits.

    New Zealand Liquor Exit Nears Completion

    Trading updates follow fiscal 2026 results of higher sales revenue but lower net profit. Warehousing and freight costs weighed on full-year earnings despite steady turnover.

    Metcash is now closing its New Zealand liquor distribution business to simplify operations and protect returns. The wind-down wraps up before the second half of fiscal 2027, reducing total earnings by approximately $2 million.

  • Coles Drops Palantir AI Software Across 840 Australian Supermarkets

    Coles Drops Palantir AI Software Across 840 Australian Supermarkets

    Coles will terminate its software partnership with US technology firm Palantir. The platform will leave more than 840 Australian supermarkets when the three-year contract expires.

    The system processed more than 10 billion rows of operational data. That load covered employee shifts, bakery production schedules and store-level inventory allocations.

    Operational Data and Customer Backlash

    Signed in February 2024, the agreement deployed Palantir’s Foundry operating system and artificial intelligence tools for workforce planning and supply-chain logistics. The supermarket chain confirmed the platform will exit its stores beyond 2027. Public pushback over Palantir’s government surveillance and defence contracts drove the decision.

    Advocacy group GetUp mounted a billboard campaign near hundreds of stores in July, mimicking Coles branding to challenge its privacy practices. Coles rejected claims that shopper data was exposed to external access.

    “The software is deployed within Coles’ own environment and is operated and isolated under Coles controls,” a Coles spokesperson said.

    Supplier Scrutiny and Reputational Risk

    Retailers across the Asia-Pacific region face swift commercial fallout when back-end software vendors carry political or military profiles. Enterprise procurement once rested on technical capability and cost alone. That calculation has changed. Boards must now weigh vendor reputation alongside data isolation protocols.

    Ripping out an enterprise planning platform creates operational friction and heavy switching costs. Replacing tools that coordinate thousands of store rosters and perishable stock orders takes months of procurement, technical integration and staff retraining.

    The Shift in Retail Procurement

    Work began as a standard productivity initiative while grocery chains accelerated automation to curb operating costs. Palantir’s historical ties to intelligence agencies, US immigration enforcement and foreign defence contracts turned routine back-office optimization into an active brand problem.

    A replacement tender and full system migration across the 840 supermarkets must now wrap up before the contract concludes at the end of 2027.

  • Danone Launches YoPro High-Protein Yoghurt in New Zealand

    Danone Launches YoPro High-Protein Yoghurt in New Zealand

    Danone launched its high-protein yoghurt brand YoPro in New Zealand in September 2026. The rollout includes 15g and 20g protein formats manufactured at its Victorian processing site.

    An exclusive distribution deal with Foodstuffs North Island places the brand directly into the cooperative’s supermarket network.

    Protein formats and supply lines

    Standard YoPro pots and pouches contain 15g of protein per serve. The concentrated YoPro Perform line offers 20g per serve. Danone formulated both product tiers without added sugar or artificial sweeteners, targeting gym-goers and convenience shoppers seeking functional dairy.

    Supply ships across the Tasman from Danone’s manufacturing facility in Victoria’s Kiewa Valley. Using this established Australian base allows the dairy group to test New Zealand consumer demand without committing capital expenditure to local processing infrastructure.

    The exclusive grocery route

    The arrangement gives Danone immediate shelf space across high-volume banners including Pak’nSave and New World. For Foodstuffs, exclusive rights to an established Australian brand create a temporary point of difference against rival Woolworths New Zealand.

    Exclusivity deals carry operational trade-offs. Danone cuts its addressable market in half by bypassing Woolworths and South Island stores. That places the entire burden of brand adoption on a single cooperative’s promotional schedule.

    Battle for dairy shelf space

    This launch pits Danone against domestic dairy giants where Fonterra and boutique local processors dominate chilled cabinets. High-protein and low-sugar yoghurt has developed into a reliable growth pocket across Asia-Pacific dairy. It pulls consumers away from standard flavoured yoghurts that carry higher sugar loads.

    Danone spent several years building YoPro into a category leader in Australia before expanding the supply chain eastward. That playbook relies on heavy athletic marketing and high protein-to-calorie ratios to defend premium shelf pricing against private-label alternatives.

    Distribution now shifts to in-store execution across North Island supermarket chillers as Foodstuffs completes category resets for the spring retail cycle.

  • Nearly 200 Coles Shareholders Urge Retailer to Act on Plastics

    Nearly 200 Coles Shareholders Urge Retailer to Act on Plastics

    Nearly 200 Coles shareholders urged the company to break its silence over plastic use in September 2026. The demand follows the supermarket chain’s decision to stop selling Antarctic krill oil supplements.

    Rival Woolworths followed suit days later, ending the sale of krill-derived products across its supermarkets.

    Supermarket Giants Drop Antarctic Krill Lines

    Coles confirmed the product exit after conservation group Sea Shepherd spotted several unavailable krill oil items on the grocer’s website. Woolworths then ended all krill supplement sales in its own stores.

    The simultaneous delisting strips high-margin marine dietary lines from both chains. Environmental groups have long scrutinised Antarctic krill harvesting for disrupting Southern Ocean food webs.

    Shareholders Target Packaging Policies

    Investors are now pressing Coles management to address packaging waste and match Woolworths’ commitments. The shareholder group wants firm disclosures on plastic volume metrics alongside specific reduction milestones.

    Coordinated pressure on both supermarket operators accelerates packaging redesign deadlines for regional brand and private-label suppliers. Those unable to cut secondary plastics or adopt circular materials face delisting risks.

    Sourcing Audits Across Australian Aisles

    The sudden krill exit shows how quickly activist campaigns alter Australian retail range planning. RetailNews Asia has tracked similar rapid category exits across fresh produce, seafood and packaging formats in recent trading periods.

    Coles faces its next test when investors look for binding packaging targets and plastic reduction timelines at the upcoming formal shareholder meeting.

  • Starbucks Opens Vietnam’s First Signing Store in Ho Chi Minh City

    Starbucks Opens Vietnam’s First Signing Store in Ho Chi Minh City

    Starbucks opened its first Signing Store in Vietnam on Ho Chi Minh City’s Cao Thang Street on Wednesday, expanding a regional format that already runs 26 outlets across four other Asian markets.

    Deaf staff work alongside hearing employees across counter service and daily operations, using visual menus, gestures and written order systems rather than spoken prompts.

    Operations on Cao Thang Street

    The unit sits set back from the main roadway on Cao Thang Street with a garden-style layout planned to lower ambient street noise for staff and guests. It serves the chain’s standard beverage and food menu while changing the service counter workflow to accommodate point-and-sign ordering.

    Chi Nguyen, director of external affairs at Starbucks Vietnam, stated to local media that the location functions as an inclusive space where staff and visitors interact directly through visual methods.

    Format Expansion Across Asia

    Specialised format stores of this type allow multinational food and beverage operators to test altered counter workflows without changing back-of-house supply chains. Starbucks established its first signing outlet in Kuala Lumpur in 2016 before expanding the concept to China, Japan and South Korea, where dedicated customer communication tools were integrated into standard point-of-sale setups.

    For commercial landlords, quiet and garden-style layouts of this type offer ways to activate secondary street frontage and deeper, non-standard retail floorplates that struggle to accommodate high-turnover drive-throughs or standard counter lines. The operational friction sits in staff onboarding and maintaining service speed during peak morning trade, where non-verbal communication systems must process complex drink customisations without causing counter bottlenecks.

    Market Positioning in Vietnam

    Starbucks opened its initial location in Ho Chi Minh City in 2013 and has spent more than a decade building a store network across major commercial hubs including Hanoi, Da Nang and Binh Duong. The brand competes against established domestic chains such as Highlands Coffee and Phuc Long, which operate larger branch networks at lower price points across Vietnam’s urban centres.

    The Cao Thang unit brings the company’s regional signing store count to 27 locations across Asia, with operators watching whether the model will be adapted for additional high-density retail districts in Hanoi.

  • Mixue Shifts Malaysia Strategy Toward Food Safety and Quality Control

    Mixue Shifts Malaysia Strategy Toward Food Safety and Quality Control

    Mixue has shifted its operational focus in Malaysia to food safety and standardized store management this quarter. It has slowed its rapid store openings to protect franchise consistency.

    The value-priced ice cream and tea operator is standardizing ingredient handling, audits, and franchise training across hundreds of independently run franchised outlets in the country.

    Standardising Store Operations

    Headquarters teams are rolling out stricter supplier checks, central storage compliance, and mandatory staff retraining. The goal is curbing hygiene inconsistencies across high-volume suburban counters.

    For franchisees, the tightened rules raise daily discipline and audit frequencies. Store managers face unannounced inspections covering temperature logs, equipment sanitization, and ingredient shelf-life tracking.

    Pressure on Value Tea Rivals

    Rival low-cost bubble tea chains in Malaysia now face immediate pressure. Many compete on single-digit ringgit price points. Churning out high volumes at discount prices leaves little room for error in cold chain logistics or store sanitation.

    Protecting customer trust before hygiene lapses damage the brand drives the compliance push. The main risk sits behind the counter. Enforcing uniform standards across hundreds of independently run franchised outlets demands continuous oversight costs.

    Next Phase of Southeast Asian Expansion

    Mixue entered Southeast Asia aggressively, relying on low franchise fees and an integrated Chinese supply chain to blanket Indonesia, Vietnam, and Malaysia. Rapid expansion quickly secured brand recognition across shopping malls and commercial shop lots.

    Maintaining product consistency across thousands of regional outlets poses a major challenge as local health authorities step up inspections of quick-service beverage chains.

    Malaysian franchisees will complete updated audit cycles over the coming quarter as headquarters evaluates network compliance across Peninsular Malaysia.

  • Funday Natural Sweets and Cotton on Kids Partner on Apparel Range

    Funday Natural Sweets and Cotton on Kids Partner on Apparel Range

    Confectionery brand Funday Natural Sweets has partnered with Australian childrenswear retailer Cotton On Kids in September 2026 to launch a limited-edition apparel collection based on its core product range.

    The apparel run is designed for children aged two to 10 years and sells exclusively through the Cotton On website. Graphic designs across the garments replicate four confectionery variants: Strawberry & Cream, Sour Peach Hearts, Sour Cola, and Fruity Koalas.

    Candy Graphics for Digital Shelves

    Cotton On is keeping the release confined to its online channels rather than distributing inventory across its physical store fleet. Digital exclusivity lowers supply chain overhead for short-run collaborative merchandise while testing customer demand before committing floor space in suburban shopping centres.

    For Funday, the partnership puts grocery-aisle branding into everyday childrenswear. Apparel licensing gives fast-moving consumer goods makers repeated household visibility without requiring an increase in trade marketing expenditure inside supermarkets.

    Brand Collaborations in Childrenswear

    Fashion retailers across Asia-Pacific continue to use branded novelty drops to drive direct web traffic. Cross-category partnerships between food brands and apparel chains have expanded rapidly as fast-fashion operators look for distinctive graphic intellectual property that appeals directly to parents buying for young children.

    The operational risk in food-to-fashion licensing sits squarely on inventory velocity. Themed capsule collections lose consumer appeal quickly once seasonal promotional cycles end, making web-only fulfillment a calculated choice to prevent discounted stock overhang in physical stores.

    Licensing Growth in Apparel

    Cotton On has built a steady business model around limited licensing deals across its adult and youth divisions, drawing on entertainment properties, beverage brands, and food labels to refresh basic garment blanks.

    Online performance data from this initial confectionery run will determine whether Cotton On expands the licensed grocery range into retail stores across Australia and its broader Asia-Pacific store network.

  • China’s Meiyijia Opens Two Ohmee Stores at Petrolimex Stations in Hanoi

    China’s Meiyijia Opens Two Ohmee Stores at Petrolimex Stations in Hanoi

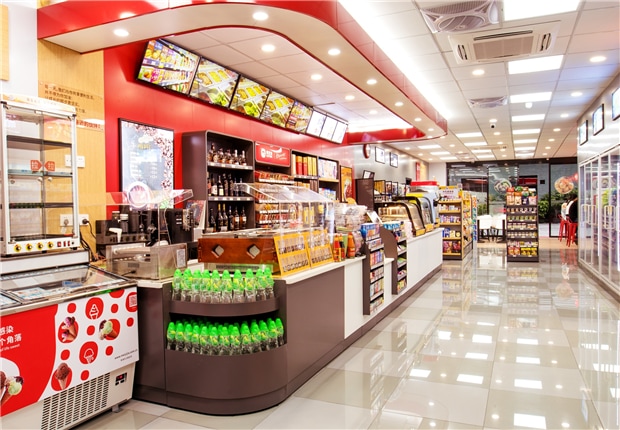
    Chinese convenience chain Meiyijia has opened two Ohmee Express stores at Petrolimex petrol stations in Hanoi following its entry into Vietnam in April. The pilot tests a forecourt retail model in the chain’s first overseas market.

    The tie-up links China’s largest convenience operator with Vietnam’s dominant petroleum distributor. Meiyijia runs more than 40,000 stores in its domestic market.

    Pilot Sites on Hanoi Arteries

    Both outlets operate on Ngoc Hoi and Nguyen Quy Duc streets in Hanoi. They stock packaged food, drinks and daily necessities alongside standard fuel station services.

    Petrolimex deputy general director Nguyen Ngoc Tu said the partnership supports plans to convert traditional petrol stations into multi-service commercial hubs. The strategy responds to shifts in vehicle energy use and digital payments.

    Fuel Forecourt Competition in Vietnam

    Forecourt retailing gives convenience operators a direct way to bypass street-level real estate bottlenecks in Southeast Asia. Securing prime roadside retail space in Hanoi and Ho Chi Minh City carries steep rents and heavy competition from players like Circle K, WinMart+ and GS25. Partnering with a state-backed fuel network gives Meiyijia immediate roadside access and built-in vehicle traffic without negotiating individual retail leases.

    Customer conversion presents the main operational challenge. Petrol buyers in Vietnam make brief refuelling stops on motorbikes. Basket sizes stay modest unless the forecourt store offers quick food service or payment utilities that draw riders off their bikes.

    Cross-Border Expansion from Guangdong

    Meiyijia entered Vietnam in April under the Ohmee banner, selecting the country for its first international expansion. Founded in Guangdong in 1997, the company built its domestic network on a low-cost franchise model. It penetrated lower-tier Chinese cities before expanding into higher-density urban centres.

    Results from the two Hanoi pilot stores will determine whether Meiyijia and Petrolimex roll out the Ohmee Express format across the fuel distributor’s nationwide network of filling stations.

  • Ice Cream and Food Drive 45 Percent Surge in Philippine Convenience Store Sales

    Ice Cream and Food Drive 45 Percent Surge in Philippine Convenience Store Sales

    Philippine convenience store sales jumped 45 percent year on year in January, propelled by heavy consumer spending on food and packaged goods, according to Kantar Worldpanel data.

    Food purchases accounted for 59.3 percent of all fast-moving consumer goods transactions across the format, up from 58.8 percent in the previous year.

    Ice cream retained the top spot among individual product categories, followed by milk, packaged snacks, and alcoholic beverages. Beverages accounted for 23.8 percent of overall basket value, dipping from 25.6 percent in 2014. Personal care items captured 13.5 percent of sales, marking the largest category share expansion with a 2.2 percentage point gain. Household care products took a 4.3 percent share, up from 3.5 percent.

    Shifting Baskets and Fast Growth

    Consumer baskets also showed new priorities during the tracking period. Diapers, bottled water, and fabric cleaners entered the top ten bestselling categories by sales value, while coffee and hair care products dropped out of the list. Diapers climbed straight into fifth place, sitting just behind alcoholic beverages and ahead of biscuits, soft drinks, bottled water, fabric cleaners, and fruit juice.

    The convenience channel outpaced every competing modern trade format in the country over the 12-month period. Convenience store sales growth reached 45 percent, compared with 31 percent for direct sales and 11 percent for drugstores.

    Regional Shopper Divergence

    Household penetration widened alongside value growth. Kantar tracked 3,000 urban and rural households and found that 18.5 percent bought goods from convenience stores, up from 16.1 percent a year earlier. That shift brought an estimated 566,991 new families into 24-hour retail chains such as 7-Eleven, Ministop, and FamilyMart.

    Shopper behaviour varies sharply by geography. The National Capital Region accounts for the highest shopper volume, with 34 percent of homes using convenience stores, but residents there visit only five times a year on average. Mindanao holds fewer total convenience shoppers, yet those households visit nine times annually, making them the most frequent spenders in the country.

    Format Expansion Pressures

    Operators face higher inventory management demands as convenience stores shift from late-night snack stops into daily grocery replenishment hubs. Stocking bulky items like diapers and laundry detergents requires tighter shelf space allocation in stores that average only one to two checkout counters. Chains that fail to optimize their stock mix risk losing margin to traditional sari-sari neighbourhood stores that hold lower overheads.

    Philippine operators are matching this shift by accelerating store expansion beyond Metro Manila into secondary cities in South Luzon and Mindanao. Kantar new business development head Lourdes Deocareza attributed the channel expansion to faster consumer lifestyle routines across urban centers.

    Store counts across the major three chains continue to rise toward regional footprint targets, with full-year channel penetration and repeat trip frequency serving as the key benchmarks to watch.

  • GetUp Targets Hundreds of Coles Stores over Palantir AI Deal

    GetUp Targets Hundreds of Coles Stores over Palantir AI Deal

    Community advocacy group GetUp targeted hundreds of Coles stores across Australia with spoof digital billboards, challenging the supermarket operator over its enterprise partnership with US analytics vendor Palantir. The advertisements ran outside store entrances in July, mimicking the retailer’s signature red and white branding with the slogan: “Here at Coles, we’re always watching you.”

    The pushback followed Coles deploying software from the controversial US technology company to sharpen artificial intelligence and operational efficiency across its supermarket network. While the digital billboards were taken down quickly, the campaign triggered public debate over how large grocery chains handle customer data and explain tracking tools to shoppers.

    Public Scrutiny Over Store Analytics

    Supermarket operators across the Asia-Pacific region have accelerated investments in predictive analytics, automated inventory forecasting, and computer vision systems. Enterprise partnerships with overseas defence and intelligence contractors carry brand risks that standard retail IT upgrades do not. Consumer groups increasingly scrutinise the boundary between back-end supply chain optimisation and customer-facing surveillance.

    For grocery chains operating in concentrated retail markets, transparency around data architecture has become an operational necessity rather than an investor relations footnote. When retailers fail to define where data processing stops, third-party advocacy groups easily fill the information vacuum with negative messaging right at the store entrance.

    Retail AI Strategy Under Pressure

    The dispute reflects broader friction across Australian retail as grocers test advanced algorithmic tools to cut shrink and streamline operations. Coles had framed its AI rollout as an efficiency play, intended to modernise store workflows and stock management across its national footprint. Linking store-level operations to specialised analytics vendors has instead tested customer goodwill at a time of heightened consumer sensitivity around commercial data collection.

    Grocers managing similar automation rollouts across regional markets now face tighter questions regarding data sovereignty, third-party software governance, and in-store customer communications. Retailers will need to clarify operational boundaries as advocacy campaigns continue tracking corporate technology procurements.

  • Jollibee to List 7,251-Store International Unit in Hong Kong

    Jollibee to List 7,251-Store International Unit in Hong Kong

    Jollibee Foods Corporation is preparing to separate and list its international business in Hong Kong instead of the United States, carving out an overseas network of 7,251 restaurants across 33 countries.

    Shares in the Manila-listed parent rose 1.87 per cent following the move, which replaces a plan announced on January 6 to float the international arm on an American exchange.

    Richard Chong Woo Shin, currently chief executive of Jollibee Foods Corporation International (JFCI), will lead the standalone entity full-time once the separation concludes. Shin previously held senior roles at William Grant & Sons, Ralph Lauren, Bacardi and Altria. Jollibee Foods Corporation said the international business will operate with a lean corporate structure focused on capital allocation, investment opportunities and portfolio priorities, subject to listing committee approval from the Hong Kong stock exchange.

    Portfolio Tilt Toward Asian Beverages

    JFCI functions largely as a multi-brand operator with heavy exposure to Asian beverage chains. The international business holds full ownership of Smashburger, Tim Ho Wan, Yonghe King and Hong Zhuang Yuan, alongside controlling stakes of 80 per cent in The Coffee Bean & Tea Leaf, 70 per cent in South Korea’s Compose Coffee, 60 per cent in Highlands Coffee operator SuperFoods Group and 51 per cent in Milksha.

    Jollibee Foods Corporation ended June with 10,767 outlets worldwide under 19 brands, with overseas locations accounting for nearly 70 per cent of the total network. International system-wide sales climbed 25.4 per cent in the second quarter, while overseas same-store sales rose 4.4 per cent.

    Regional momentum is heavily concentrated in Asian markets. In Vietnam, system-wide sales jumped 47.6 per cent in the second quarter on same-store sales growth of 17.9 per cent. South Korea’s Compose Coffee added 145 stores during the first half, opening roughly 30 outlets a month. In China, Yonghe King reached 537 restaurants, with 65 per cent operating under franchise agreements and a target to reach 70 per cent by the end of the year.

    Shifting Away From Capital-Heavy Expansion

    Listing in Hong Kong aligns JFCI’s capital structure with where its physical earnings actually compound. While the flagship Jollibee fried chicken brand commands strong name recognition in Western markets, its North American presence remains tiny and capital-intensive compared to its Asian coffee and fast-casual footprint. The group ended June with 340 North American outlets, down from 357 a year earlier. Of those, the Jollibee banner ran 108 stores, including 106 company-owned sites and just two franchised locations.

    That balance sheet model is changing slowly. Jollibee launched its US franchising programme in March 2025 and secured seven multi-unit development groups by July, aiming for 330 franchised American locations by 2030. In the second quarter, US Jollibee stores posted a 9.8 per cent gain in same-store sales, marking 66 consecutive months of growth. Smashburger increased same-store sales by 7 per cent, though its store count fell from 203 to 180 as underperforming units were shuttered.

    Since the announcement on January 6, 2026 to list our international business, we have been doing the detailed work required to establish two strong, independent companies. That work has reinforced our conviction in the listing and has led us to conclude that Hong Kong is the market best aligned with JFCI’s business, geographic footprint, and long-term ambitions.

    The Path to Hong Kong Trading

    The pivot to Hong Kong coincides with a sharp rebound in the city’s equity fundraising. Hong Kong Exchanges and Clearing chief executive Bonnie Chan stated that new listings in 2026 had raised more than US$40 billion, surpassing the roughly US$37 billion collected during all of 2025. Hong Kong has actively courted Southeast Asian consumer groups, with more than 150 regional issuers already listed, representing over US$4.3 billion in capital raised.

    Group president and chief executive Ernesto Tanmantiong has set a target to position the flagship Jollibee brand among the top five restaurant operators globally, up from its current 18th position on Brand Finance’s global ranking with a valuation of US$3.3 billion.

    Before JFCI begins trading in Hong Kong, Jollibee must resolve the composition of its portfolio assets. The parent group is currently evaluating a separate initial public offering in Vietnam for Highlands Coffee, which has grown from 56 outlets in 2012 to approximately 1,000 stores, with a target listing date in the first quarter of 2027 that could raise up to US$400 million.

  • Australian Grocery Baskets Rise 8.5% as Shoppers Trade Down

    Australian Grocery Baskets Rise 8.5% as Shoppers Trade Down

    Australian households face an 8.5 per cent jump in standard grocery costs, pushing four-person families to spend an average of $245 weekly at supermarket checkouts. That identical basket of goods climbed to $232 in July 2026 from $214 in March 2025, according to tracking data from consumer research firm Canstar.

    Overall household grocery spending rose two per cent year on year from an average of $240 per week, held down only because shoppers are actively ditching premium items and buying cheaper alternatives. Research from ANZ Institutional shows consumers are managing higher food costs by swapping beef for chicken, picking private-label staples like pasta and canned tomatoes, and structuring purchases around promotional cycles.

    Trading down to private labels

    Price scrutiny has altered basket composition across major supermarket chains. Canstar survey data indicates 40 per cent of shoppers cut back on discretionary treats and snacks, while 38 per cent spend extra time evaluating unit pricing on shelves. Another 30 per cent target marked-down stock, and 25 per cent now buy supermarket home brands instead of proprietary labels.

    The shift demonstrates how consumer adaptation blunts headline shelf inflation. Families who alter their purchasing baskets shield their weekly budgets, while those maintaining rigid preferences for items like fresh beef, dairy and convenience foods absorb the full weight of cumulative price gains.

    “Food inflation doesn’t just change prices; it changes habits,” said Matthew Mann, director of research and analysis at ANZ Institutional.

    Margin squeeze for national brands

    For packaged goods manufacturers and tier-one food brands, this behavioral pivot threatens market share in key dry-grocery and dairy categories. Major supermarket operators in Australia continue to expand their private-label ranges, securing margin while offering entry-level price points that squeeze branded suppliers off shelf space.

    Suppliers unable to fund trade promotions or justify premium pricing risk permanent volume losses as private-label loyalty solidifies. The margin pressure sits heavily on domestic food processors, who must navigate higher logistical and ingredient costs without full pricing power at the retail negotiating table.

    Tracking the checkout shift

    Cost pressures built steadily through 2025 before escalating into mid-2026, compounded by wider supply chain friction and energy costs. University of Sydney retail researcher Lisa Asher noted that real wage growth has failed to keep pace with cumulative food cost increases over that window.

    The key metric for Australian retail suppliers through the final quarter of 2026 is volume recovery in branded meat and snack categories as promotional discounting deepens.

  • Destination Italy Adds Two Frozen Pizza Lines Across Australia and New Zealand

    Destination Italy Adds Two Frozen Pizza Lines Across Australia and New Zealand

    Destination Italy expanded its frozen pizza lineup across Australia and New Zealand on September 7, 2026, launching two Italian-made varieties into regional supermarket freezers.

    Made in Italy, Woodfired Puttanesca and Woodfired Salame ship directly to Australian and New Zealand retailers catering to demand for imported convenience meals.

    Ingredients and Recipe Formats

    The Woodfired Puttanesca pizza uses a traditional tomato and mozzarella base topped with black olives, capers, and oregano. Woodfired Salame pairs that same base with sliced salami, produced in Italy before frozen transport.

    Both products rely on Italian-baked woodfired crusts to stand out from local alternatives. The format targets shoppers who want regional recipes without paying foodservice prices.

    Premium Competition in the Freezer Aisle

    Major grocers across Australia and New Zealand have steadily reallocated freezer space to imported and specialty private-label items over the past three years. Mainstream frozen pizzas face ongoing margin compression. That pressure has prompted distributors to push higher-value imported SKUs onto shelves.

    For retailers, imported lines offer higher basket values in a category historically dominated by discount domestic labels. Cold-chain freight costs and exchange-rate swings between the euro and the Australian dollar remain key operational hurdles, squeezing margins when shipping volumes fluctuate.

    Retail Distribution Timelines

    Destination Italy built its initial ANZ footprint around core woodfired SKUs before widening the range with specialized regional flavor profiles. Across the supermarket frozen sector, brands are taking similar premium routes, using origin-certified manufacturing to defend shelf share.

    Supermarkets will roll out the two new varieties across national freezer networks through the remainder of the month.

  • F&N Magnolia Launches Sanrio Ice Confection Line Across Singapore

    F&N Magnolia Launches Sanrio Ice Confection Line Across Singapore

    F&N Magnolia rolled out a limited-edition strawberry and yoghurt ice confection across Singapore retail channels on September 3, priced at S$2.20 for single sticks and S$8.40 for four-packs.

    The launch pairs the heritage dairy brand with Sanrio characters My Melody and Kuromi across impulse and take-home formats. Alongside the stick multipacks, the company introduced a repackaged My Melody and Kuromi raspberry ripple ice cream tub priced at S$6.42.

    Channel Distribution and Pricing

    F&N split the product formats by channel to target distinct shopping occasions. Convenience stores carry the single-serve stick line at S$2.20, while leading supermarket operators stock the four-stick multipacks at S$8.40 and the redesigned tubs at S$6.42. All items carry halal certification to serve the broader domestic market.

    To drive basket size in grocery aisles, the brand attached a gift-with-purchase promotion running through the end of October 2026. Shoppers who buy two multipacks receive a branded travel organiser set valued at S$19.90, subject to stock availability.

    Character Licensing in Dairy Retailing

    Packaged food manufacturers across Southeast Asia rely heavily on co-branded character tie-ups to drive short-term volume in crowded freezer cabinets. Licensing recognizable IP allows legacy dairy labels to capture younger demographics and impulse buyers without reformulating entire permanent portfolios.

    The promotion runs across participating supermarket chains until October 31, 2026, or until premium gift stocks are exhausted.

  • Coles Drops Palantir Contract After Activist Campaign over Data Use

    Coles Drops Palantir Contract After Activist Campaign over Data Use

    Coles will end its enterprise partnership with United States software vendor Palantir. The decision follows an 85,000-signature petition against deploying military-grade data systems in Australian supermarkets.

    Company officials confirmed the business will let the three-year agreement expire in 2027 rather than sign an extension.

    Rostering and Supply Chain Deployment

    The grocer brought in Palantir in early 2024 to manage backend administration across its store network. The software scheduled shift rosters and coordinated bakery production runs. It also modelled inventory flow through distribution centres.

    Community advocacy group GetUp launched a campaign against the deal shortly after the contract took effect. Activists cited Palantir’s contracts with the United States Immigration and Customs Enforcement agency and the Israeli Defence Forces. They argued military-grade systems had no place in retail operations.

    A spokesperson for the chain rejected claims that the platform ever tracked shoppers or gathered aisle surveillance feeds. “Palantir’s technology has delivered value across Coles’ operations, particularly in rostering, store operations and supply chain planning,” the spokesperson said.

    The Enterprise Risk in Retail AI

    Supermarket operators across the Asia-Pacific region are rushing to automate workforce management and stock replenishment. Yet vendor selection brings brand exposure that procurement teams often underestimate. When enterprise software providers run heavy defence and state intelligence divisions, consumer-facing retailers absorb the reputational fallout directly at the checkout.

    Coles chose to let the contract lapse quietly at its natural term rather than terminate immediately. That approach lets the grocer run down existing IT commitments while scouting replacement platforms for store-level forecasting and labor scheduling.

    A Push Toward Neutral Systems

    Earlier, the company maintained Palantir never controlled internal grocer data or held rights to repurpose operational metrics. It declined to detail commercial reasons for walking away from the contract when asked for clarification.

    Chains across Australia and the wider region face sharper scrutiny over in-store data management. Woolworths and Coles both encountered customer resistance in recent years when testing automated checkout monitoring and digital loss-prevention systems.

    Attention now turns to how the retailer will transition its store scheduling and supply chain workflows to alternative software providers before the agreement concludes in 2027.